


EN
FP (TSE:7947) Could Be 26% Undervalued As Board Reviews Forecasts And Pricing
FP Corporation (TSE:7947) has put its next fiscal year under the microscope, with a board meeting on October 30 set to review consolidated forecasts and the rationale behind its pricing and cost decisions.
FP Corporation's share price has gained momentum in recent months, with a 90 day share price return of 17.52% and a year to date share price return of 13.21%. The 1 year total shareholder return of 21.79% contrasts with a 5 year total shareholder return that is down 14.12%, which may suggest that investors are reacting more to recent pricing and cost actions than to longer term history.
Scan how FP's recent repricing theme compares with other packaging and materials businesses by checking stocks in the 15 high quality undervalued stocks.
For FP Corporation, the sharp rebound after a weak five year stretch raises a simple tension. Are investors finally catching up with the underlying container business, or has sentiment moved faster than the fundamentals support?
Preferred P/E of 16.1x: Is it justified?
Pricing for FP Corporation now embeds a P/E of 16.1x, which sits well above both peers and the wider Japan packaging group. This suggests that the recent share price strength is leaning on a richer earnings multiple rather than a depressed entry point.
The P/E ratio links FP Corporation's market value to its earnings, giving a snapshot of how much investors are willing to pay for each unit of profit. For a mature food container producer operating solely in Japan, this kind of yardstick can show whether the market is paying up for steady profitability, dividend reliability at 2.46%, and consistent earnings growth of 5.6% per year over the past five years, or instead stretching beyond what recent performance supports.
The current reading of 16.1x sits above the JP Packaging industry average of 8.8x and above the peer group average of 9.6x. This signals that the market is already assigning FP Corporation a premium tag. The estimated fair P/E of 12.7x is lower than where the stock trades, so the present valuation implies investors are paying more than the level suggested by that fair ratio. The multiple may have room to compress toward that fair value anchor if sentiment cools.
Explore the SWS fair ratio for FP.
Result: Price-to-Earnings of 16.1x (OVERVALUED)
Still, the entire FP Corporation story leans heavily on one market, Japan, and on disposable food containers, so any shift in local demand or regulation could unsettle that upbeat multiple.
Find out about the key risks to this FP narrative.
Another View On FP Corporation's Valuation
FP Corporation looks expensive on a 16.1x P/E, yet our DCF model paints a different picture. At ¥2,965, the shares trade about 26.3% below an estimated future cash flow value of ¥4,022.94. One method points to a rich multiple; the other points to a discount. Which lens do you trust more?
Look into how the SWS DCF model arrives at its fair value.
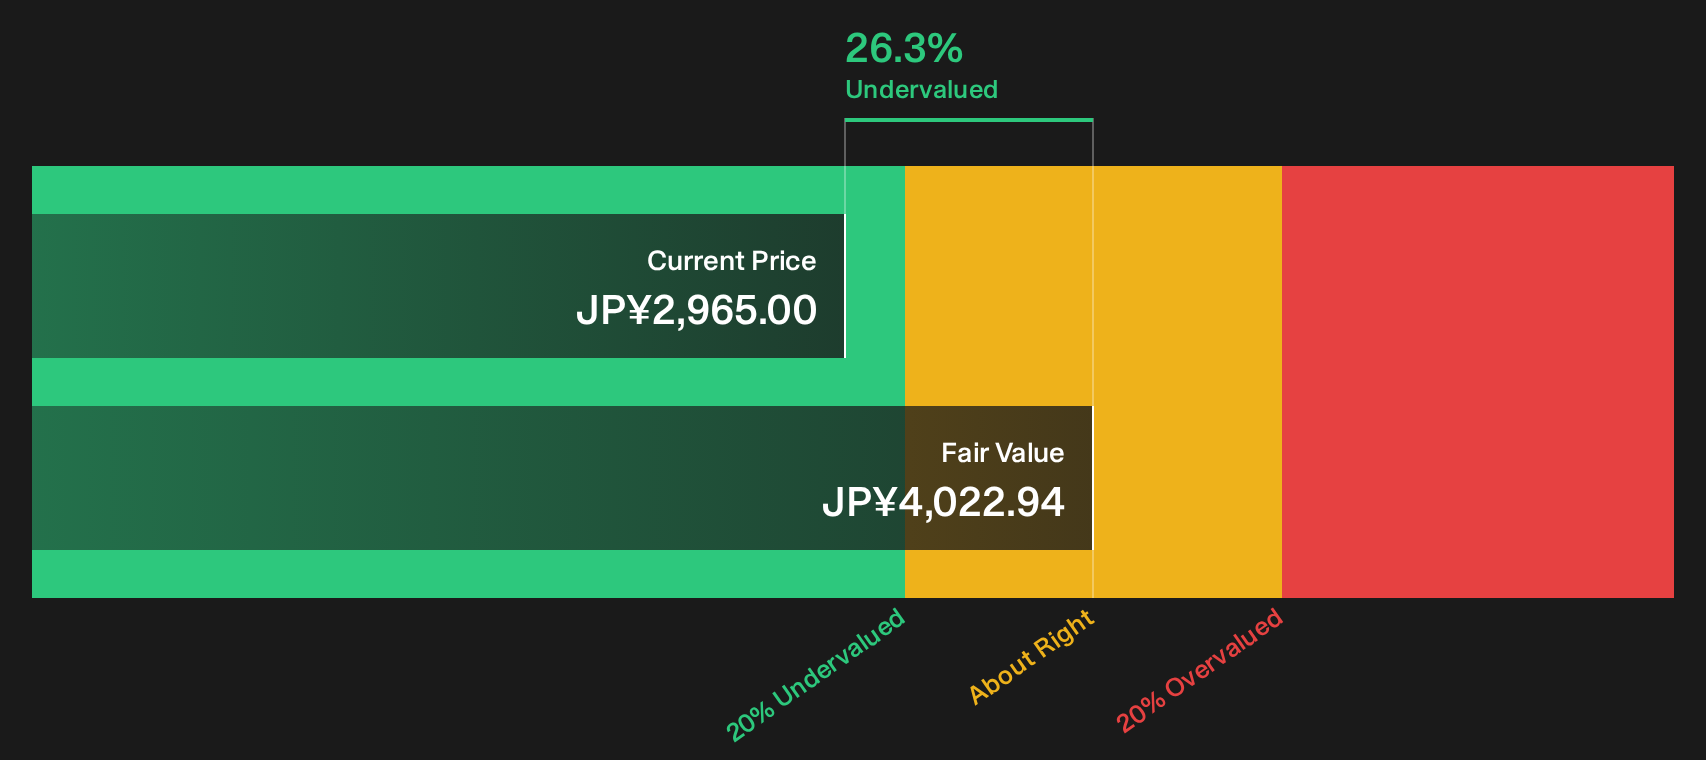
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out FP for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 15 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Feeling that FP Corporation’s setup leans optimistic or cautious right now is only half the story. Act quickly, review the data that matters most to you, then weigh those positives for yourself with the 4 key rewards
Looking for more investment ideas beyond FP Corporation?
If FP Corporation has sharpened your focus on pricing and valuation, do not stop here. Broaden your watchlist with a few targeted hunting grounds.
- Target resilient balance sheets that can handle shocks and still fund growth with a curated list of solid balance sheet and fundamentals (22 results).
- Hunt for mispriced opportunities where quality and valuation align by scanning the 15 high quality undervalued stocks.
- Zero in on under-the-radar stories before they hit the mainstream by tracking a focused 71 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com