


EN
Earnings Beat Could Be A Game Changer For Komeri (TSE:8218)
- Komeri Co., Ltd. reported half year results to September 30, 2026, with sales of ¥201,237 million and net income of ¥11,310 million, and basic earnings per share from continuing operations of ¥241.68.
- The latest half year figures show both sales and profit above the prior period. This indicates that Komeri’s core retail operations are currently supporting higher earnings per share.
- The focus now is on how Komeri’s higher half year sales and earnings per share may reshape the investment narrative that investors rely on.
What Is KomeriLtd's Investment Narrative?
To own KomeriLtd, you need to be comfortable with a relatively steady retail story. The latest half year numbers, with higher sales and earnings per share than a year ago, point to a business that is currently executing on its home improvement format and ancillary services. In the short term, the key swing factors are likely to be store level execution, product mix, and how well management controls costs in a low growth demand backdrop where forecasts point to modest revenue and profit expansion rather than fast acceleration.
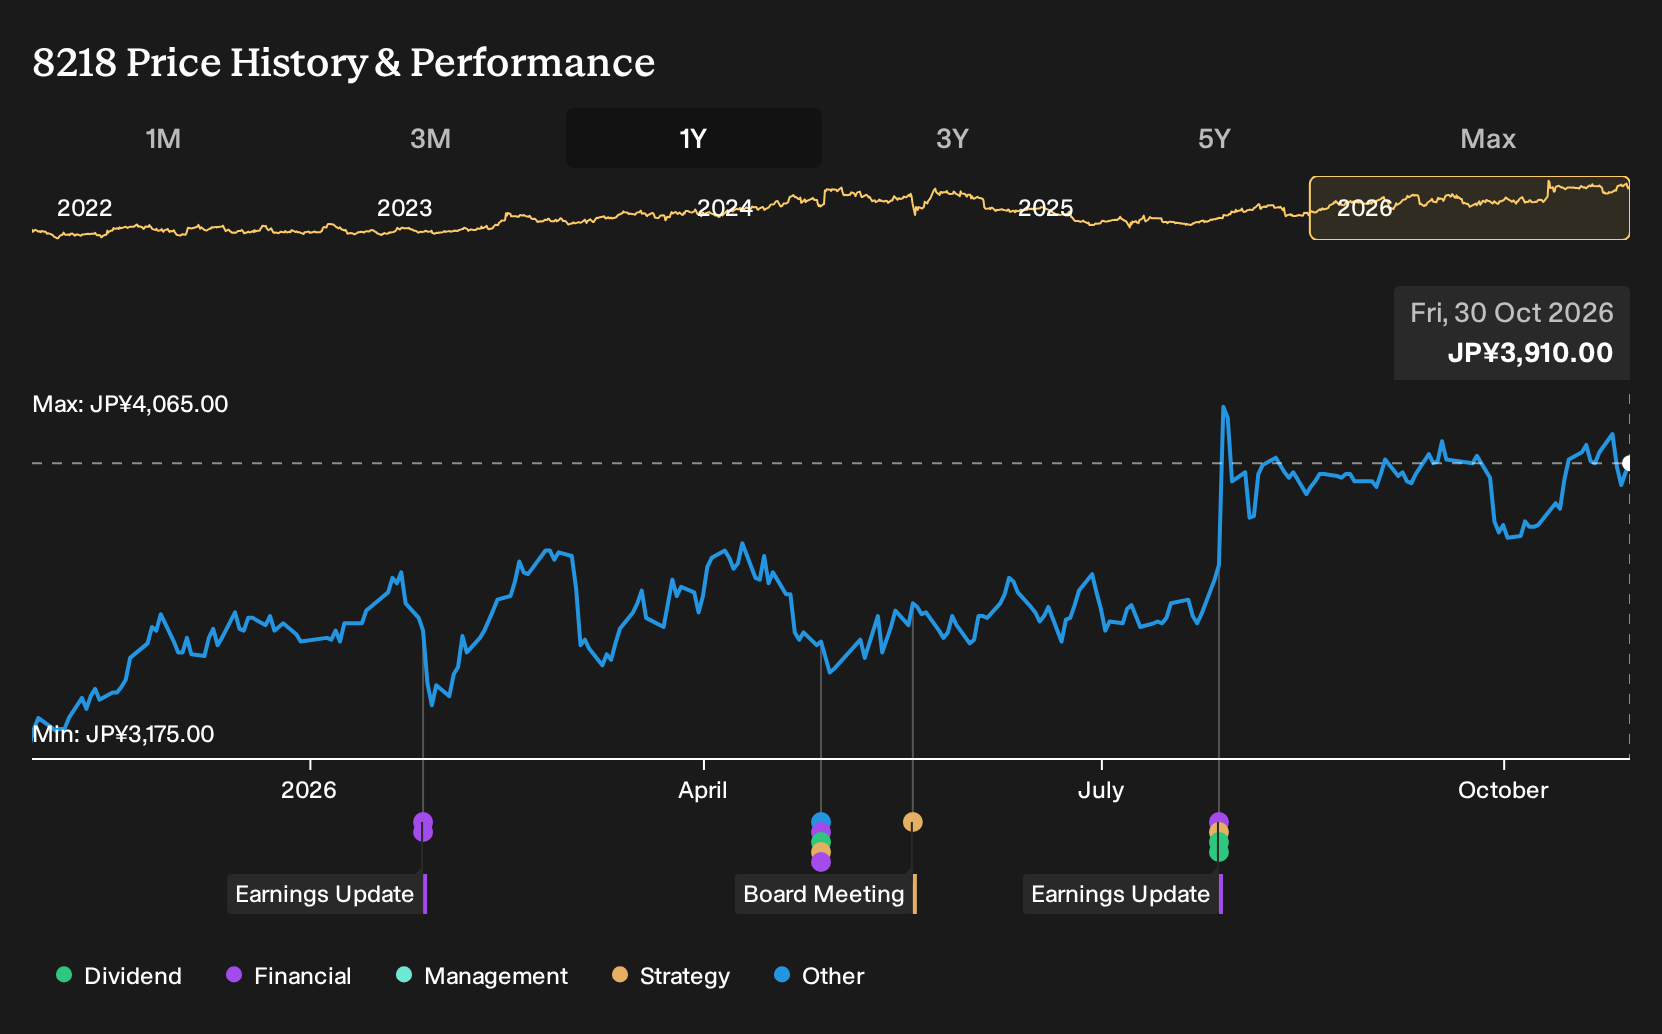
Valuation adds another layer. The shares trade on a P/E that sits below both peer and industry averages, and recent performance slightly exceeded the broader Japanese market over one year. That combination, together with forecasts that still point to earnings and revenue growth, underpins the investment story for a more patient holder who values seasoned management and a long operating history. The new half year report slots into that narrative as more confirmation than reset. However, it does nudge the focus back onto whether current margins can be held if conditions become less friendly.
Even so, there is a quieter issue in the background that could matter far more than the latest earnings beat if...
There's only one way to know the right time to buy, sell or hold KomeriLtd. Head to Simply Wall St's company report for the latest analysis of KomeriLtd's Fair Value.
Decide For Yourself
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so consider relying on your own analysis and judgment.
- A great starting point for your KomeriLtd research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for KomeriLtd. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate KomeriLtd's overall financial health at a glance.
Looking For More Ideas Beyond KomeriLtd?
Once you have a view on KomeriLtd, it can help to compare that thesis with opportunities that share similar qualities or offer very different risk and return profiles. The Simply Wall St Screener lets you filter for exactly the type of businesses you want to research next.
- If resilience matters most to you, start with companies that pair measured risk with steadier fundamentals through the 24 resilient stocks with low risk scores.
- Income focused investors can zero in on businesses offering strong cash returns to shareholders by checking out the 27 dividend fortresses.
- For those who want robust finances and clean balance sheets at the core of their process, the list of solid balance sheet and fundamentals (22 results) is a direct way to narrow the field.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com