


EN
Vår Energi (OB:VAR) Shares Jumped, What Is Behind The Latest Attention?
Vår Energi (OB:VAR) just packed several updates into one day. Fresh third quarter results, new full year 2026 production guidance, and a proposed third quarter dividend all landed on 21 October 2026.
The latest results and dividend proposal have landed after a strong run in Vår Energi’s shares. The stock is now at NOK59.1 with a year-to-date share price return of 76.95%, alongside a 1-year total shareholder return of 95.81%, which signals building momentum rather than a short-term spike.
Spot similar momentum in other energy names by scanning our curated list of 16 nuclear energy infrastructure stocks as you weigh Vår Energi against peers that are benefiting from heavy investment in long-term energy infrastructure.Vår Energi now has a sharply higher share price, bigger reported earnings and a fresh dividend proposal on the table. Is the move mainly driven by stronger fundamentals, or by investors crowding in on sentiment as guidance tightens?
Most Popular Narrative: 7% Overvalued
Vår Energi’s most followed narrative puts fair value at NOK55.07 against the latest close at NOK59.1, so the story currently frames the stock as pricing in more than that fair value estimate while focusing heavily on its project pipeline and cost profile.
Large, flexible project pipeline (30+ early phase projects, over 3 billion barrels of resource potential) and a leading exploration track record position the company for organic, long-duration growth, helping sustain and increase future revenue. Ongoing reduction in unit operating costs (targeting approximately $10/boe from approximately $12.2/boe in H1, driven by new low-cost fields and digitalization) and rebidding contracts will structurally improve net margins and earnings resilience, even in volatile pricing environments.
See why 53 investors see Vår Energi as 7% overvalued.
Result: Fair Value of NOK55.07 (OVERVALUED)
Still, the Vår Energi story can change quickly if energy transition policies accelerate or if higher decommissioning and carbon costs reduce those margin assumptions.
Find out about the key risks to this Vår Energi narrative.
Another View: SWS DCF Model Flips The Story
The popular narrative has Vår Energi slightly overvalued on a fair value of NOK55.07. The SWS DCF model presents a different perspective. At NOK59.1, the shares are described as trading about 43.5% below an estimated future cash flow value of roughly NOK104.59, which frames today’s price as a discount rather than a premium. Which set of assumptions do you trust more?
For a closer look at how those future cash flows are stitched together and where the big sensitivities lie, Look into how the SWS DCF model arrives at its fair value.
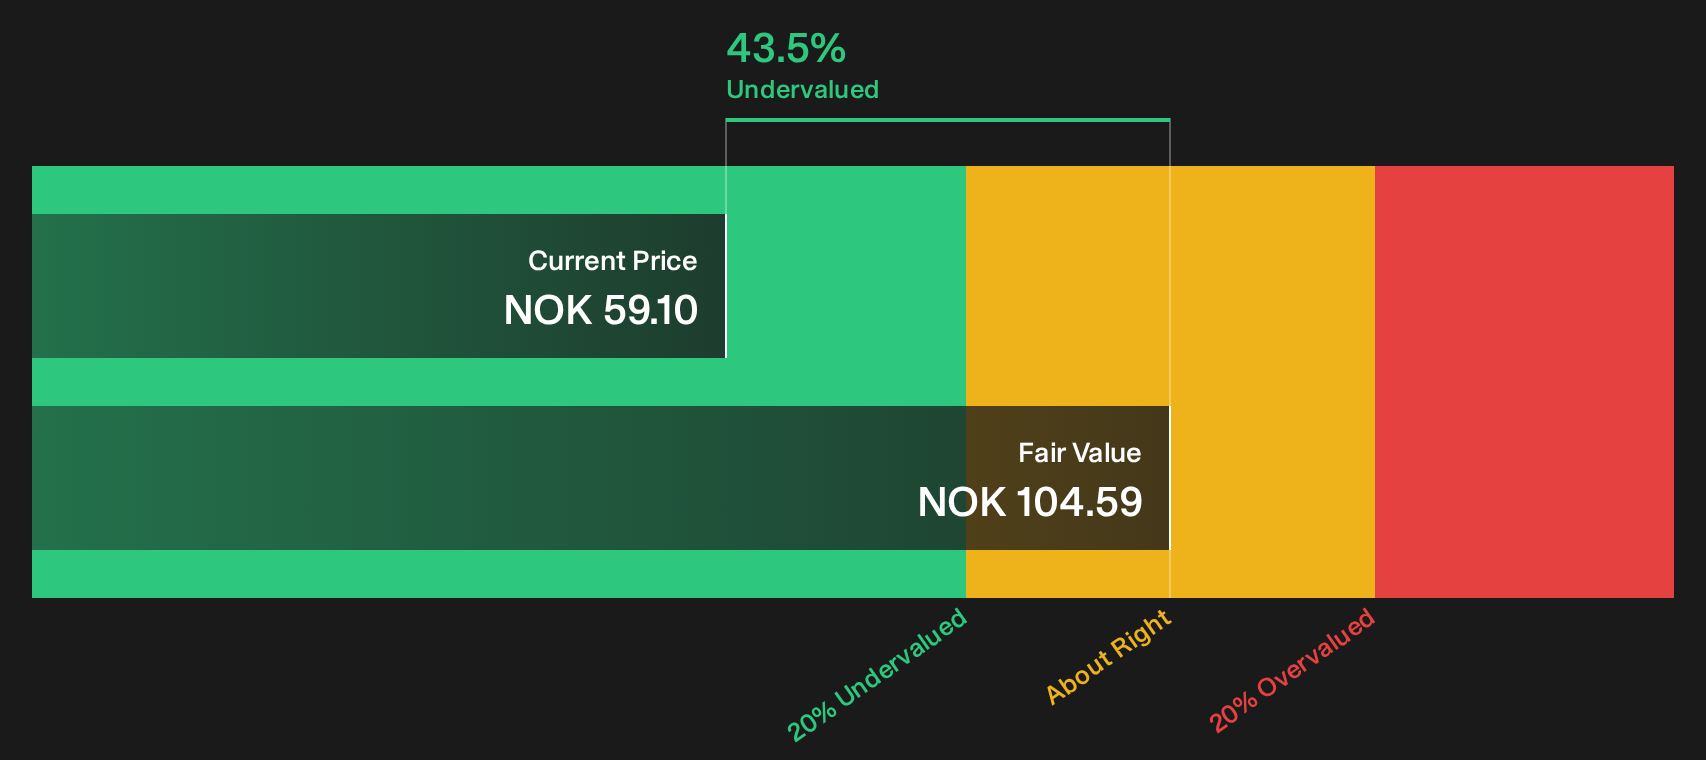
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Vår Energi for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 199 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Vår Energi is clearly split, which is exactly when fresh data can matter most for your decision. Move fast, review both the upside and the risks, then ground your own stance in the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Vår Energi?
If you stop with Vår Energi, you could miss other opportunities that fit your style, so widen your search with a few focused stock screens.
- Target dependable cash generation and steady fundamentals by running a list of solid balance sheet and fundamentals (203 results) that highlights businesses built on stronger financial footing.
- Hunt for mispriced opportunities by scanning the 199 high quality undervalued stocks that filters for quality companies trading below their estimated worth.
- Prioritize resilience and capital preservation by reviewing a 218 resilient stocks with low risk scores tailored to highlight stocks with lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com