


EN
What Just Happened With Shimano (TSE:7309)?
Shimano (TSE:7309) is back in focus after raising its full year earnings forecast and reporting higher nine month sales and net income, along with a proposed shift to one year director terms.
The raised guidance and nine month earnings update arrived alongside a sharp swing in sentiment, with Shimano’s share price delivering a 10.86% 7 day return and a 15.40% 30 day share price return. The 1 year total shareholder return of 29.57% sits against a weaker 5 year total shareholder return that declined 30.84%, suggesting momentum has recently strengthened even though longer term holders have experienced a tougher stretch.
Spot opportunities by riding similar sentiment shifts through our hand picked 71 high quality undiscovered gems, featuring fundamentals that investors may be starting to reprice.After that sharp move, Shimano now trades above the average analyst target, while screens still flag a meaningful intrinsic discount. Which reference point is closer to fair value as the dust settles on the upgrade?
Price-to-Earnings of 29.9x: Is it justified?
Shimano now trades at a P/E of 29.9x, which places the ¥20,570 share price at a clear premium to both its peer group and the wider JP Leisure industry.
The P/E ratio compares what investors are currently paying for each unit of earnings to what those profits actually are. For a business like Shimano that sells bicycle components and fishing tackle, a higher multiple usually reflects expectations for steadier profit growth, strong competitive positioning, or lower perceived risk compared with other consumer durables stocks.
Recent fundamentals give some context to that premium. Earnings grew 13.3% over the past year after declining 23.9% per year over the past 5 years, and net profit margins of 11.8% are above last year’s 10.9%. That combination of improving profitability and high quality earnings can help justify a richer valuation, although our model-based view of fair value points in a different direction over time.
The comparison with peers is stark. Shimano’s P/E of 29.9x is well above the JP Leisure industry average of 16.6x and also above the peer average of 17.8x. The estimated fair P/E ratio of 20x sits much closer to those benchmarks and represents a level the market could move towards if expectations cool or earnings catch up with the price.
Explore the SWS fair ratio for Shimano.
Result: Preferred multiple of Price-to-Earnings of 29.9x (OVERVALUED)
Still, the narrative can flip if Shimano’s recent share price strength cools faster than earnings progress, or if analyst targets begin to anchor sentiment more tightly.
Find out about the key risks to this Shimano narrative.
Another view on Shimano’s value
The P/E premium paints Shimano as expensive, yet the SWS DCF model points the other way. At a share price of ¥20,570, the stock is flagged as trading about 24.9% below an estimated future cash flow value of ¥27,375.32. That raises a simple question: Which signal do you trust more, earnings today or projected cash flows?
Look into how the SWS DCF model arrives at its fair value.
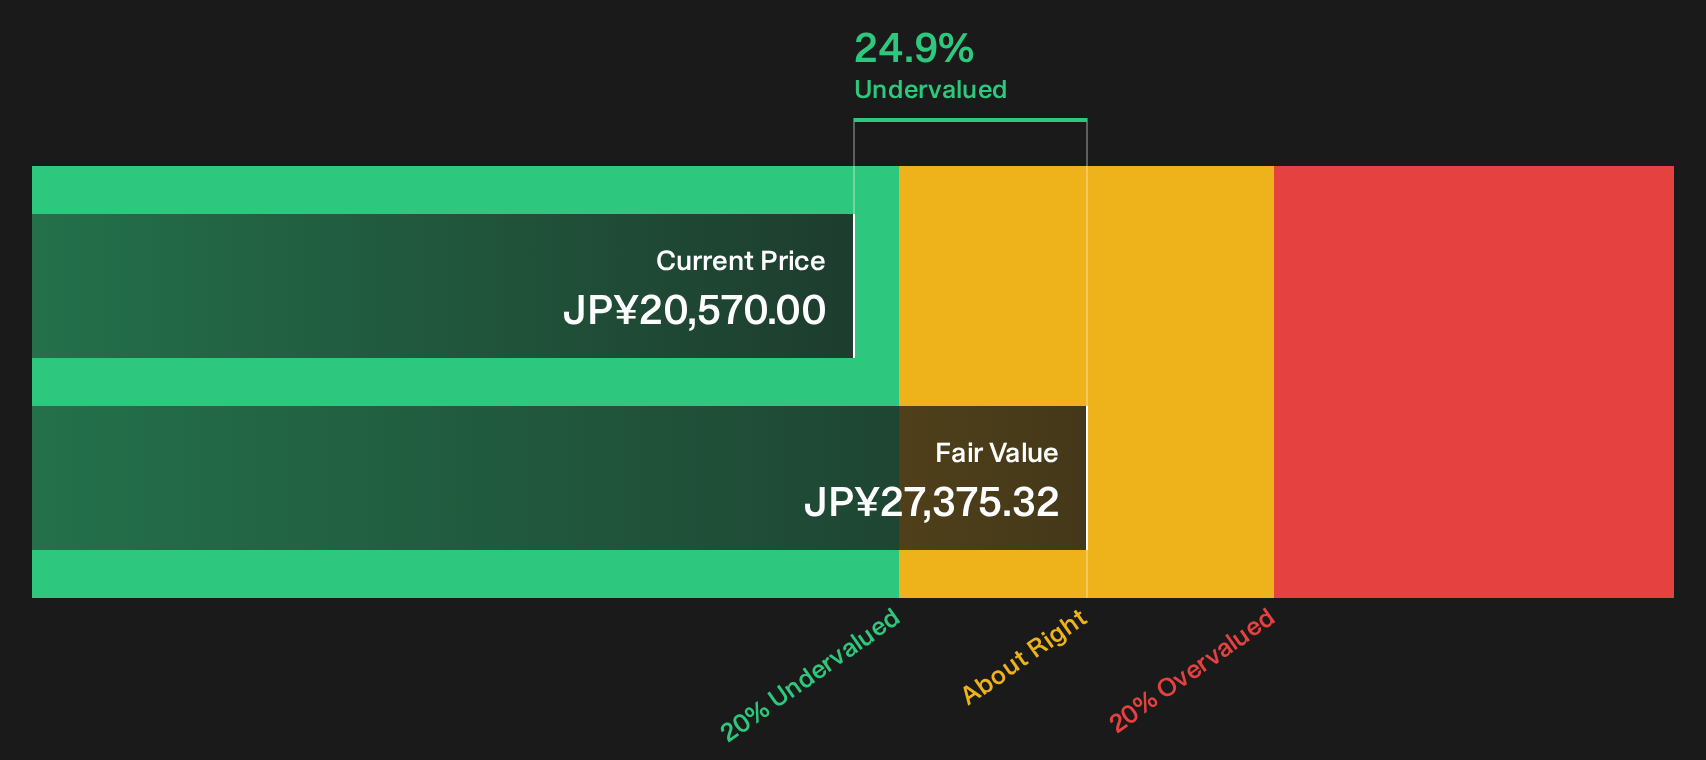
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Shimano for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 15 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Shimano has clearly shifted, so now is the moment to inspect the numbers yourself and pressure test every signal on your screen. To understand what investors are optimistic about and how those positives stack up against your own thesis, review the 3 key rewards
Looking for more investment ideas beyond Shimano?
If Shimano has prompted you to reassess your watchlist, now is the moment to widen the search and stack the odds with data driven stock ideas.
- Target potential mispricings early in their journey by scanning the 71 high quality undiscovered gems that already show solid fundamentals and room for attention to catch up.
- Prioritise resilience in tougher markets by focusing on a list of solid balance sheet and fundamentals (22 results) so you are not relying solely on optimistic forecasts to support your thesis.
- Build a cash flow focused watchlist by hunting for income ideas among 27 dividend fortresses that combine yield with underlying business strength instead of chasing payouts blindly.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com