


EN
How Investors Are Reacting To OneMain Holdings (OMF) Earnings Beat
- OneMain Holdings reported Q3 2026 net income of US$185 million and diluted EPS from continuing operations of US$1.60, while recording US$469 million of net charge offs and declaring a quarterly dividend of US$1.05 per share.
- The mix of stronger than expected revenue and profit, improving credit trends and continued capital returns suggests OneMain Holdings is relying on disciplined underwriting and balance sheet management to support its personal loan, auto and card portfolios.
- We will now consider how OneMain Holdings' investment narrative could be affected by its stronger than expected Q3 revenue and earnings performance.
Scan beyond OneMain Holdings and evaluate other consumer lenders with strong balance sheets using our hand picked list of solid balance sheet and fundamentals (25 results) as a comparison set.
OneMain Holdings Investment Narrative Recap
To own OneMain Holdings, you need to be comfortable with a consumer lender that leans into higher yielding products while working hard to keep credit losses contained. The Q3 result showed solid earnings power alongside US$469 million of net charge offs. The near term story still turns on whether improving delinquency trends can offset pressure from the card and legacy loan books.
The most important short term catalyst remains execution on receivables growth in personal loans, auto and cards, while avoiding loss rates that erode margins. The biggest risk is that card charge offs and the older pre August 2022 loans keep credit costs elevated. The latest numbers do not remove that risk, but they show some operational progress.
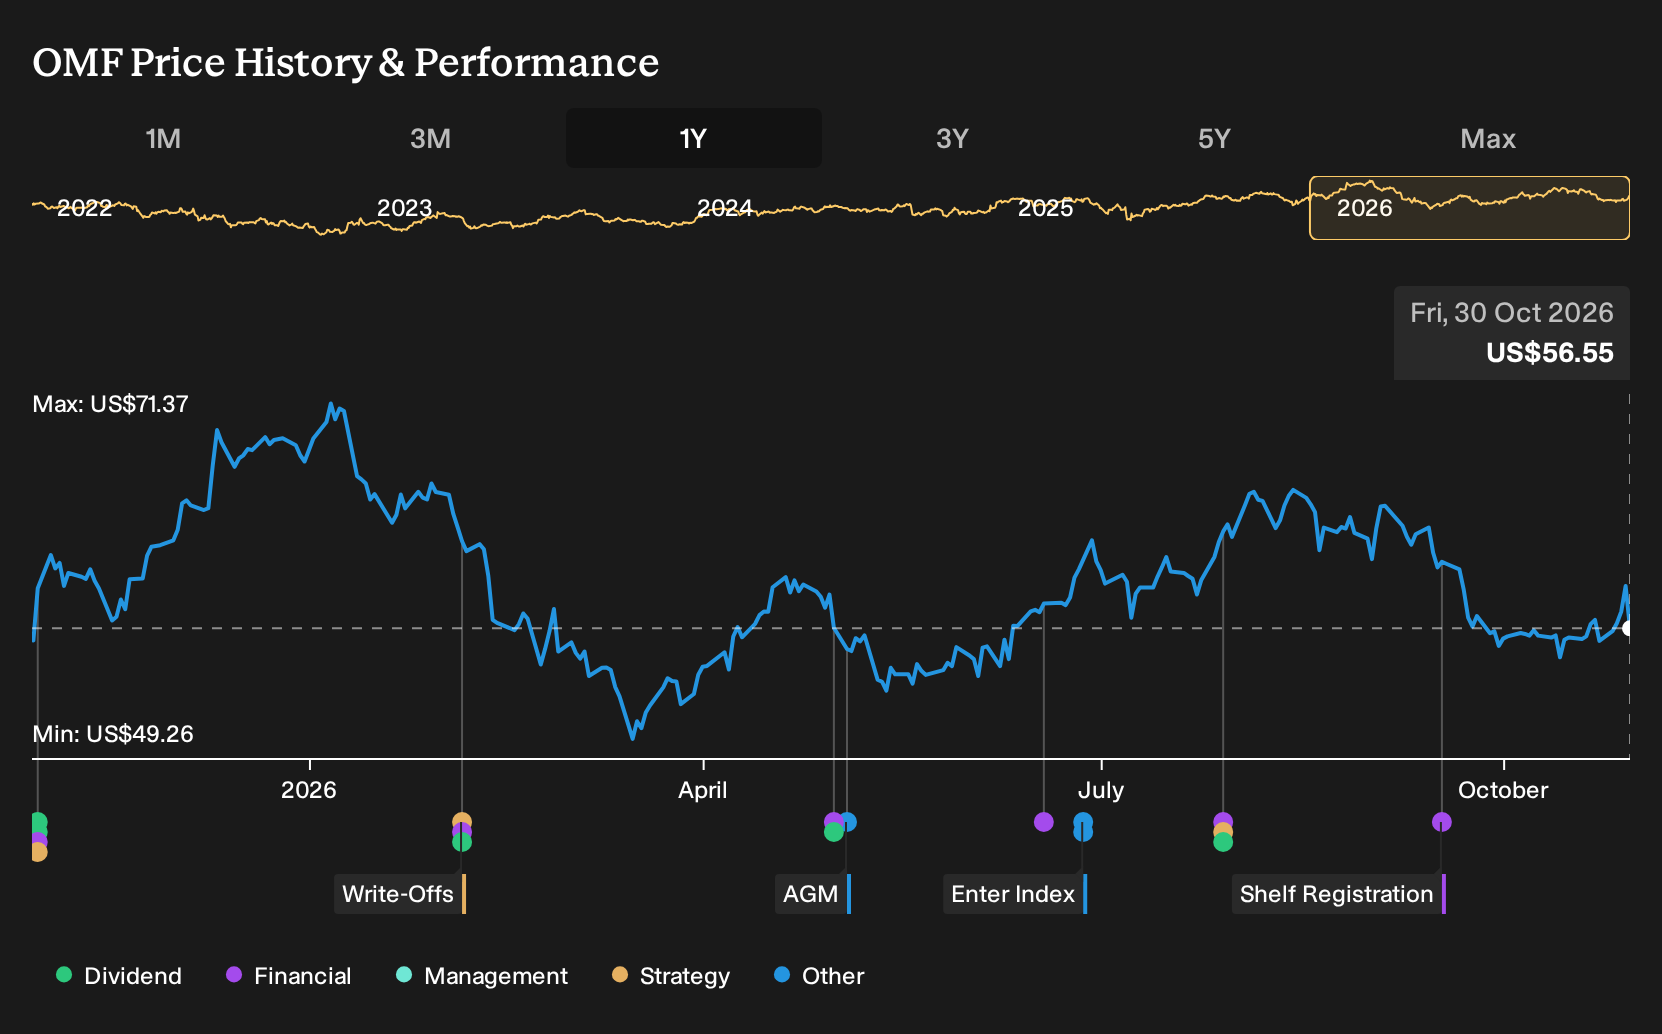
The US$1.05 quarterly dividend declared on October 30, 2026, is the announcement that matters most here. It signals that OneMain Holdings is continuing to return cash even while absorbing higher net charge offs. For you, the key question is whether the underlying earnings base comfortably supports both that payout and ongoing investment in receivables growth.
This dividend sits alongside previous buybacks and creates a potential catalyst around capital return consistency. If credit metrics stay within management’s comfort zone, ongoing dividends and any repurchases can influence per share outcomes. If losses rise or funding conditions tighten, that same commitment to capital return could become a pressure point rather than a support.
OneMain Holdings' narrative projects US$7.3b revenue and US$1.2b earnings by 2029. This aligns with analysts assuming 34.4% yearly revenue growth and implies an earnings increase of about US$419m from US$781.0m today.
Uncover why OneMain Holdings' fair value indicates a 21% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between about US$61.6 and US$68.6 per share, so private investors are not treating OneMain Holdings as wildly mispriced. Those views were set before the latest earnings, higher net charge offs and reaffirmed dividend, so you may want to weigh fresh credit risks and capital returns against those earlier opinions.
Explore another OneMain Holdings fair value estimate, including one that suggests as much as 21% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your OneMain Holdings research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for OneMain Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate OneMain Holdings' overall financial health at a glance.
Looking For More Ideas Beyond OneMain Holdings?
If the OneMain Holdings story has sharpened your thinking, use that momentum to widen your opportunity set. A targeted screener helps you compare this lender against other businesses that share the qualities you care about most, whether that is value, resilience, or income.
- If you want to focus on quality at a reasonable price, review companies in the 29 high quality undervalued stocks and see which ones warrant a closer look.
- For investors who put capital preservation first, filter for sturdier balance sheets and steadier cash flows using the 30 resilient stocks with low risk scores as a starting point.
- If income is your priority, scan for higher yield opportunities that may complement OneMain Holdings by running through the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com