


EN
Vail Resorts (MTN) Proxy Fight Puts Its Fair Value Story To The Test
Vail Resorts (MTN) has moved into the spotlight after filing a definitive proxy statement and urging investors to back its nine director nominees in a contested board fight with activist Oasis Management.
Against this backdrop, Vail Resorts’ 1-month share price return of 10.68% and year-to-date gain of 13.34% suggest momentum has picked up recently, even though the 5-year total shareholder return of 48.91% decline points to a tougher longer-term journey for investors.
Scan how Vail Resorts compares with other potential rebound stories by checking a curated set of 18 high quality undiscovered gems that investors may be overlooking right now.
Vail Resorts now trades slightly above the average analyst target yet screens at a sizable discount to some fair value estimates. After the recent rebound and ongoing proxy fight, is that a caution signal or a mispricing?
Most Popular Narrative: 2% Overvalued
On the latest widely followed view, Vail Resorts screens close to fairly priced, with a fair value of $148.36 against a last close of $151.83. The current premium is small, but it still raises the question of what could shift the story from here.
Vail Resorts expects its Resource Efficiency Transformation Plan to move beyond the original goal, with $106 million of annualized savings targeted by the end of fiscal 2026 and a further $30 million of technology efficiencies identified through fiscal 2028. This points to ongoing support for net margins and earnings. The company is guiding to about $25 million of incremental resource efficiency savings in fiscal 2027 that are intended to help offset around 4% labor and expense inflation along with higher incentive compensation and marketing, which directly links future cost discipline to operating margin stability.
See why 12 investors see Vail Resorts as 2% overvalued.
Result: Fair Value of $148.36 (OVERVALUED)
Still, the recent Epic pass unit decline and management’s indication that a second very poor snow year could trigger a dividend cut both hang over the Vail Resorts narrative.
Find out about the key risks to this Vail Resorts narrative.
Another View: Vail Resorts And The Earnings Multiple Gap
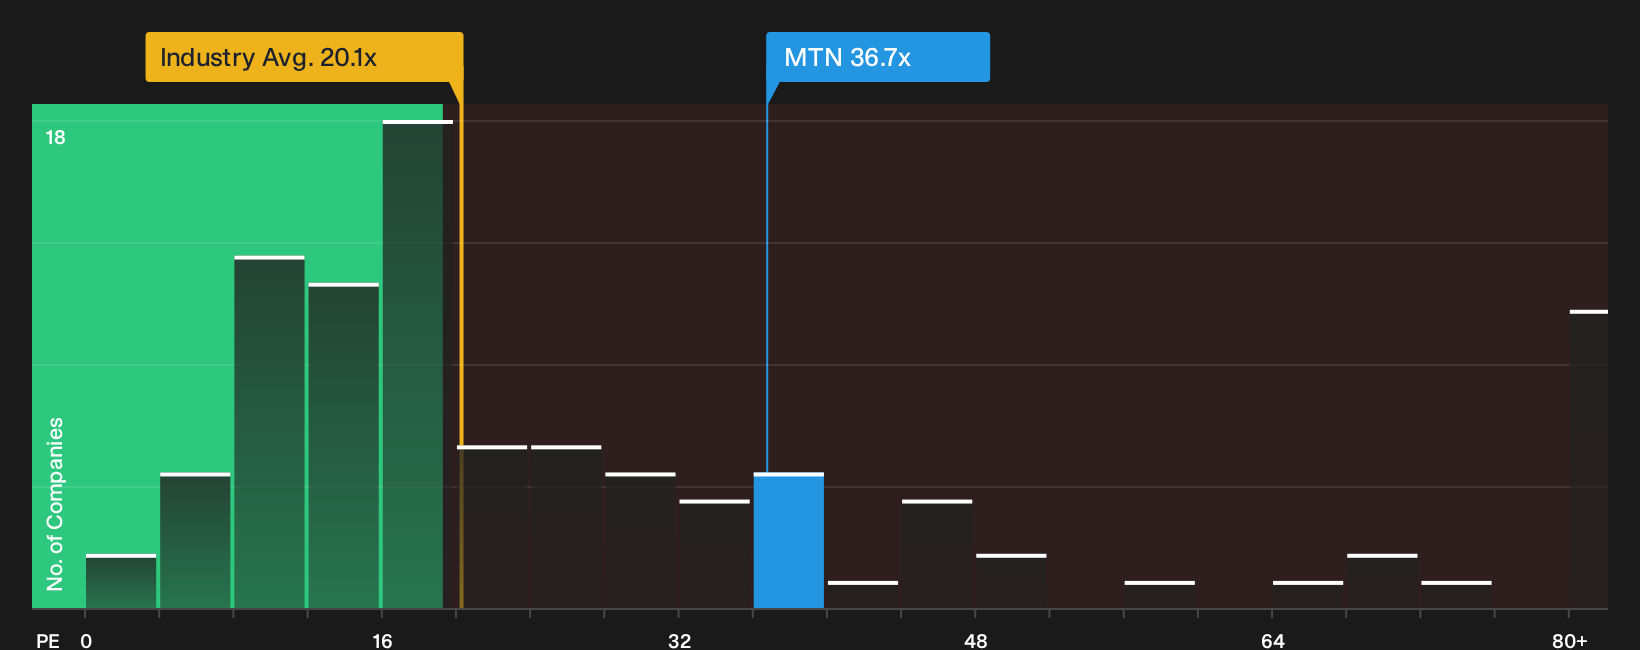
That earlier fair value of $148.36 comes from analysts’ long range earnings assumptions. A simple P/E check tells a different story. Vail Resorts trades on 36.7x earnings, while peers average 21.9x and the fair ratio is 23.1x. That is a hefty premium. Is it justified by future profit growth, or is it valuation risk building up?
To see how this pricing gap plays out across different earnings scenarios, take a closer look at our valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Vail Resorts for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Vail Resorts so far. If you want to move fast and back your own judgment, start by weighing its 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Vail Resorts?
If the Vail Resorts story has you thinking harder about price, quality, and risk, do not stop here. Broaden your opportunity set before the next move.
- Target resilient balance sheets and steady fundamentals by running a focused search through our list of solid balance sheet and fundamentals (25 results).
- Zero in on potential value opportunities by checking companies that screen as 29 high quality undervalued stocks.
- Prioritize sleep-at-night holdings by filtering for 30 resilient stocks with low risk scores that may better match your risk tolerance.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com