


EN
KONE Oyj (HLSE:KNEBV) Raised Full Year Guidance, Is The Stock Already Expensive?
Why KONE Oyj’s latest earnings and guidance shift matter now
KONE Oyj (HLSE:KNEBV) has just paired a third quarter earnings release with a higher full year sales growth outlook, after reporting gains in quarterly sales, net income and earnings per share.
The latest guidance upgrade comes as KONE Oyj’s share price has gained 8.05% over the past month and 10.38% across 90 days. However, the year-to-date share price return is still down 9.25% and the one-year total shareholder return is slightly negative at 1.58%. Over longer periods, the picture shifts. The 3-year total shareholder return stands at 45.84% and the 5-year total shareholder return at 9.66%, suggesting longer term holders have seen meaningfully better outcomes than those focused on recent weakness.
Scan how KONE Oyj’s guidance shift compares with other industrial peers by reviewing a curated list of list of solid balance sheet and fundamentals (203 results) in similar sectors.
Bulls point to KONE Oyj’s upgraded sales guidance and long term returns. Bears focus on the weaker China new building market. The valuation section now shows which side current pricing leans toward.
Most Popular Narrative: 7% Undervalued
KONE Oyj’s widely followed narrative fair value of €59.70 sits above the latest close at €55.30, which frames the current debate around the stock’s earnings power and balance sheet risk.
The planned combination with TK Elevator, which would create a company with over €20b of pro forma sales, around €2.7b of adjusted EBIT and targeted annual cost and financing synergies of about €900m, has the potential to improve scale efficiency and financing costs and in turn influence future EBIT margins and earnings.
See why 18 investors see KONE Oyj as 7% undervalued.
Result: Fair Value of €59.70 (UNDERVALUED)
Still, that story can change quickly if the Chinese new construction market weakens further or if the TK Elevator deal loads KONE Oyj with higher risk than expected.
Find out about the key risks to this KONE Oyj narrative.
Another View: KONE Oyj looks expensive on earnings
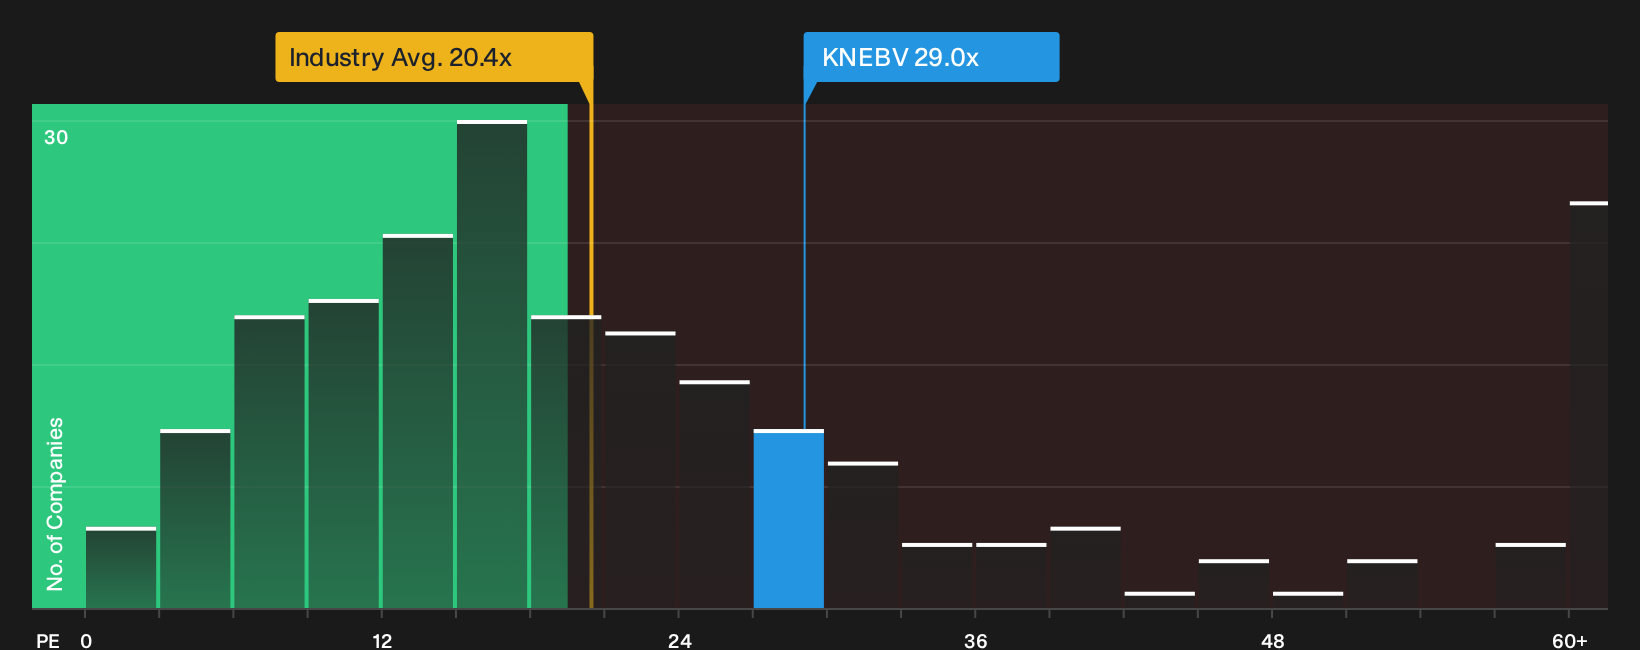
The first narrative points to KONE Oyj trading about 7% below a €59.70 fair value. On a plain P/E basis, the picture is harder to call a bargain. The stock trades on 29x earnings, compared with 20.5x for the European Machinery industry, 18x for peers, and a fair ratio of 28.4x that the market could move toward. That gap raises the question of whether investors are already paying up for much of the modernization and TK Elevator story.
To see how these earnings-based signals stack up against detailed ratio work, review the valuation breakdown in See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on KONE Oyj so far. If you want to move quickly and form your own angle on the situation, start with the balance of 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond KONE Oyj?
If KONE Oyj has sharpened your thinking, do not stop here. Broaden your watchlist with targeted ideas that match what you want from your capital.
- Target dependable income and capital resilience by reviewing a curated set of 221 dividend fortresses that combine yield with staying power.
- Hunt for mispriced quality by scanning the 199 high quality undervalued stocks that pair strong fundamentals with valuations the market has not fully rewarded yet.
- Lower the overall risk in your portfolio by checking a focused group of 218 resilient stocks with low risk scores built on sturdier balance sheets and steadier track records.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com