


EN
Eisai (TSE:4523) In Focus Following Lecanemab Data Update With Valuation In Question
Why Eisai stock is back in focus
Eisai (TSE:4523) is drawing fresh attention after confirming an extensive data rollout on its Alzheimer’s drug lecanemab at the CTAD 2026 conference, including five year outcomes and real world usage analyses.
Investors have already been reacting around the margins, with Eisai’s 1 day share price return of 1.57% and 30 day share price return of 4.06% framing the latest lecanemab update, set against a 12 month total shareholder return of 14.22%, but a 3 year total shareholder return that has declined 31.68%.
Compare Eisai’s Alzheimer’s catalyst with other healthcare-focused opportunities by screening for 10 healthcare AI stocks that could be building momentum off similar treatment and technology breakthroughs.
The recent Eisai move sits between two stories. Some will see early evidence of business traction around lecanemab, while others may view it as a sentiment swing ahead of CTAD. How does that backdrop line up against today’s valuation?
Most Popular Narrative: 10% Overvalued
Eisai last closed at ¥5,052, which sits above the most followed fair value estimate of ¥4,582. As a result, the current Alzheimer’s excitement is being judged against expectations that already build in meaningful neurology and oncology contributions.
The current narrative that Eisai is fairly valued and bullish suggests that the share price already reflects meaningful contributions from LEQEMBI, LENVIMA, DAYVIGO, and the medium-term revenue and core operating profit targets through FY2028.
See why 4 investors see Eisai as 10% overvalued.
Result: Fair Value of ¥4,582 (OVERVALUED)
Still, pressure on LEQEMBI pricing or a sharper increase in biologics-related production costs could quickly challenge Eisai’s recurring earnings narrative around neurology.
Find out about the key risks to this Eisai narrative.
Another View: Eisai Through A Cash Flow Lens
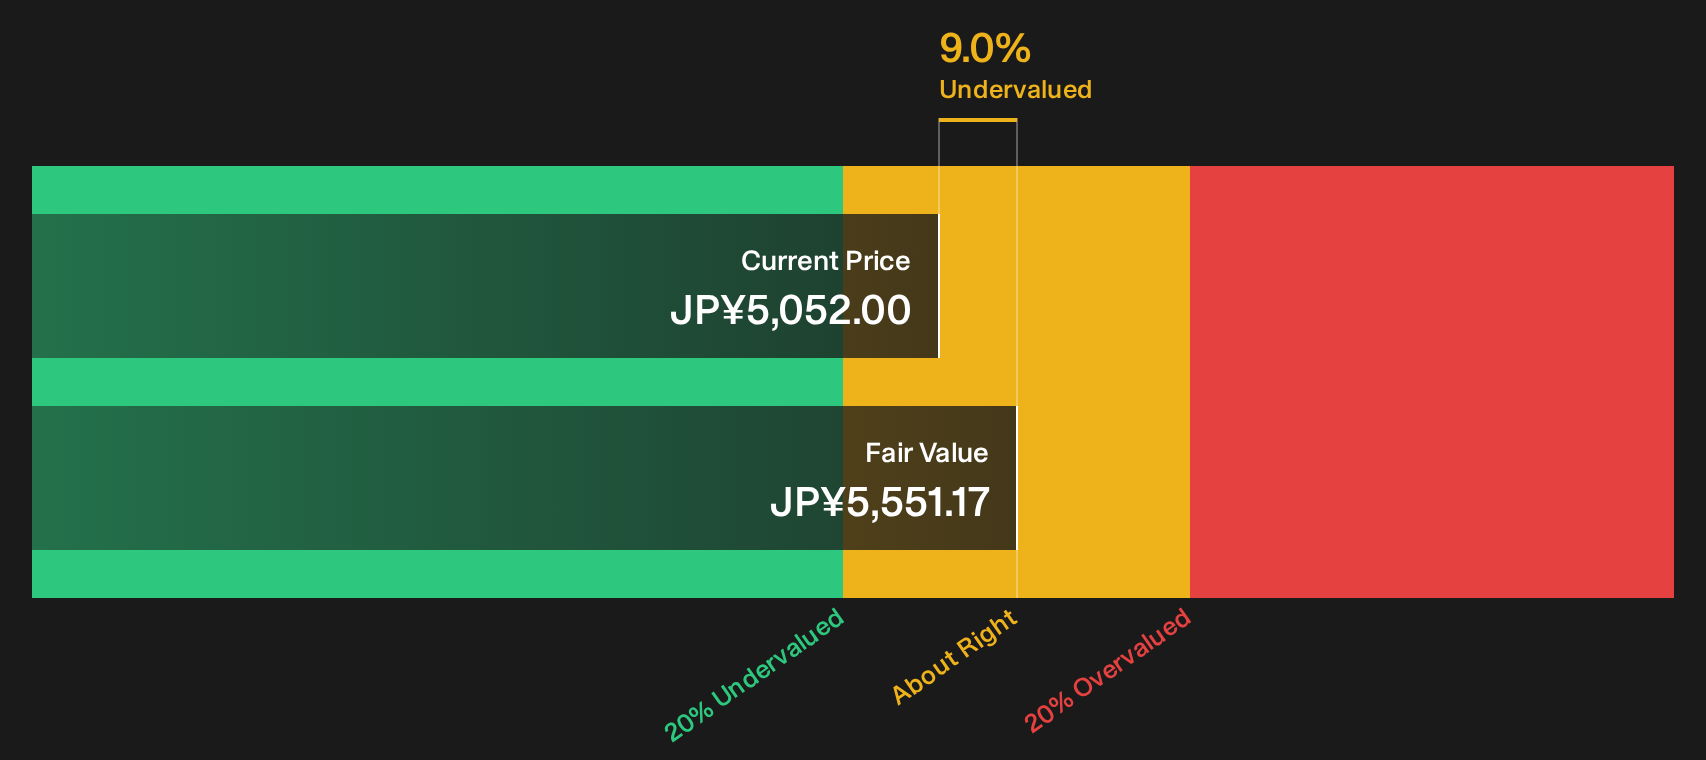
The earlier narrative framed Eisai as roughly 10% above a fair value of ¥4,582 using earnings and analyst targets. A different lens tells a different story. The SWS DCF model estimates Eisai’s future cash flows at ¥5,551.17 per share, which puts today’s ¥5,052 price below that level and points to an undervalued reading instead.
This gap between an earnings based fair value of ¥4,582 and a cash flow estimate of ¥5,551.17 leaves you deciding which set of assumptions feels more realistic for Alzheimer’s uptake, margins and capital spend over the next few years.
To see how this cash flow view is built and what would need to change for it to move, Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Eisai for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 15 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If sentiment across Eisai still feels split to you, quickly review the numbers, pressure test the Alzheimer’s thesis, and weigh both sides of the story yourself with 2 key rewards and 1 important warning sign.
Looking for more ideas beyond Eisai?
If Eisai has sharpened your focus, now is the moment to broaden your watchlist with other clear, numbers based ideas before the next move passes you by.
- Target resilient income by scanning for companies in the 27 dividend fortresses that might support stronger portfolio cash flow.
- Hunt for potential mispriced opportunities using the 15 high quality undervalued stocks that could align better with your return expectations.
- Reinforce portfolio resilience by reviewing the 24 resilient stocks with low risk scores that may help you reduce downside exposure.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com