


EN
Colgate-Palmolive (CL) Could Be Trading At A 26% Discount Following Its Earnings Beat
Colgate-Palmolive (CL) just paired a third quarter earnings beat with higher full year guidance. The company updated investors on net sales, profit margins and expectations for double digit earnings per share growth.
Colgate-Palmolive shares have climbed, with a 1-month share price return of 11.69% and a year-to-date share price gain of 22.65%. The 1-year total shareholder return of 26.64% signals building momentum around the earnings beat and higher guidance.
Scan how Colgate-Palmolive’s earnings beat and raised guidance compare with other consumer stocks showing similar momentum across our hand-picked 29 high quality undervalued stocks right now.
After a sharp rerating on the back of raised guidance, Colgate-Palmolive now sits closer to analyst targets but still screens at a discount to an intrinsic estimate. Does that trade off between recent gains and perceived value still favour buyers?
Most Popular Narrative: 10% Overvalued
On the numbers, the most followed narrative pegs Colgate-Palmolive’s fair value at $86.48 using a 7% discount rate, which sits below the last close of $95.29 and frames the recent rally as slightly ahead of itself rather than wildly mispriced.
The operating business is running ahead of the tape. Second quarter net sales rose 4.9% to $5.36 billion with organic sales up 2.4%, Base Business EPS up 8% to $0.99, and gross margin up 140 basis points to 61.5%. That extended the earnings beat streak to five quarters, with volume growth accelerating for a third consecutive quarter. Free cash flow rose 18% through the first half, and management raised full year gross margin guidance to roughly flat against a prior expectation of decline, while increasing advertising at a double digit rate.
See why 9 investors see Colgate-Palmolive as 10% overvalued.
Result: Fair Value of $86.48 (OVERVALUED)
Still, Colgate-Palmolive’s story can crack if North American organic sales stay weak for longer, or if another skin health impairment signals deeper brand issues.
Find out about the key risks to this Colgate-Palmolive narrative.
Another View: SWS DCF Model Flags Upside
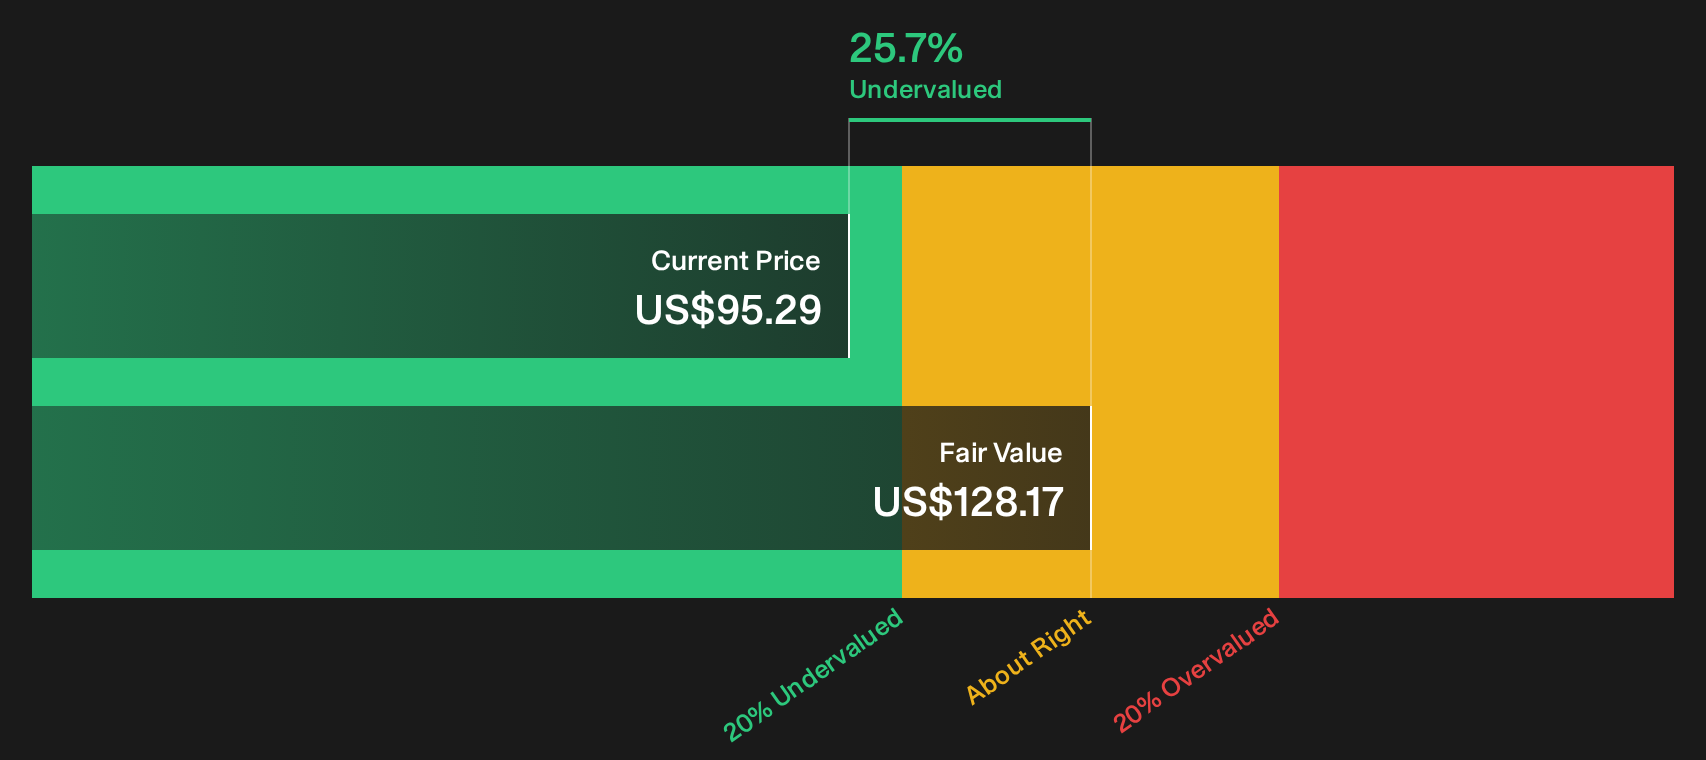
Where the popular Colgate-Palmolive narrative calls the stock roughly 10% overvalued at a fair value of $86.48, the SWS DCF model points the other way. In that framework, an estimate of future cash flow value at $128.17 implies the current $95.29 price sits well below intrinsic value.
The gap is wide. A 25.7% discount on this cash flow lens gives investors a very different read on risk than a forward earnings multiple that looks stretched against fair ratio estimates. The key question is which set of assumptions is more convincing: the conservative growth and margin inputs in the narrative, or the cash flow path built into our DCF model.
To understand the moving parts in that projection, and what would need to change for the two views to converge, Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Colgate-Palmolive for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals in Colgate-Palmolive’s story so far. If you want to move fast and build your own view, start with the 3 key rewards and 3 important warning signs.
Looking for more Colgate-Palmolive sized ideas?
Do not stop with Colgate-Palmolive. Use the screener to hunt for quality, compare stories side by side, and pressure test where your next dollar should go.
- Target resilient income by scanning companies that behave like income anchors through our 5 dividend fortresses.
- Hunt for quality at a discount by filtering for businesses that pair strong fundamentals with appealing prices across the 18 high quality undiscovered gems.
- Protect your downside first by focusing on resilient balance sheets and lower risk profiles using the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com