


EN
Are Slowing Earnings Altering The Investment Case For MSC Industrial Direct Stock?
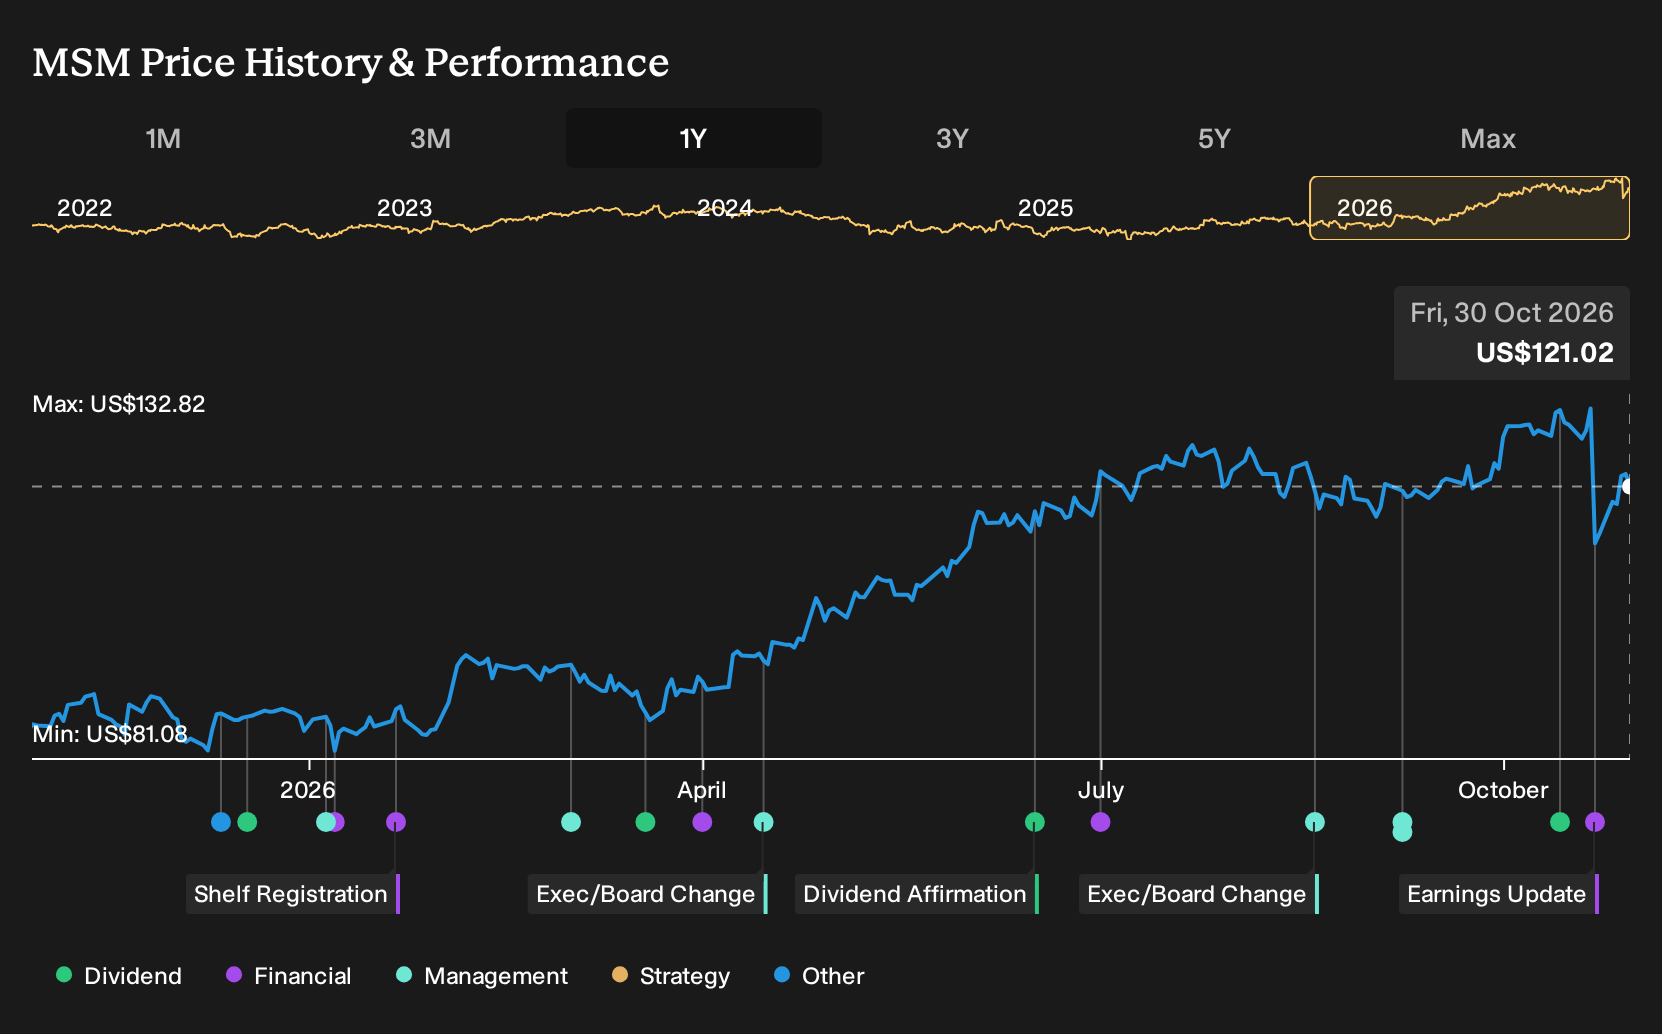
- MSC Industrial Direct reported fourth quarter sales of US$1,079.16 million and net income of US$47.94 million, with basic earnings per share from continuing operations of US$0.86.
- The contrast between higher fourth quarter sales and lower quarterly net income and earnings per share raises questions about cost pressures and profitability trends within MSC Industrial Direct's distribution model.
- We will now look at how MSC Industrial Direct's investment narrative holds up given that quarterly earnings growth trails profit performance.
Stress test MSC Industrial Direct against a curated peer set to see how its mixed earnings picture compares with 29 high quality undervalued stocks that pair resilient cash flows with solid balance sheets.
MSC Industrial Direct Investment Narrative Recap
To own MSC Industrial Direct, you need to believe its distribution platform can convert steady customer demand into healthier profitability over time. The recent quarter showed higher sales but lower quarterly earnings per share, so the key short term catalyst is whether cost programs, automation and sales productivity work can translate revenue into cleaner margins.
The biggest near term risk is that weaker volumes and cost inflation offset that efficiency push. Tariffs on China exposed products, higher interest costs and any disruption from sales force and service changes could keep pressure on net income. This quarter does not remove those concerns.
The full year results are the most relevant backdrop to this latest quarter. MSC Industrial Direct reported full year sales of US$4,009.7 million and net income of US$222.59 million, with basic earnings per share from continuing operations of US$3.99. Those figures give you a clearer view of the earnings base that cost and productivity projects are working from.
That annual performance sits alongside earlier commentary that returns on capital have been under pressure and that earnings per share have been flat over several years. Execution on vending, in plant programs, digital channels and headcount savings therefore still matters a lot for the next phase of progress and for how resilient margins prove if demand softens again.
MSC Industrial Direct's current earnings of US$222.6 million are set against analyst expectations for earnings of US$377.6 million by 2029. This implies an earnings increase of about US$155 million and assumes revenue growth of 6.3% each year to reach around US$4.8b in that forecast period.
Uncover why MSC Industrial Direct's fair value indicates a 12% potential upside to its current price. This suggests a discount that could close quicker than many investors expect.
Exploring Other Perspectives
One more optimistic angle on MSC Industrial Direct focuses on AI and higher value programs as the real needle movers. The most bullish analysts were penciling in revenue of about US$5.0b and earnings of US$449.2 million by 2029, compared with US$4.8b and US$377.6 million in the consensus set. Those projections all predate the latest quarter, so use this earnings update as a chance to test which version of the story you find more convincing.
Explore 2 other MSC Industrial Direct fair value estimates, including one that suggests as much as 12% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your MSC Industrial Direct research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for MSC Industrial Direct. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MSC Industrial Direct's overall financial health at a glance.
Looking for more investment ideas beyond MSC Industrial Direct?
If the mixed picture at MSC Industrial Direct has you thinking about diversification, using a structured screener can help you focus on companies that better match your risk tolerance, income needs and return goals.
- If you want potential growth with a focus on balance sheet strength, start with a 18 high quality undiscovered gems that already clear a basic fundamentals hurdle.
- If capital preservation matters most to you, filter for stability with a 30 resilient stocks with low risk scores and see which businesses keep risk indicators in check.
- If dividend income is a key part of your plan, line up payout heavyweights through a 5 dividend fortresses that couples yield with resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com