


EN
Following Earnings And Guidance, Is Spotify Technology (SPOT) Now Too Expensive?
Third quarter earnings and guidance move Spotify Technology into focus
Spotify Technology (NYSE:SPOT) is back in the spotlight after reporting third quarter 2026 results and issuing fresh guidance that paired higher sales figures with shifting profitability trends across the year.
The 1 day share price return of 6.5% and 30 day gain of 21.8% suggest investors are reacting positively to Spotify Technology's recent earnings update and fourth quarter guidance, even though the 1 year total shareholder return has declined 9.4% after very large 3 year gains of about 3.5x.
See what investors are focusing on after Spotify Technology's earnings jump by running the same playbook across our curated list of 29 high quality undervalued stocks.
Spotify Technology now trades higher on fresh results and guidance, so the puzzle is whether the current price still offers a skewed payoff for new buyers or mostly rewards existing holders. Next comes the valuation check.
Most Popular Narrative: 18% Overvalued
On the most followed view, Spotify Technology screens as expensive, with a fair value of $504.24 sitting below the latest close at $593.44 and framing a market that is already baking in a lot of execution success.
The numbers suggest that the share price already reflects successful execution of Spotify Technology’s 2030 margin and subscriber ambitions, leaving limited room for disappointment on user growth, advertising inflection, or content cost negotiations.
See why 10 investors see Spotify Technology as 18% overvalued.
Result: Fair Value of $504.24 (OVERVALUED)
Still, if Spotify Technology sustains gross margin around the low 30s and AI driven productivity holds up, that could undercut the bearish valuation narrative.
Find out about the key risks to this Spotify Technology narrative.
Another View on Spotify Technology’s valuation
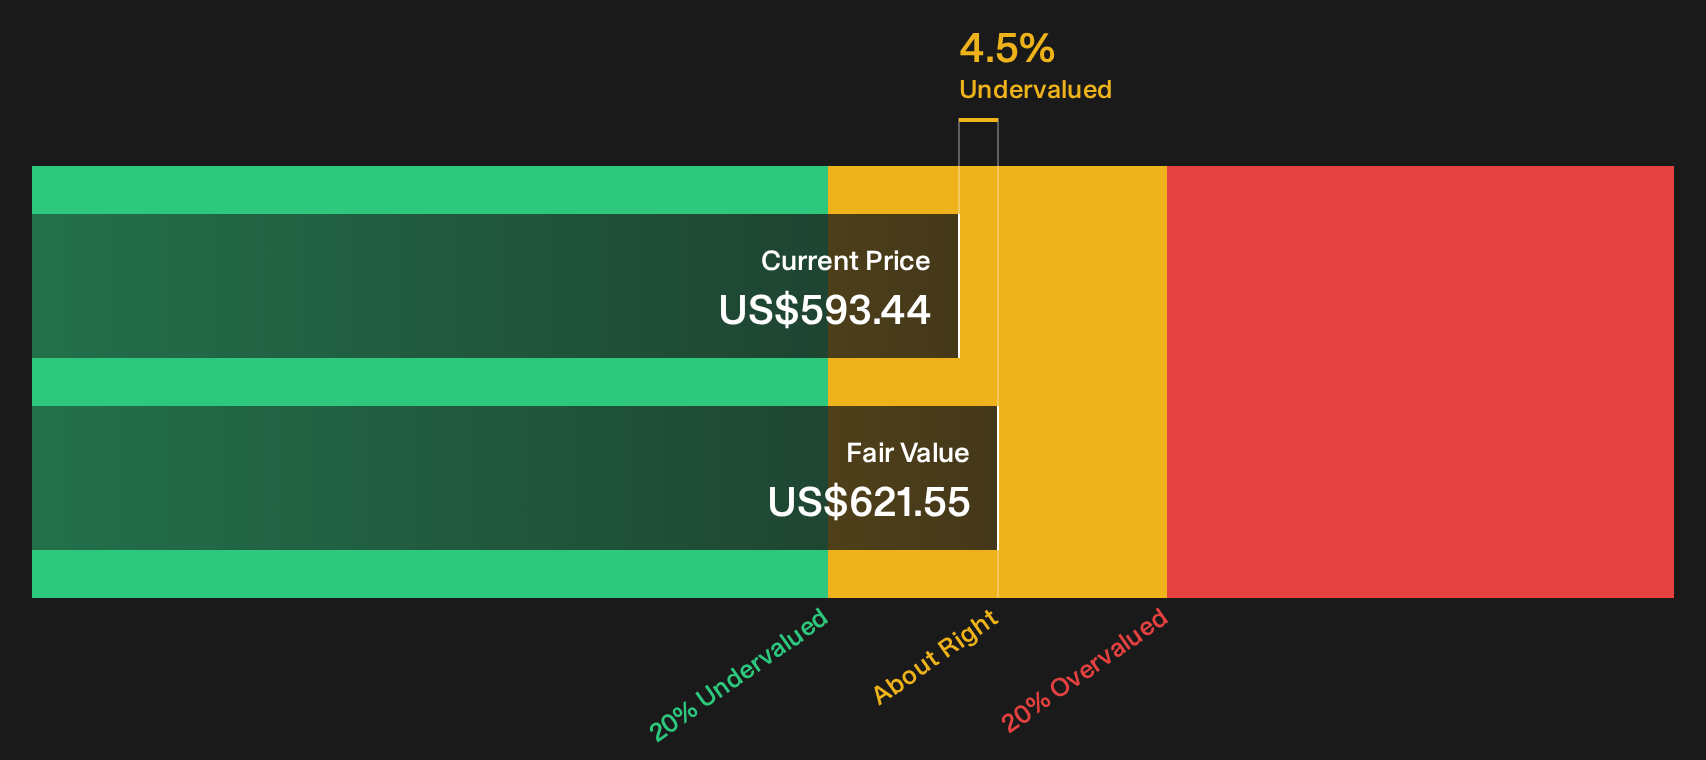
That bearish fair value of $504.24 paints Spotify Technology as 18% overvalued, yet the SWS DCF model points in a different direction. On that cash flow view, SPOT at $593.44 sits about 4.5% below an estimated $621.55 future cash flow value. Which yardstick do you trust more?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages on Spotify Technology's value story often create the best testing ground for your own thesis, so move fast and pressure test the data yourself. To weigh both sides in one place, start with our breakdown of 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Spotify Technology?
If Spotify Technology has your attention, do not stop there. Fresh opportunities often appear first in focused stock lists built from clear, transparent rules.
- Target potential mispricings by scanning a curated set of 29 high quality undervalued stocks that pair stronger fundamentals with prices that still look out of sync.
- Lock in income-focused ideas by reviewing a hand picked group of 5 dividend fortresses that prioritize reliable payouts alongside balance sheet support.
- Protect your downside by filtering for 30 resilient stocks with low risk scores that score well on resilience while still giving you meaningful equity upside.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com