


EN
Is Gibraltar Industries (ROCK) Undervalued Ahead Of Its November 5 Earnings?
Gibraltar Industries (ROCK) is back in focus as traders position ahead of the November 5 earnings release, with Wall Street expecting year-over-year changes in both profit and sales.
Recent trading hints at a tug of war between short term optimism and longer term caution, with Gibraltar Industries’ share price up 3.4% over the past week but down about 20% year to date. The 1 year total shareholder return has fallen roughly 36% as investors weigh earnings expectations against perceived risk.
Scan how traders are positioning around earnings by comparing Gibraltar Industries with a hand picked 29 high quality undervalued stocks that also carry solid fundamentals and potential rerating catalysts.
Bulls point to Gibraltar Industries’ earnings and revenue growth, while bears point to the steep share price decline. Which side does the current valuation actually support as you weigh the next move?
Most Popular Narrative: 47% Undervalued
Against a last close of $40.14, the most followed valuation narrative for Gibraltar Industries points to a fair value of $75.25. This implies a steep discount and a market that remains unconvinced about the long term plan.
The divestiture of the Renewables segment and full exit from eBOS and racking operations is simplifying Gibraltar Industries. This is concentrating management attention and capital on Residential, Agtech, and Infrastructure, which can support a clearer revenue mix and margin profile over time.
OmniMax integration projects have lifted identified synergy opportunities from US$20 million to US$29.4 million in 2026, with logistics, SKU rationalization, and SG&A savings already contributing to a 19% Residential adjusted EBITDA margin in Q2 2026.
See why 6 investors see Gibraltar Industries as 47% undervalued.
Result: Fair Value of $75.25 (UNDERVALUED)
Still, the thesis can weaken if residential roofing demand remains soft for an extended period and Gibraltar Industries struggles to achieve its planned OmniMax synergy and deleveraging targets.
Find out about the key risks to this Gibraltar Industries narrative.
Another View: What P/E Says About Gibraltar Industries
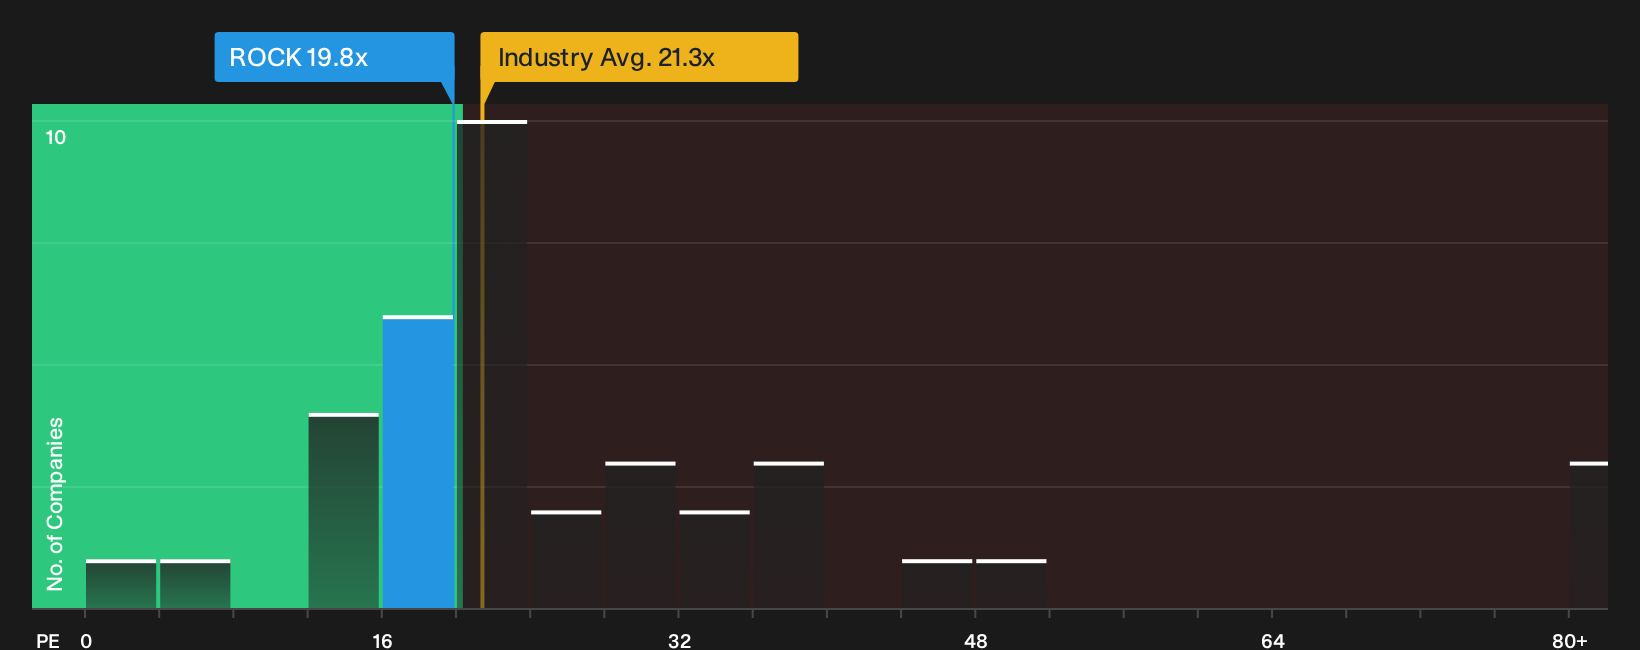
The story shifts when you stop looking at fair value estimates and focus on the P/E ratio. Gibraltar Industries trades on 19.8x earnings, which is richer than its direct peers at 16.8x, yet still below the broader US Building industry on 21.6x.
Our fair ratio estimate sits much higher at 38.4x. This points to a wide gap between where the market prices the stock today and where that multiple could move if sentiment changed. Is that gap a cushion for risk or a signal that expectations might already be demanding?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Gibraltar Industries is clearly split, and the clock is ticking for you to make sense of both the upside and the risk side of the story. Take a few minutes to review the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Gibraltar Industries?
Do not stop at one stock. Broaden your watchlist with fresh ideas built from the same data driven approach, and give yourself more options before the next move.
- Target strong future upside potential by scanning a 18 high quality undiscovered gems that many investors are not watching yet.
- Prioritize resilience first and hunt through a 30 resilient stocks with low risk scores that focuses on companies with more durable profiles.
- Strengthen your core holdings by filtering for a list of solid balance sheet and fundamentals (25 results) that can help you stress test your portfolio.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com