


EN
Did Obesity Drug Data Just Shift Novo Nordisk Stock's Investment Narrative?
- Novo Nordisk recently highlighted extensive new obesity and diabetes data, including 26 abstracts for ObesityWeek 2026 and detailed CagriSema and Wegovy real world findings, alongside FDA approval of once weekly Awiqli insulin for youths with type 2 diabetes.
- The cluster of obesity and diabetes announcements underlines Novo Nordisk's push to defend its GLP 1 position as Eli Lilly's retatrutide raises competitive pressure in core treatment categories.
- This sets the stage for assessing how Novo Nordisk's investment narrative could evolve as GLP 1 competition tightens and CagriSema data becomes available.
Novo Nordisk Investment Narrative Recap
An investor in Novo Nordisk needs to believe the obesity and diabetes franchises can remain the engine of the business while newer therapies gradually add extra legs. In the near term, the story still revolves around scaling Wegovy pill capacity and keeping GLP 1 margins resilient as pricing pressure and the self pay mix weigh on Wegovy injection.
The most important short term catalyst is data and uptake across the oral and combo obesity portfolio, since that supports utilisation of the heavy capacity build out. The biggest risk is that tougher GLP 1 competition and broader payer pressure intensify, which could compress realised prices without enough volume or pipeline contribution to offset it.
The ObesityWeek 2026 data slate may be the most relevant announcement here. A dense set of Wegovy pill, injection and CagriSema readouts gives investors fresh visibility on how Novo Nordisk is executing across age groups, formulations and care settings, including telehealth and digital support programs that can matter for adherence and real world outcomes.
CagriSema REDEFINE results and pediatric semaglutide data feed directly into the firm’s attempt to defend and extend its GLP 1 position against Eli Lilly’s retatrutide. For shareholders watching catalysts, the breadth and quality of these findings help frame whether Novo Nordisk can support its 2030 GLP 1 capacity plans while gradually reducing reliance on any single product.
Novo Nordisk's current analyst narrative points to revenue of DKK 338.9 billion and earnings of DKK 104.7 billion by 2029, compared with earnings today of DKK 116.4 billion. This implies an earnings decline of DKK 11.7 billion over that period, while revenue is described as remaining fairly flat rather than growing at a set annual rate.
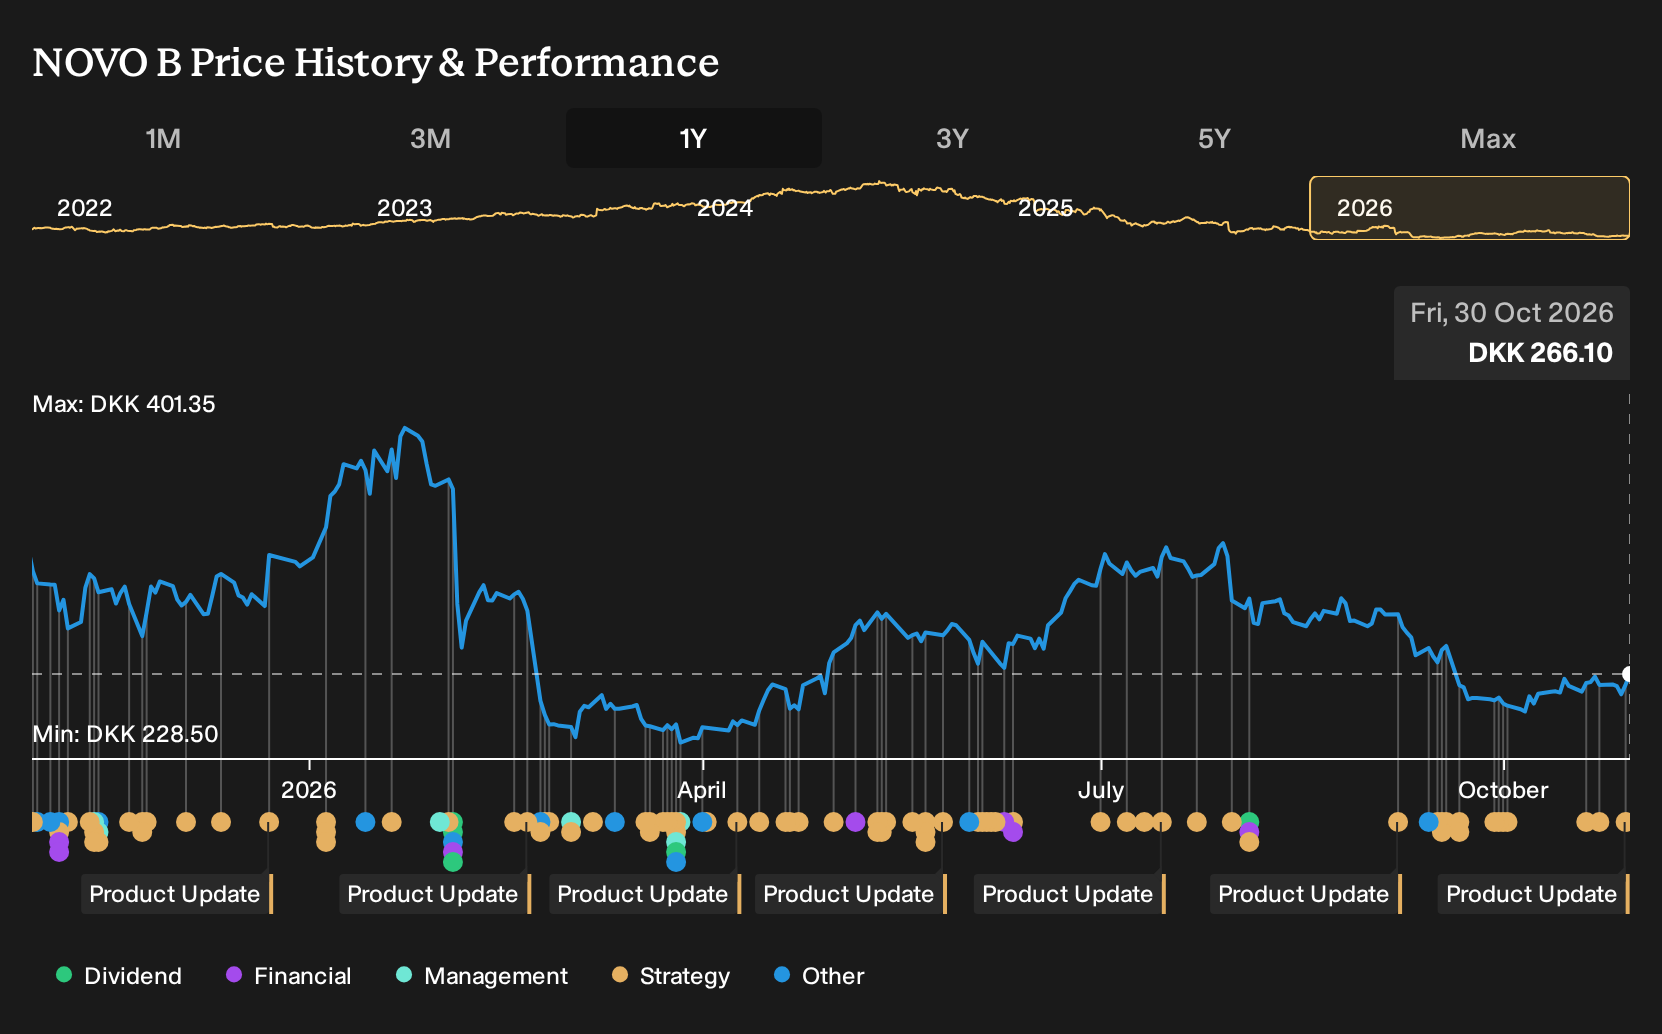
Uncover why Novo Nordisk's fair value indicates a 12% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view focuses on GLP 1 price pressure rather than new obesity data. In that more cautious Novo Nordisk narrative, the lowest analysts previously projected revenue of about DKK 284.0b and earnings near DKK 79.3b by 2029. That is far below consensus. It shows how sharply expectations can differ and why you may want to explore several competing outlooks as ObesityWeek 2026 data and the Awiqli approval potentially reshape forecasts.
Explore 16 other Novo Nordisk fair value estimates, including one that suggests it could be worth just DKK287.00.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Novo Nordisk research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Novo Nordisk. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Novo Nordisk's overall financial health at a glance.
Looking for more Novo Nordisk style investment ideas?
If Novo Nordisk has sharpened your focus on quality and durability, broaden that lens by using the Simply Wall St Screener to surface other businesses with characteristics that match your own risk and return preferences.
- If capital protection sits high on your list, start with companies that score well on resilience and risk using the 218 resilient stocks with low risk scores.
- For investors who care most about financial strength and staying power, the list of solid balance sheet and fundamentals (203 results) can point you toward businesses with sturdier balance sheets.
- If you are hunting for under-followed opportunities with stronger fundamentals than their visibility suggests, the 603 high quality undiscovered gems is a useful way to surface fresh ideas.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com