


EN
Ryanair (ISE:RYA) Stock Looks Reasonably Priced On 20% Airfare Warning
Ryanair Holdings has delivered a 59.6% gain over the past three years, yet its recent share price pullback and shifting industry backdrop now put a simple question in front of you. Is the current price you see on the screen adequately grounded in the airline's earnings power.
- A 59.6% return over three years puts real weight on whether Ryanair's profit engine has changed enough to support where the stock now trades.
- The CEO's expectation of sharply higher European airfares, along with route cuts and fuel cost pressures, can reshape how investors think about Ryanair's future margins and earnings resilience.
- Your read on Ryanair Holdings is one view; the desks covering it have another. See what analysts think Ryanair Holdings's shares could be worth.
The issue now is whether today's Ryanair share price is justified by the earnings the business is generating and is expected to generate.
If you want more context for Ryanair Holdings and this airfare story, compare it with other listed carriers and transport groups using the solid balance sheet and fundamentals stocks screener (203 results).
Does Ryanair Holdings Look Fairly Valued on Earnings?
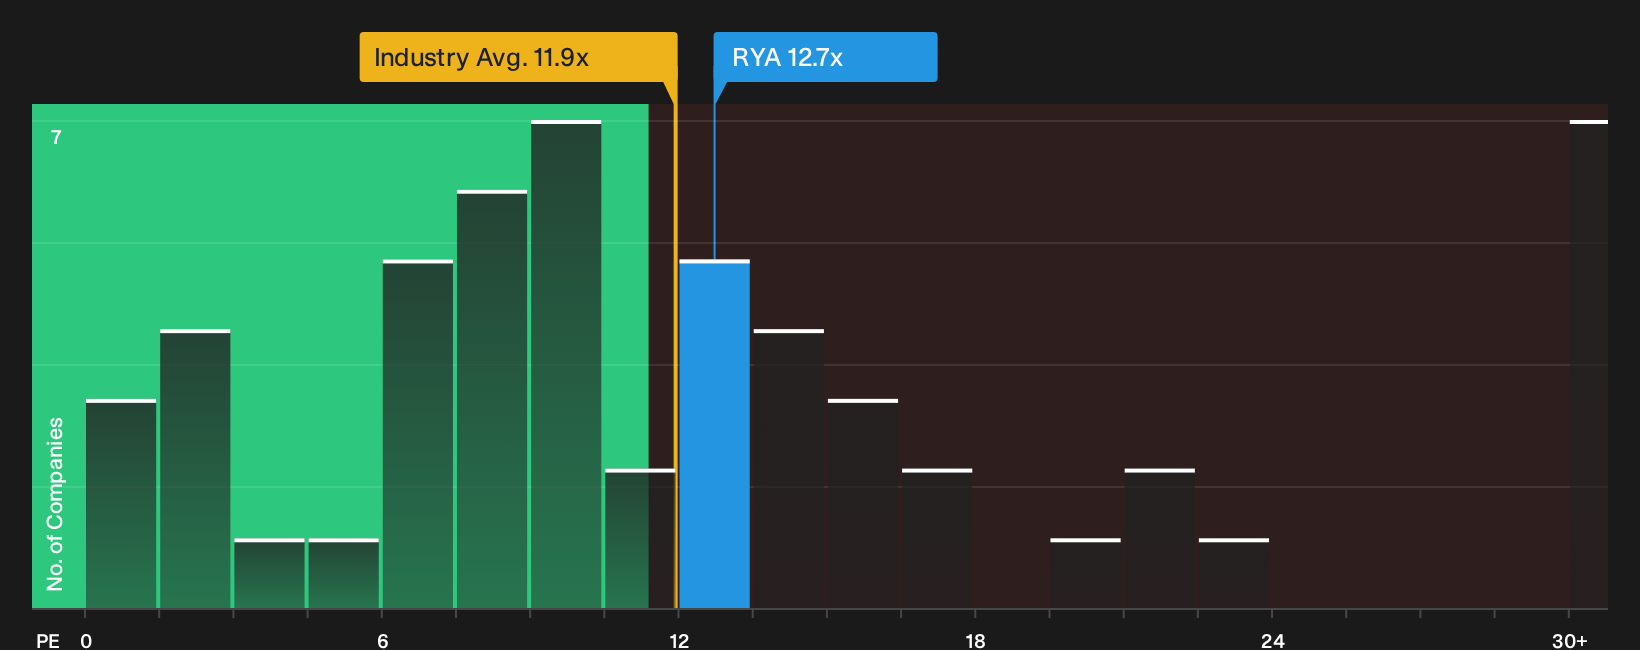
The P/E ratio works well for Ryanair Holdings because earnings are a key focus for airlines with established route networks and large fixed costs. On this lens, Ryanair trades on about 12.7x earnings compared with an industry average of roughly 11.9x and a peer group closer to 13.5x. That places the shares fractionally above the wider airline sector but a touch below similar listed carriers.
Because Ryanair's CEO is flagging a possible 20% jump in European airfares, the current 12.7x P/E suggests the market is pricing in some earnings strength but not giving the stock a big premium to the group. For you as an investor, that kind of mid range multiple means the share price already reflects a fair amount of the story on costs, taxes and capacity cuts, yet it does not fully detach from the sector benchmarks. Explore the numbers behind Ryanair Holdings's P/E valuation.
The Ryanair Holdings Narrative: What Would Justify Today's Price?
Ryanair Holdings' valuation puzzle only really comes into focus once the assumptions behind it are spelled out. This is what Simply Wall St Narratives aim to do by mapping the earnings, margin and growth paths that would need to hold for the stock to be worth materially more or less than today's price on the screen. Each narrative treats fair value as a hypothesis about the business that can be revisited over time rather than a fixed snapshot.
One of the top community narratives on Ryanair Holdings: 20% undervalued
"Fuel and currency hedging out to FY 2027 at materially better rates, alongside a transition to a debt free balance sheet with over 600 unencumbered aircraft..."
Discover why this Narrative puts Ryanair Holdings at 20% undervalued.
For Ryanair Holdings, the quoted price is only one piece of the decision
Before you stop at the P/E and airfares story, look at who is actually steering Ryanair Holdings and how their rewards line up with your interests. See who runs Ryanair Holdings and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com