


EN
Shake Shack (SHAK), Why Is The Market Taking A Closer Look?
Shake Shack (SHAK) heads into its November 5 earnings release with an unusual setup. Wall Street expects an 8.3% year over year earnings decline, even as revenue projections point to 15.8% growth.
Recent trading has been choppy for Shake Shack, with the share price gaining 20.11% over the past 30 days and 12.32% over 90 days, yet still sitting below earlier levels given a year to date share price decline of 15.56% and a 1 year total shareholder return decline of 26.97%. This pattern hints that investors have recently become more willing to price in potential growth or reduced risk ahead of the November 5 update, even though longer term total shareholder returns over 5 years remain down 22.52%. The stock now trades at US$70.48.
Scan how Shake Shack’s setup compares with other consumer names showing earnings pressure but solid top-line momentum by reviewing our hand picked 29 high quality undervalued stocks.
The recent rebound in Shake Shack looks sharp on the chart, yet earnings expectations are softer even as sales forecasts point higher. How much of this move reflects the business, and how much reflects changing sentiment around the valuation setup?
Most Popular Narrative: 13% Undervalued
At a last close of $70.48 versus a widely followed fair value of $81.38, the current setup for Shake Shack hinges on whether margin work and digital traction can keep earning that gap.
Operational tools such as updated labor models, kitchen design changes and supply chain repricing already supported a 120 basis point restaurant margin increase in 2025 despite higher beef costs, and continued work on these programs paired with an explicit aim for G&A leverage from 2027 can provide a path to higher restaurant level profit and company wide earnings.
See why 15 investors see Shake Shack as 13% undervalued.
Result: Fair Value of $81.38 (UNDERVALUED)
Still, the bullish Shake Shack script could be knocked off course if beef and operating costs keep squeezing restaurant margins, or if heavier value competition drags on traffic and earnings.
Find out about the key risks to this Shake Shack narrative.
Another View: Shake Shack Looks Expensive On Earnings
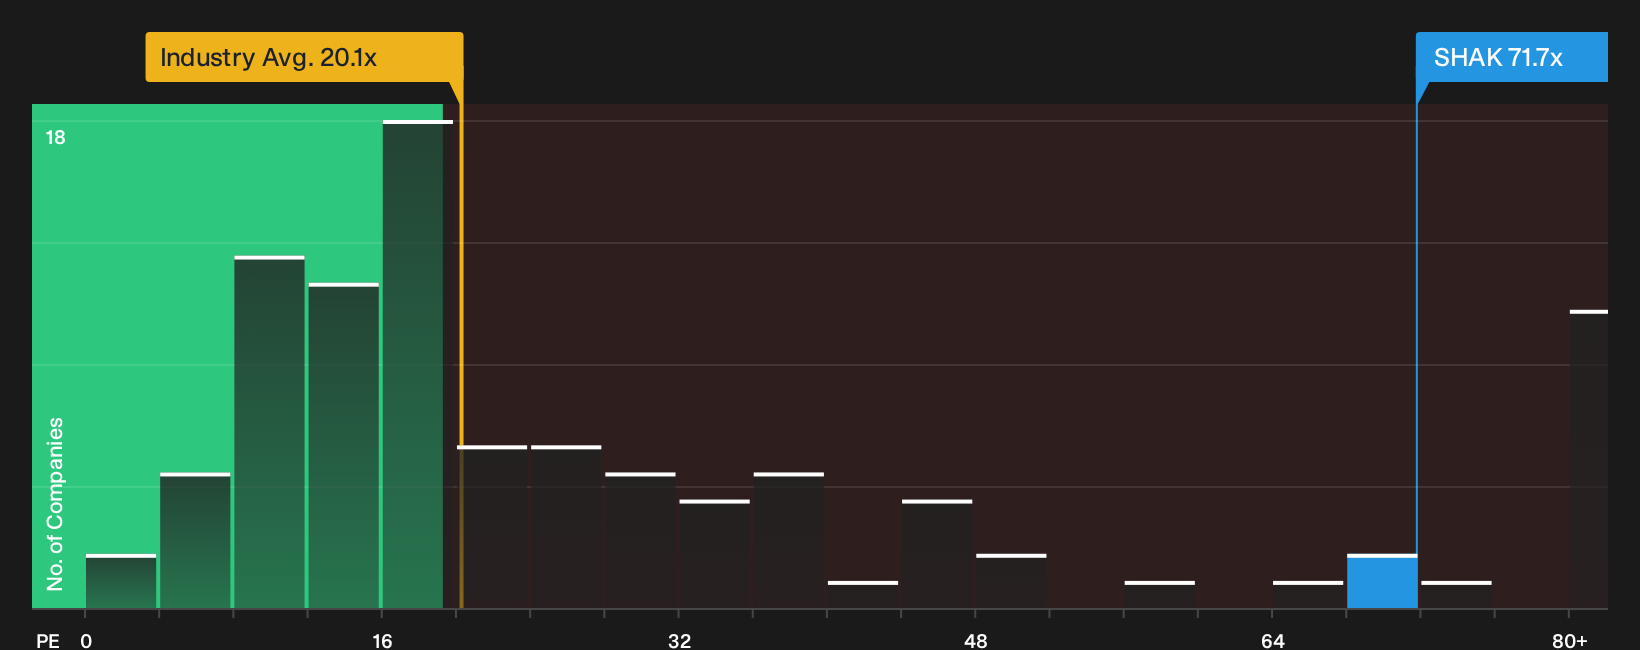
While the fair value narrative pins Shake Shack at US$81.38, the current P/E of 71.7x tells a tougher story. That multiple is far above the US Hospitality industry at 20.7x, the peer average at 19.9x, and even the 22.6x fair ratio estimate. For anyone watching valuation risk, the question is whether future execution really justifies that kind of premium.
See what the numbers say about this price in our valuation breakdown through See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether the mixed tone around Shake Shack really fits your own read of the fundamentals and valuation setup? Act quickly, examine the positives in detail, and weigh the trade offs yourself by reviewing the 3 key rewards.
Looking for more investment ideas beyond Shake Shack?
If Shake Shack has sharpened your focus on valuation and risk, do not stop here. Broaden your watchlist now so you do not miss stronger setups.
- Target steadier compounding by reviewing a curated pool of resilient companies in the 30 resilient stocks with low risk scores.
- Hunt for quality at a discount by scanning the 29 high quality undervalued stocks that combine solid fundamentals with appealing pricing.
- Spot potential future leaders early by checking a focused 18 high quality undiscovered gems before the broader market pays attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com