


EN
Rambus (RMBS) After Strong Q3 Results And Guidance With Fair Value Still In Focus
Rambus (RMBS) has landed back on investor radars after reporting third quarter 2026 results and fresh fourth quarter guidance, pairing higher revenue and earnings with a clearer near term outlook.
Over the past month, Rambus shares have come under pressure, with the 30 day share price return down 20.71% and the year to date share price return down 14.74%. This is in contrast to the 3 year total shareholder return of 45.76% and 5 year total shareholder return of 252.69%, which point to much stronger longer term momentum.
Scan Rambus alongside other chip and AI infrastructure plays by reviewing the hand picked 54 AI infrastructure stocks that are drawing increased attention after earnings and guidance updates.
Rambus now sits at an awkward crossroads, with bulls pointing to rising earnings and AI exposure while bears focus on the recent pullback and past gains. Which story does the current valuation actually support?
Most Popular Narrative: 40% Undervalued
Against a last close of $84.65, the most followed Rambus fair value narrative sits at about $141.57, which points to a wide valuation gap that hinges on how durable AI driven demand and margin assumptions prove to be under an 11.22% discount rate.
The company's sharpened focus on a core IP licensing and semiconductor business model is being reinforced by silicon IP growth expectations of 10% to 15% annually and record cash from operations of US$360 million in 2025. This supports a revenue mix that can help sustain net margins and fund further product and IP development.
See why 37 investors see Rambus as 40% undervalued.
Result: Fair Value of $141.57 (UNDERVALUED)
Still, Rambus investors need to weigh the antitrust subpoena risk and ongoing supply constraints, which could pressure margins and stall the bullish AI narrative.
Find out about the key risks to this Rambus narrative.
Another View: Rambus On Earnings Multiples
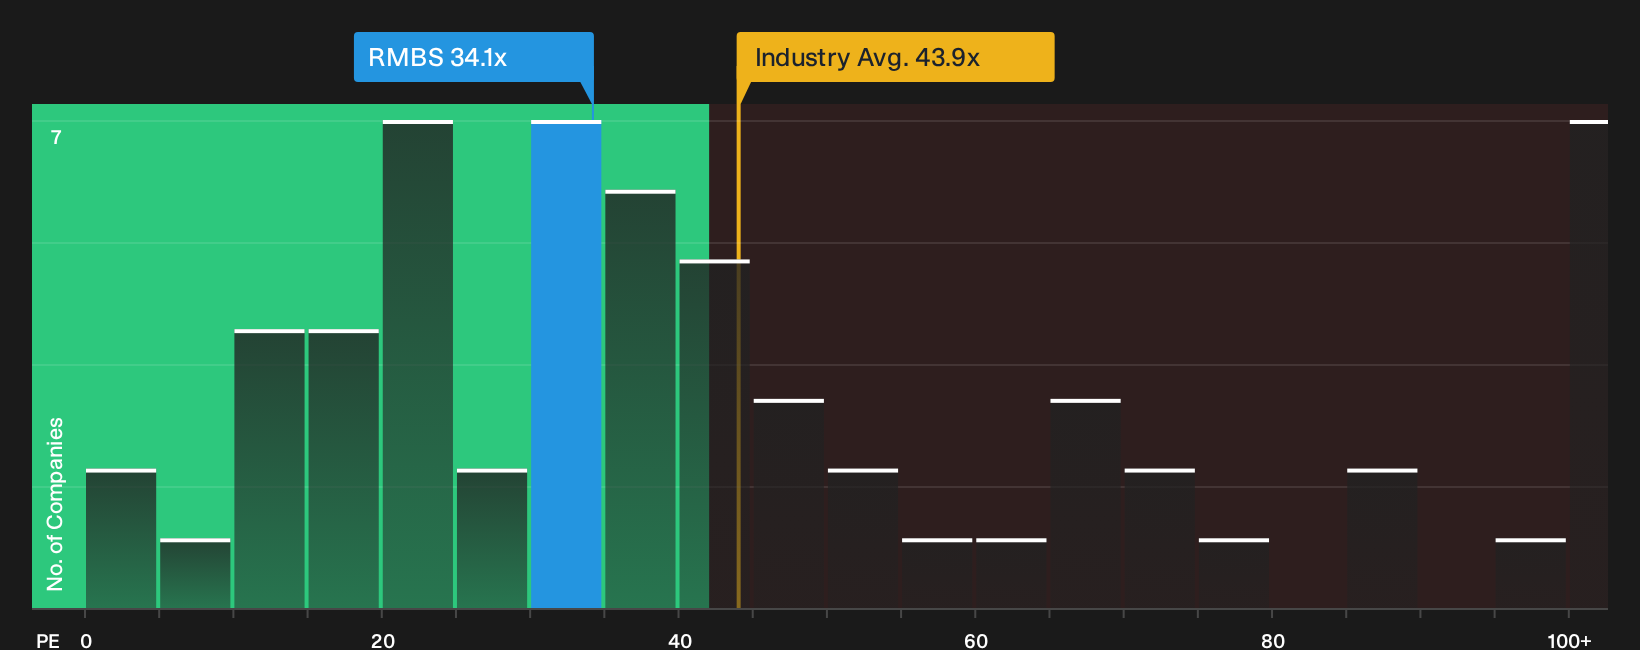
That 40% undervalued story runs into a very different signal when you look at Rambus through its current P/E. At 34.1x earnings, the stock trades well below both the US Semiconductor industry on 43.9x and peers at 46x, and only slightly under a fair ratio of 36.1x.
This gap suggests the share price already builds in some caution, even while leaving room for the market to move closer to that fair ratio if sentiment improves. The key question for investors is whether this discount reflects real risk or an opportunity that patience might reward.
See what the numbers say about this price in our valuation breakdown, then compare it with the See what the numbers say about this price — find out in our valuation breakdown..
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Rambus for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Torn between the bullish AI story and the recent pullback in Rambus, or already leaning one way? Move fast and interrogate the evidence yourself using the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Rambus?
If Rambus has you thinking harder about risk, reward and timing, do not stop at a single ticker. Let a broader watchlist sharpen your decisions.
- Target reliable cash generators by scanning a list of solid balance sheet and fundamentals (25 results) that keeps financial resilience front and centre.
- Hunt for mispriced potential with a curated 29 high quality undervalued stocks that pairs strong fundamentals with attractive entry points.
- Prioritise staying power by reviewing a 30 resilient stocks with low risk scores focused on businesses with more stable profiles when conditions turn choppy.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com