


EN
Adobe Shares Slid Even Though Profit Rose
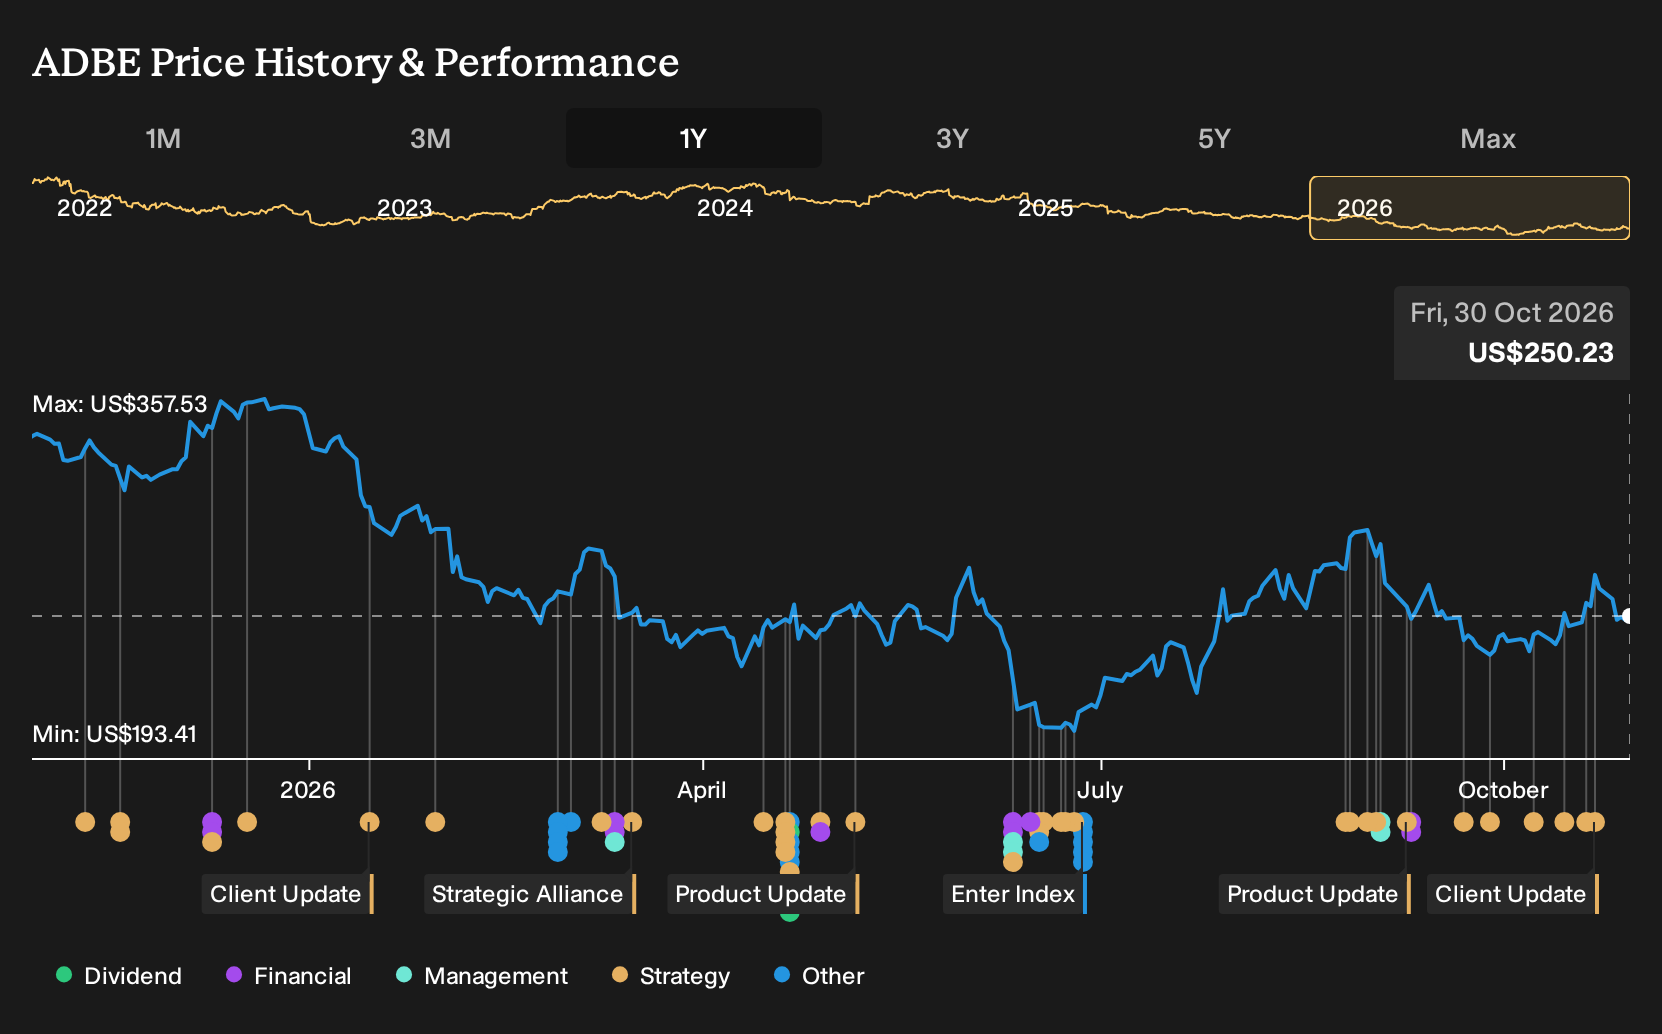
Adobe has spent the past year in the spotlight for CEO and CFO departures, fresh AI rivals and a huge new buyback plan, while also posting record quarterly revenue and crossing 1 billion monthly users. For Adobe shareholders, the loss over the past year was 26.5%, including dividends. If you had bought in on 30 October 2025, how much of that setback would fairly sit with Firefly, GenStudio and the freemium AI pivot now underway?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
Adobe is not the only name tied to this theme. Zero in on 37 AI small caps and compare how each one is priced.
The Two Adobe Stories Investors Had To Balance
The shares cost US$339 at the start of the period, and anyone looking at Adobe then had to choose which future felt more realistic.
On the optimistic side, the Firefly and GenStudio Narrative put Fair Value at US$456, 34% above the start price. That view leaned on assumptions such as revenue growth of 8.8% a year and profit margins at 29.2%, with AI tools including Acrobat AI Assistant and Express helping to lift user engagement.
The cautious Narrative set Fair Value at US$317, 6% below the start price. It assumed revenue growth of 9.0% but profit margins at 26.5%, with competition from browser based startups and AI driven design compressing pricing power.
What The Results Changed For The Adobe AI Story
Adobe’s Q3 2026 numbers showed revenue at US$6.76b versus US$5.99b a year earlier and net income slightly higher, which backed the idea that Firefly, GenStudio and AI assistants could support growth. The drop in net margin from 29.6% to 27.0%, plus freemium AI pressure and fiercer competition, pushed in the cautious direction. Overall, the evidence cut both ways.
The lesson is to track the exact margin assumption that underpins any upbeat AI story. When you see a thesis built on stable or rising profitability, check later filings to see whether net margin, not just revenue, is holding the line.
What You Would Be Paying For In Adobe Today
Adobe now trades at US$250, with this bullish narrative putting fair value above that quote. The core claim is that markets focus on cheap casual content, while Adobe’s grip on professional workflows and enterprise compliance matters more.
For the fall to hint at opportunity rather than warning, a buyer would need to believe enterprise clients keep valuing that integrated, commercially safe AI stack over cheaper standalone tools.
"To understand the future trajectory of Adobe, one must distinguish between the "casual generation" of digital content and the "professional production" of brand-compliant assets. While the former is indeed being commoditized, the latter is becoming increasingly complex, requiring the exact vertically integrated framework that Adobe is currently perfecting."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Looking Beyond Adobe’s AI Canvas
Adobe keeps creative content moving. Just beside it, another heavyweight focuses on the plumbing underneath AI projects.
Where Adobe highlights workflows and polished output, this other group zeroes in on raw computing power and data handling.
It designs cloud infrastructure for intense AI training and everyday inference, closely linked with databases and business software.
Customers that rely on several of those layers often channel much more activity through that ecosystem.
If applied AI demand continues spreading inside enterprises, that kind of full stack position could quietly become pivotal.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 198% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com