


EN
Applied Optoelectronics (AAOI) Gains On AI Demand As Investors Ask If The Story Is Priced In
Applied Optoelectronics (AAOI) is in focus after demand for its 400G and 800G optical products tied to AI infrastructure picked up, while the supplier mix shifted further away from China-sourced components.
Applied Optoelectronics’ share price has been volatile, with the stock down 12.8% over the last day and 30.4% over the past month, yet still up 74.4% year to date as investors weigh strong AI related demand against shifting expectations for future risk and reward.
Compare Applied Optoelectronics' AI infrastructure story with other potential breakout plays using our curated list of 54 AI infrastructure stocks.
Applied Optoelectronics has given investors a wild ride this year. The real tension now is whether most of the AI driven upside is already in the rear-view mirror, or if the recent pullback leaves meaningful value still on the table.
Most Popular Narrative: 56% Undervalued
Applied Optoelectronics last closed at $69.05, while the most widely followed narrative pegs fair value at $156. That gap reflects a view that the real driver here is not just current AI demand, but how far the product roadmap and manufacturing buildout can carry future earnings.
Rising demand for AI/ML workloads, video streaming, IoT, and ongoing transition from copper to fiber in networking infrastructure creates sustained industry tailwinds, increasing the total addressable market for AOI's high-speed optical products with further upside as new product cycles (e.g., 1.6T modules) come online, supporting visibility for top-line growth over several years.
See why 77 investors see Applied Optoelectronics as 56% undervalued.
The narrative applies an 8.8% discount rate and arrives at a fair value of $156, which is very different to the current market pricing. That view leans heavily on analyst assumptions for rapid revenue expansion, margin improvement and eventual profitability from a company that is still reporting an annual loss of $57.02 million on $595.97 million in sales.
For you as an investor, the key question is whether those expectations feel realistic given the risks already flagged around customer concentration, heavy capital spending and execution on new technologies such as 1.6T modules. The stock’s low value score of 1, ongoing losses and recent share dilution sit on one side of the ledger, while high forecast revenue and earnings growth sit on the other.
Result: Fair Value of $156 (UNDERVALUED)
Still, the whole Applied Optoelectronics story leans heavily on just two customers and on aggressive capex. This could be a concern if orders or margins disappoint.
Find out about the key risks to this Applied Optoelectronics narrative.
Another View On Applied Optoelectronics’ Valuation
The story looks very different when shifting from analyst fair value to the SWS DCF model. On that basis, Applied Optoelectronics’ current price of $69.05 sits far above an estimated future cash flow value of just $2.09, implying the stock screens as heavily overvalued. Which version of reality do you trust more?
Look into how the SWS DCF model arrives at its fair value.
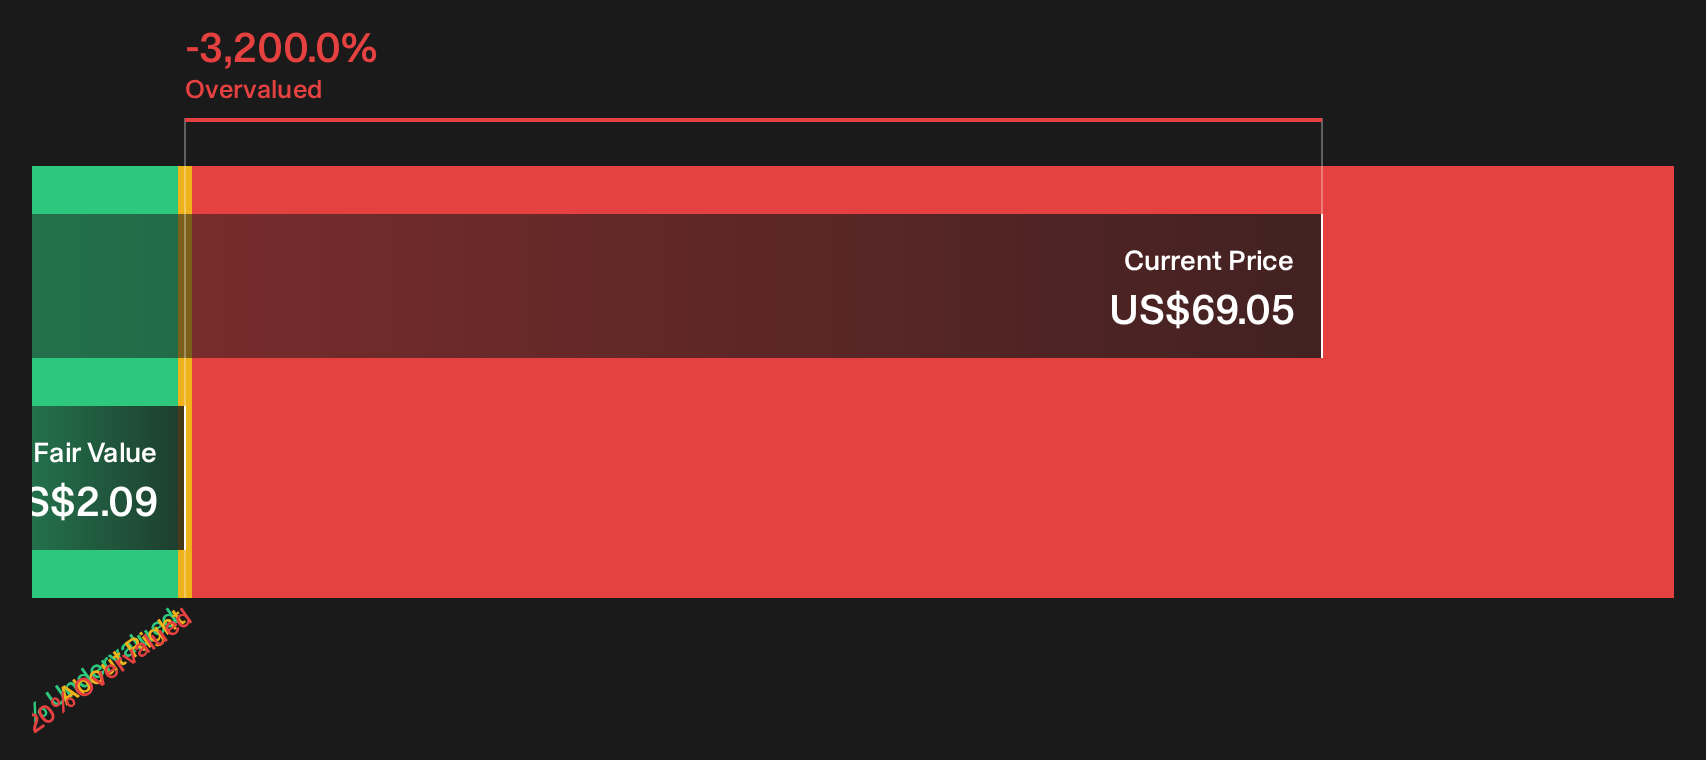
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Applied Optoelectronics for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and concern around Applied Optoelectronics feels familiar, treat it as your cue to move quickly and review the underlying numbers yourself so you can weigh both the potential upside and the red flags on your own terms with 1 key reward and 3 important warning signs
Looking for more investment ideas beyond Applied Optoelectronics?
If Applied Optoelectronics has you thinking harder about AI infrastructure and valuation gaps, you may want to explore other opportunities before this cycle moves on.
- Target rock solid businesses with healthy finances and fewer balance sheet surprises using our list of solid balance sheet and fundamentals (25 results).
- Hunt for strong companies the market may be overlooking by running the 18 high quality undiscovered gems.
- Prioritize stability and lower risk scores when you want potential upside without constant stress by checking the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com