


EN
Novartis (SWX:NOVN) Following Trial Wins And Cosentyx Approval Faces A Full Valuation Debate
Novartis (SWX:NOVN) just packed three major drug updates into one week, ranging from multiple sclerosis and early breast cancer data to a fresh European approval, even as quarterly net income moved sharply lower.
Those trial wins and the new Cosentyx approval have landed against a strong run in the shares, with Novartis posting a 30 day share price return of 11.52% and a year to date share price return of 23.30%. The 1 year total shareholder return of 38.86% and 5 year total shareholder return of 123.15% indicate that this latest earnings wobble comes after a period of robust performance.
Survey other pharma leaders showing similar momentum and clinical depth by scanning the 218 resilient stocks with low risk scores, which is aligned with resilient balance sheets and solid fundamentals.After a 23.30% year to date climb and fresh clinical wins, the question around Novartis now shifts. Is meaningful upside still ahead, or has the bulk of the rerating already played out?
Most Popular Narrative: 34% Overvalued
Novartis currently trades at CHF133.78 against a most-followed fair value estimate of CHF99.90, so the valuation conversation leans heavily on what has to go right in the next few years for that gap to close.
The main thing that has to go right is for the multibillion dollar sales ambitions for remibrutinib, radioligand therapies and the next generation cardiovascular and renal portfolio to offset large loss of exclusivity events and higher ongoing R&D spend.
The current valuation for Novartis implies that the market already prices in sustained execution on 5 to 6% annual sales growth targets, maintenance of about 40% core margins and continued large scale buybacks and dividend increases.
See why 1 investors see Novartis as 34% overvalued.
Result: Fair Value of CHF99.90 (OVERVALUED)
Still, if remibrutinib edges closer to its US$8b ambition or radioligand therapies deliver stronger adoption, the bearish Novartis narrative could unwind quickly.
Find out about the key risks to this Novartis narrative.
Another View On Novartis Valuation
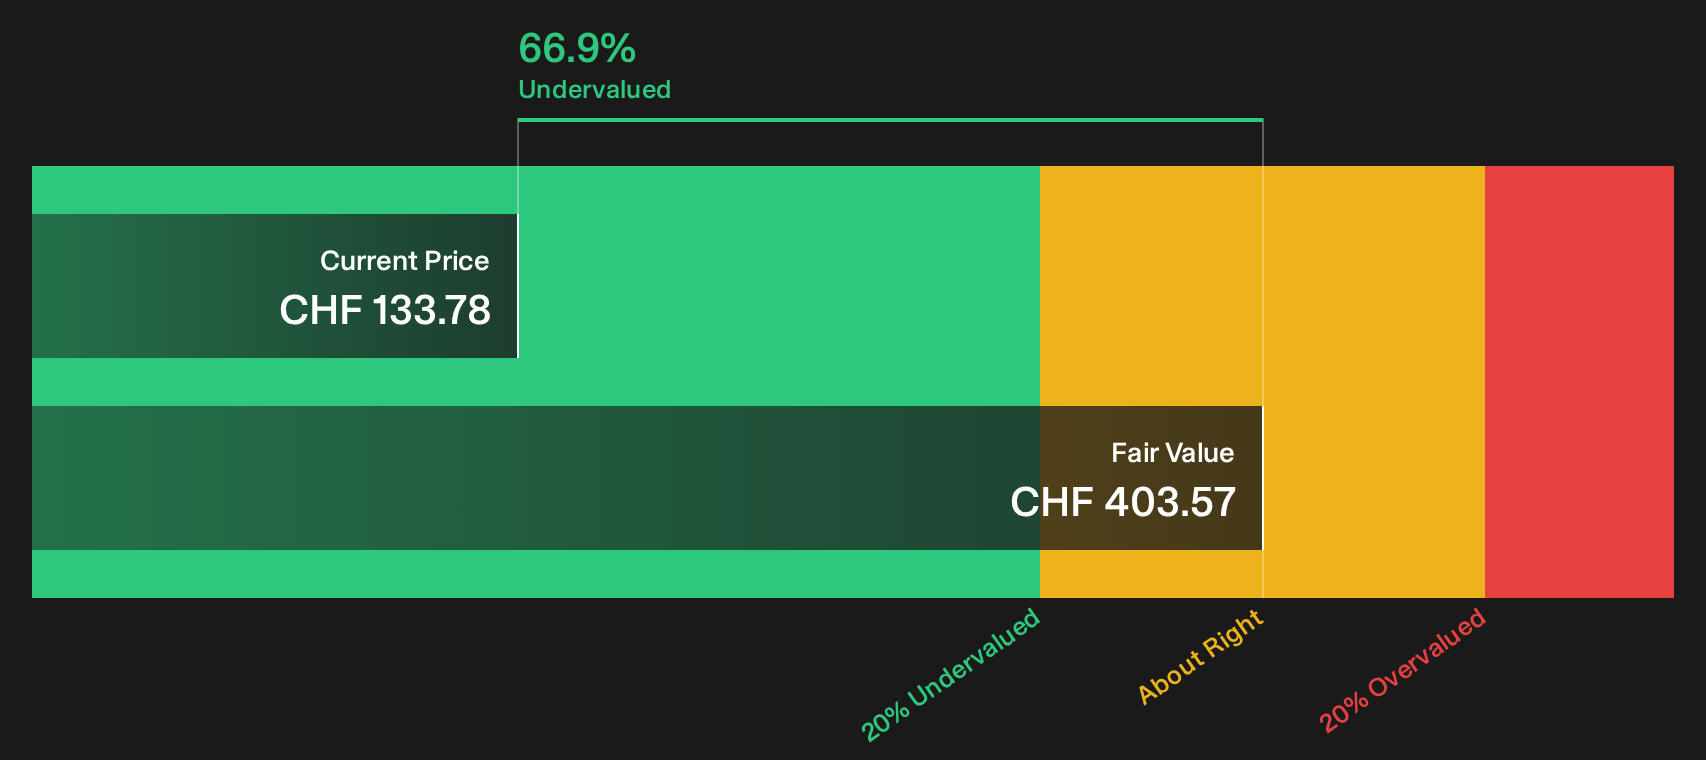
The bearish narrative pins a fair value of CHF99.90 on Novartis, yet the Simply Wall St DCF model points in a very different direction. On that cash flow view, the shares at CHF133.78 trade far below an estimated value of CHF403.57, which implies a very wide gap in expectations. Which lens do you trust more when real money is on the line?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
This mix of optimism and concern around Novartis only matters if it sharpens your own view, so move quickly and stress test the story against the 3 key rewards and 3 important warning signs.
Hunting For More Ideas Beyond Novartis?
If Novartis has sharpened your thinking, do not stop here. Broaden your watchlist with fresh opportunities where fundamentals and price still work in your favor.
- Target dependable income streams by reviewing 221 dividend fortresses that may suit investors who prioritise yield alongside business stability.
- Focus on quality at a reasonable price with 199 high quality undervalued stocks, which filters for strong fundamentals paired with compressed valuations.
- Strengthen your core holdings by scanning list of solid balance sheet and fundamentals (203 results) so you do not miss financially resilient businesses hiding in plain sight.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com