


EN
Monolithic Power Systems (MPWR) Q3 Earnings Challenge Its Premium Valuation
Monolithic Power Systems walked into this Q3 2026 earnings release with a rich reputation and a premium price tag, and the stock barely flinched. The share price moved only 1.1% higher to US$1,211.63, a muted reaction for a semiconductor company that just printed roughly US$1.2b in quarterly revenue and more than US$5.50 in basic earnings per share. Traders treated the update as business as usual. The financials point to a different story, where strong top line momentum and profitability collide with already stretched expectations.
Love Monolithic Power Systems' scale and earnings power but uneasy about paying a premium valuation for "business as usual" results? Check out the 29 high quality undervalued stocks for ideas that pair solid fundamentals with less demanding price tags.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$1,202.4m vs. US$737.2m (up 63.1%)
- Net Income, excl. extra items (Q3 2026 vs. Q3 2025): US$271.1m vs. US$178.3m (up 52.1%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$5.53 vs. US$3.72 (up 48.5%)
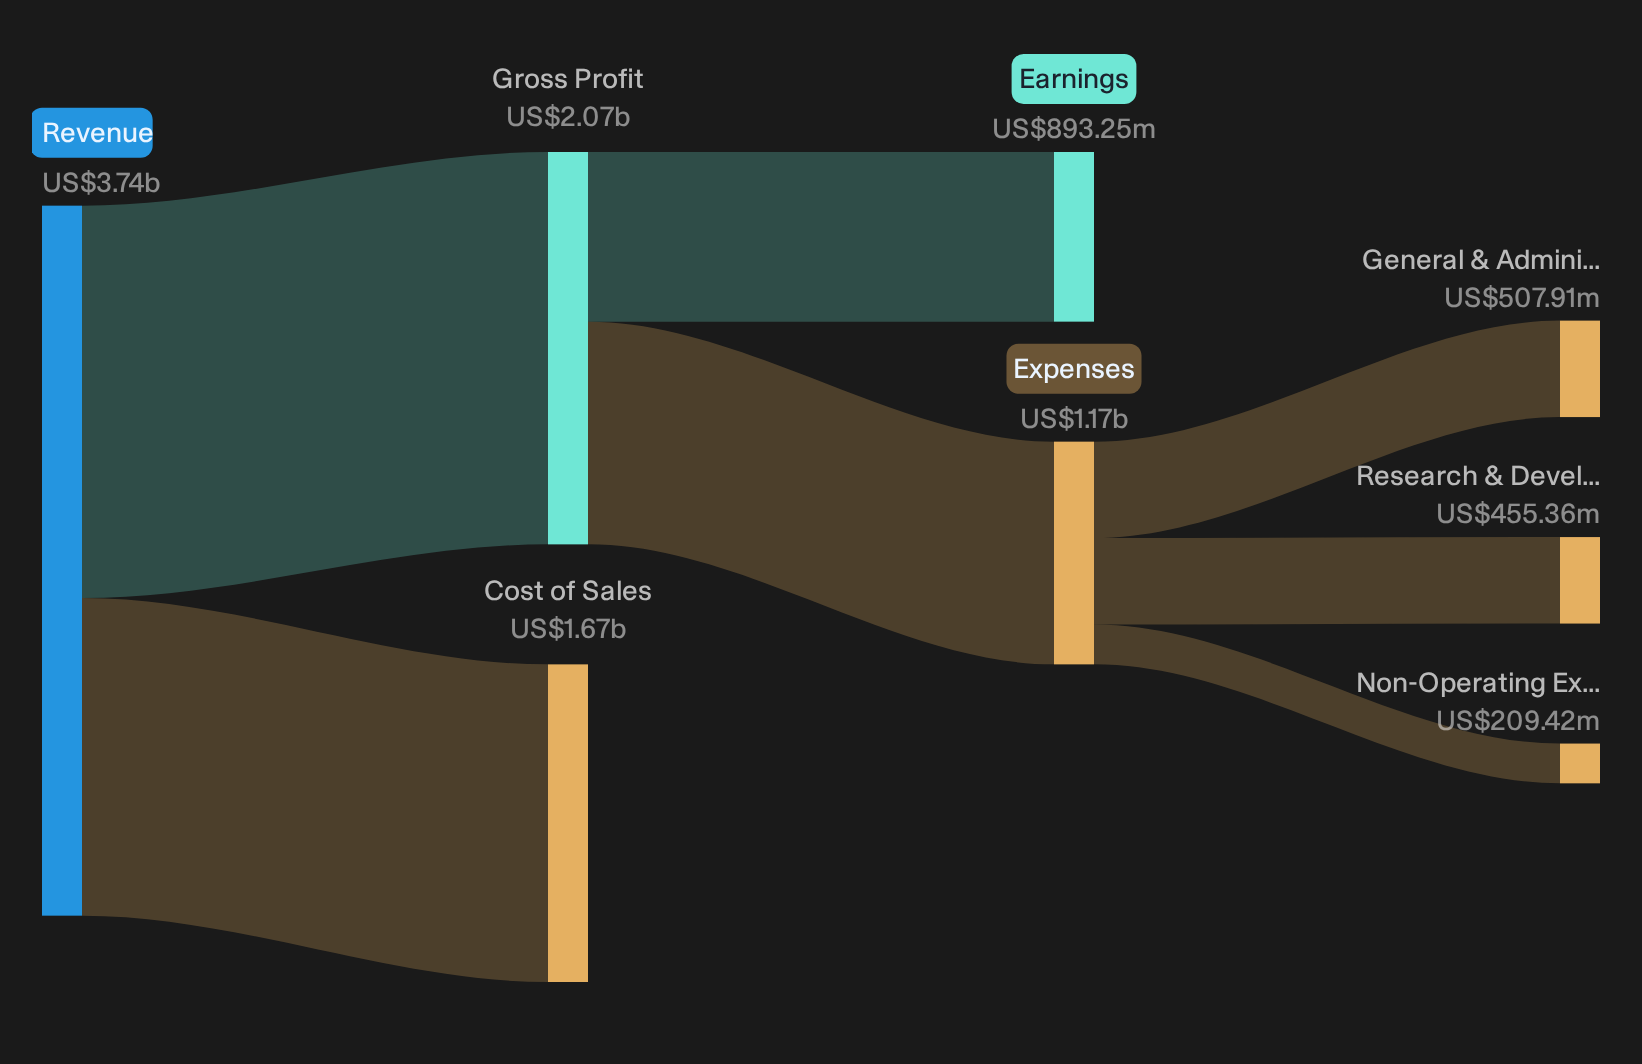
- Trailing 12-month Revenue (Q3 2026 TTM vs. Q3 2025 TTM): US$3,738.4m vs. US$2,661.0m (up 40.5%)
Ask Charlie what raised Monolithic Power Systems' enterprise data growth floor.
Evaluating MPWR’s Capacity And Capital Return Milestones
Monolithic Power Systems bulls argue that the real upside depends on more than near term beats. The thesis leans on a shift in what the business sells and how much output it can support.
"The long term manufacturing partnership with a 300mm fab in Singapore and capacity targets significantly beyond US$6b in annual output give Monolithic Power Systems room to layer more high margin power modules and system level solutions on top of existing AI data center, communications and automotive demand, which can influence both revenue scale and gross margin mix."
Q3 results show this ambition moving from slideware to execution. Revenue cleared US$1.2b, and management now pegs current capacity around US$6b, with a path toward US$8b by H2 2027. The quarter also leaned harder into modules for high current server and GPU sockets, while gross margin again ticked higher within the stated 55% to 60% “sweet spot.” Capital return is no longer theoretical either, with a US$2.00 per share dividend and an expanded US$1b repurchase plan in place.
The price and this Narrative do not agree. → Uncover what this Narrative says Monolithic Power Systems is actually worth.
Monolithic Power Systems: Capacity Risk Still Unresolved
Bears argue that Monolithic Power Systems could overspend on capacity and complex modules and then struggle to fill that pipeline with enough high value output.
"the associated capacity build and complex module assembly spending has already coincided with a weaker free cash flow margin. Any delay in utilization or a mix shift away from these higher powered products could leave cash conversion and earnings below what current revenue expectations imply."
Q3 revenue of US$1,202.4m and a Q4 guide of US$1,320m to US$1,390m show demand currently lining up with the US$6b capacity mark. Yet there is no new disclosure on free cash flow margin or utilization, so the concern about cash conversion and payback on the expanded manufacturing footprint remains largely untested by this quarter’s numbers.
Hunt For Mispriced Execution Stories
Monolithic Power Systems just reported an operational update that aligned with high expectations. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 37% below our estimate - uses AI tools and stricter carrier vetting to reduce higher risk freight and claims exposure.
- Company 2 - 38% below our estimate - expands manufacturing and supply chain capacity so higher margin protective films and services reach OEM and dealer channels.
- Company 3 - 46% below our estimate - converts a large backlog of mega-projects into cash by tightening project management and addressing long running legal disputes.
Those are three of them. See every one of the 29 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com