


EN
Is SEGRO (LSE:SGRO) Still Undervalued As Fresh Rule 8.3 Stakes Emerge?
SEGRO (LSE:SGRO) has come under the spotlight after several institutional investors disclosed fresh positions under Rule 8.3 of the Takeover Code, including holdings via cash-settled derivatives and ordinary shares in late October 2026.
Those fresh Rule 8.3 disclosures land after a mixed stretch for SEGRO, with the share price gaining 28.01% year to date but the 90 day share price return down 5.47%, while the 1 year total shareholder return of 36.47% points to momentum that has been building over a longer window despite recent softness.
Scan how SEGRO fits into the broader real estate opportunity set by comparing it with a curated list of solid balance sheet and fundamentals (10 results).
SEGRO now trades at a modest discount to average analyst targets, even as its share price has already climbed sharply this year. Is that a sign of undue caution, or a reasonable check on enthusiasm?
Most Popular Narrative: 2.9% Undervalued
SEGRO last closed at £9.12, slightly below a widely followed narrative fair value of £9.39, which frames the current analyst discount in a different light.
The physical world is increasingly struggling to bear the exponential weight of the digital world. In our previous analyses, we argued that UK-based Segro (SGRO.LN), with its 190 MVA (Mega Volt Ampere) grid reserve and 1.2 GW of data center development capacity, would transform from a traditional warehouse lessor, the "Powered Shell" model, into a fully fitted energy and data infrastructure player.
See why 14 investors see SEGRO as 3% undervalued.
Result: Fair Value of £9.39 (ABOUT RIGHT)
Still, SEGRO’s data centre narrative depends on capital intensive projects and joint ventures, so delays, cost overruns or tighter funding conditions could quickly dull the appeal.
Find out about the key risks to this SEGRO narrative.
Another View: SEGRO Looks Expensive On Earnings
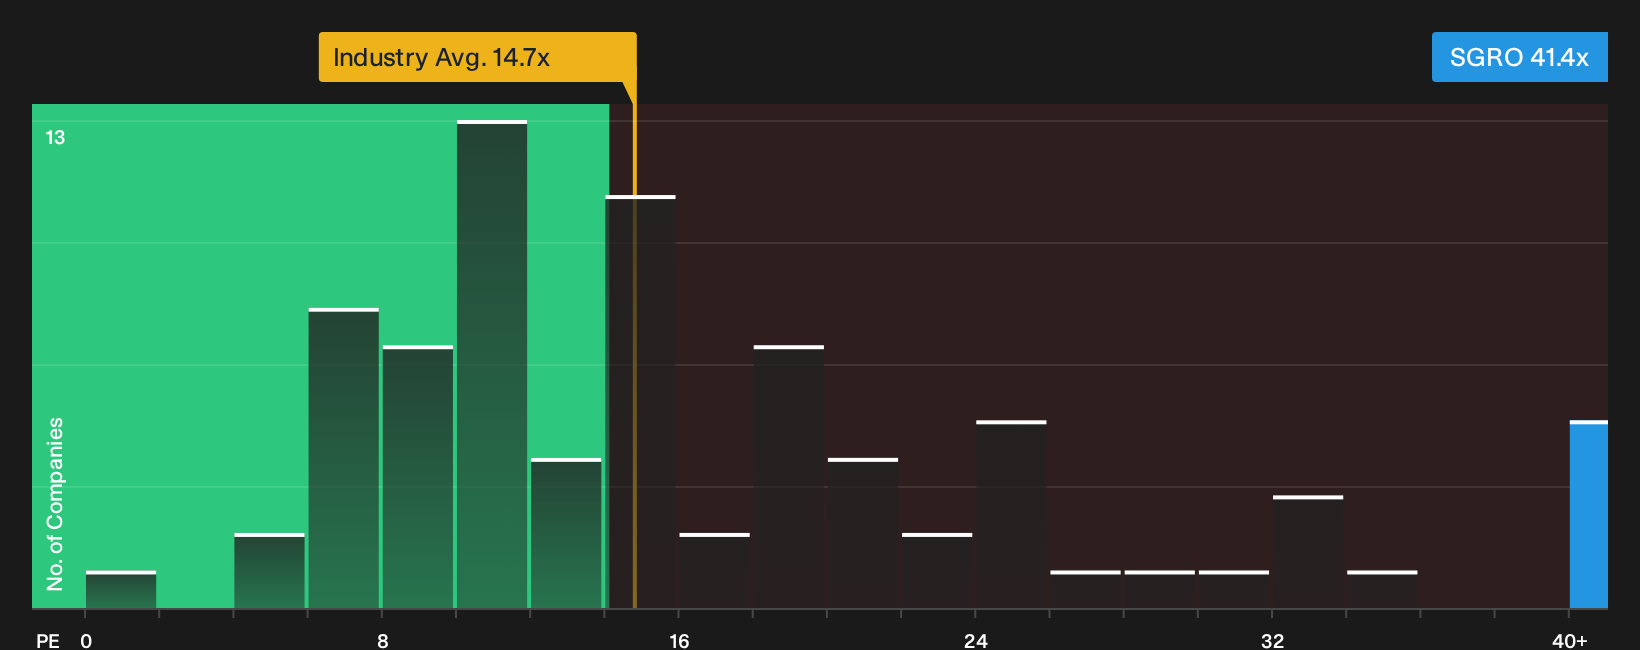
The narrative fair value suggests SEGRO is only 2.9% undervalued around £9.39. On earnings, the picture is harsher. The P/E sits at 41.4x, compared with 14.7x for the global industrial REIT group and 14x for peers, while the fair ratio sits at 18.1x.
Put simply, investors are paying more than double the fair ratio for each pound of earnings, which loads a lot of expectation into the price. If sentiment around SEGRO’s growth or data centre story cools, it is unclear how patient the market will be with that premium.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Opinions on SEGRO are split, with risks and rewards pulling in different directions. Move quickly, review the numbers yourself and weigh up the 2 key rewards and 3 important warning signs.
Looking for more ideas beyond SEGRO?
If SEGRO has sharpened your focus on where capital goes next, do not stop here. The right watchlist often starts with one timely decision.
- Target potential upside in smaller companies that already show financial strength by scanning the 14 elite penny stocks with strong financials before the crowd catches on.
- Pinpoint opportunities where price and quality line up more cleanly by running through the 12 high quality undervalued stocks while sentiment is still uncertain.
- Prioritise staying power and balance sheet resilience by pulling ideas from the 5 resilient stocks with low risk scores so your next move is built on sturdier ground.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com