


EN
Did AI Platform Expansion Just Shift SAP's (XTRA:SAP) Investment Narrative?
- SAP used its October 2026 TechEd conference to roll out new AI capabilities across Joule Studio, Joule Work and the Business AI Platform, as well as tighter governance tools and data integrations with SAP Business Data Cloud, Databricks and Dremio.
- The focus on agent governance, EU AI Act support and data sovereignty indicates that SAP is targeting AI driven automation while maintaining strong control over compliance and customer information.
- We will now look at how these SAP AI platform upgrades and governance tools could influence the company’s longer term investment narrative.
Scan how SAP’s enterprise AI push compares with other potential beneficiaries by running through a curated list of 54 AI infrastructure stocks that could also be wiring themselves into this spending cycle.
SAP Investment Narrative Recap
To own SAP, you need to believe its ERP footprint and cloud shift can keep pulling more workloads, AI agents and data onto its platforms, and that customers are willing to pay for that depth of integration. The recent TechEd announcements support that view by pushing agentic AI and governance deeper into Joule, Business AI Platform and Business Data Cloud.
The more immediate swing factor is how quickly this AI stack converts into higher value cloud contracts without eroding cloud gross margin, which already reflects extra AI and sovereignty costs. That remains the biggest near term risk. Q3 2026 results and raised 2026 guidance point to a still constructive operating backdrop, so the TechEd news looks incremental rather than thesis changing.
Among the recent updates, the 2026 guidance revision ties most directly to the TechEd story. Management now expects 2026 cloud revenue and cloud plus software revenue towards the upper end of prior ranges, and lifted the non IFRS operating profit outlook to €11.8b to €12.2b at constant currencies, while flagging dilution from acquisitions.
For you as a shareholder, that guidance frames the AI platform push as a test of execution. Joule and Business Data Cloud need to sustain cloud and software momentum, while AI units and agent based workflows must carry enough pricing power to outpace the extra infrastructure and test environment spend. Any disappointment here, especially if peers struggle to monetize AI, remains a key risk to both sentiment and SAP’s margin story.
What The AI Push Assumes About SAP’s Earnings Power
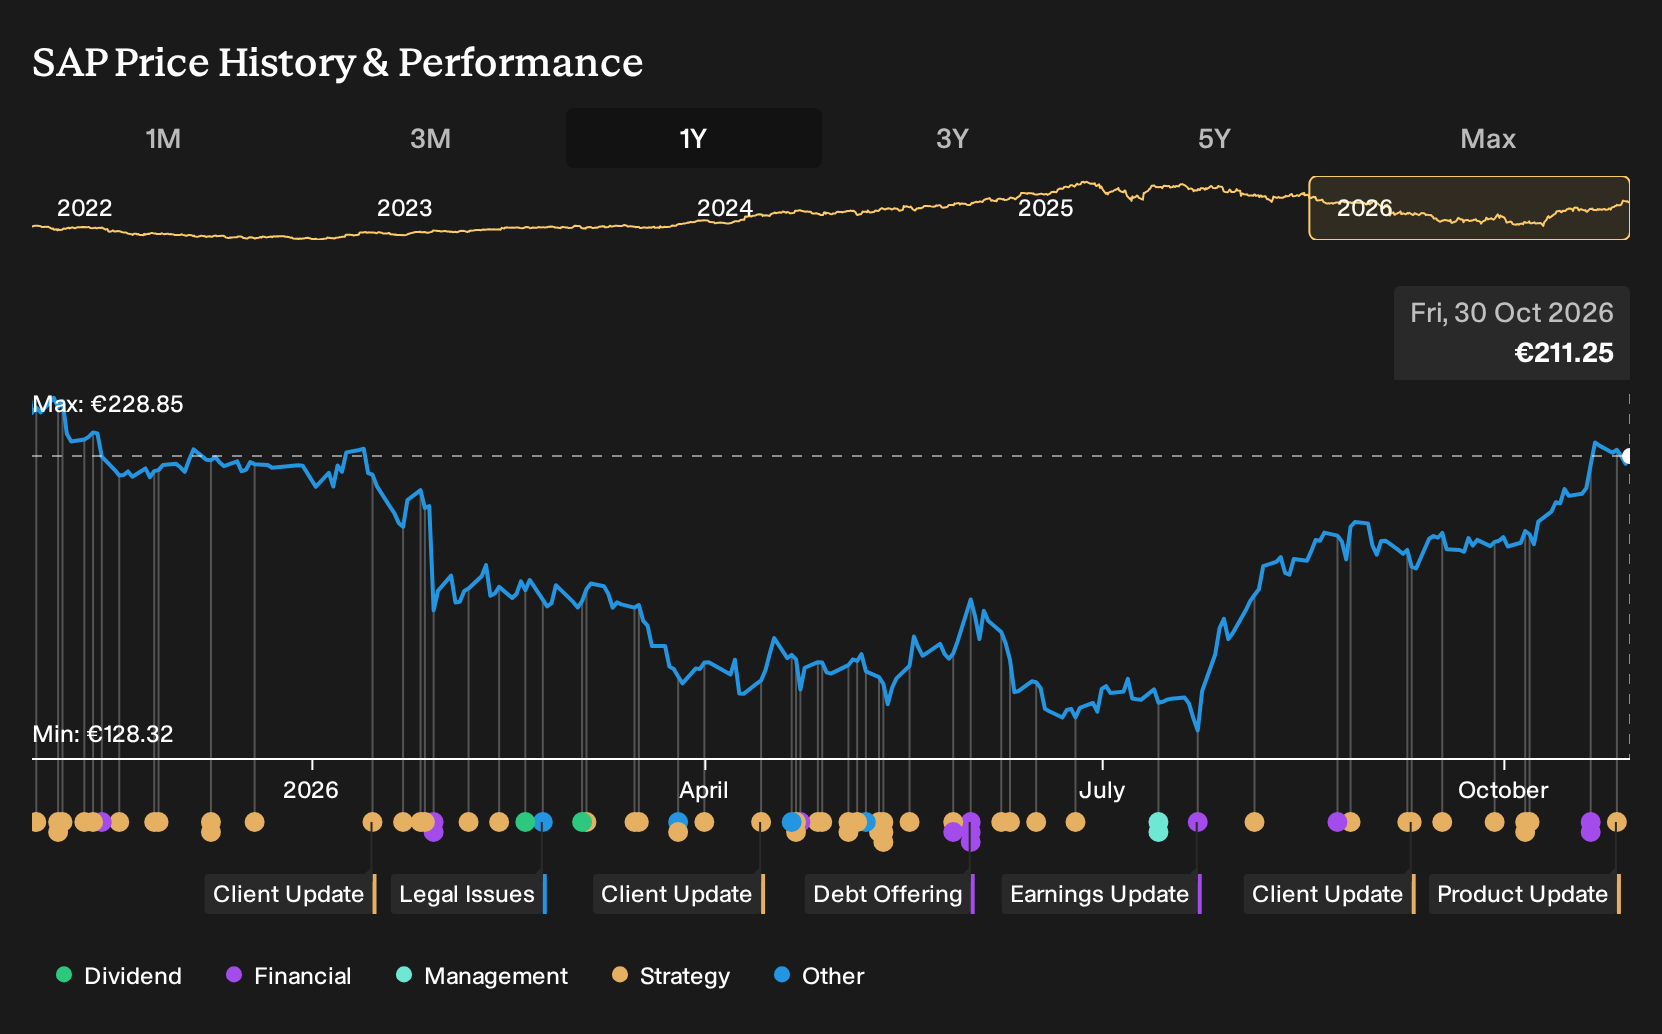
SAP's narrative projects €53.2b revenue and €11.2b earnings by 2029. This leans on analysts modelling 11.7% yearly revenue growth and an earnings increase of about €3.4b from €7.8b today.
Uncover why SAP's fair value aligns with its current price.
Exploring Other Perspectives
One alternate, more optimistic view on SAP leans heavily on this AI agent story. That camp was already modelling revenue of about €57.4b and earnings of €12.8b by 2029, compared with the €53.2b and €11.2b in the baseline. Those higher forecasts came before this TechEd news, so you may see those narratives shift again.
Explore 10 other SAP fair value estimates, including one that suggests as much as 49% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your SAP research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for SAP. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SAP's overall financial health at a glance.
Looking for more investment ideas beyond SAP?
Once you have a view on SAP, it can help to widen the lens and compare it with other opportunities that fit different risk and income profiles. The Simply Wall St Screener gives you a structured way to do that without getting lost in thousands of tickers.
- If capital preservation matters most to you, scan a curated 218 resilient stocks with low risk scores that score well on resilience and balance sheet strength.
- For investors hunting for value, work through a 199 high quality undervalued stocks that combine solid fundamentals with more appealing P/E and P/S profiles.
- If you prefer dependable income, focus on a 221 dividend fortresses that aim to pair higher yields with more robust underlying businesses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com