


EN
Escalade (ESCA) Stock Slips After Q3 Results Highlight Margin Gains
Escalade stock slipped 2.2% to US$19.70 in the first full trading day after its Q3 2026 results, a modest pullback for a leisure equipment business that has quietly been rerating over the past year. The headline was not about sales, which came in at US$65.6m. The real story was profit quality. Net income of US$6.7m and basic earnings per share of US$0.49 arrived against a backdrop of stronger margins and healthier cash generation that matter far more than a single day’s share price dip.
Like the margin resilience at Escalade but want a wider set of companies pairing healthy profitability with solid balance sheets and cash generation? Scan our list of solid balance sheet and fundamentals stocks (25 results) for a broader benchmark set.
Q3 2026 Escalade Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$65.608m vs. US$67.786m (3.2% decline)
- Net Income (Q3 2026 vs. Q3 2025): US$6.733m vs. US$5.554m (21.2% increase)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.49 vs. US$0.40 (21.5% increase)
- Trailing Net Profit Margin (Last 12 Months vs. Prior Year): 10.0% vs. 5.3% (margin roughly doubled, indicating stronger profitability)
Tired of scrolling through pages of earnings tables and raw figures to piece together what Escalade is really doing? Get the full visual picture of the business, including a clear view of valuation, in an easy dashboard via our company report for Escalade.
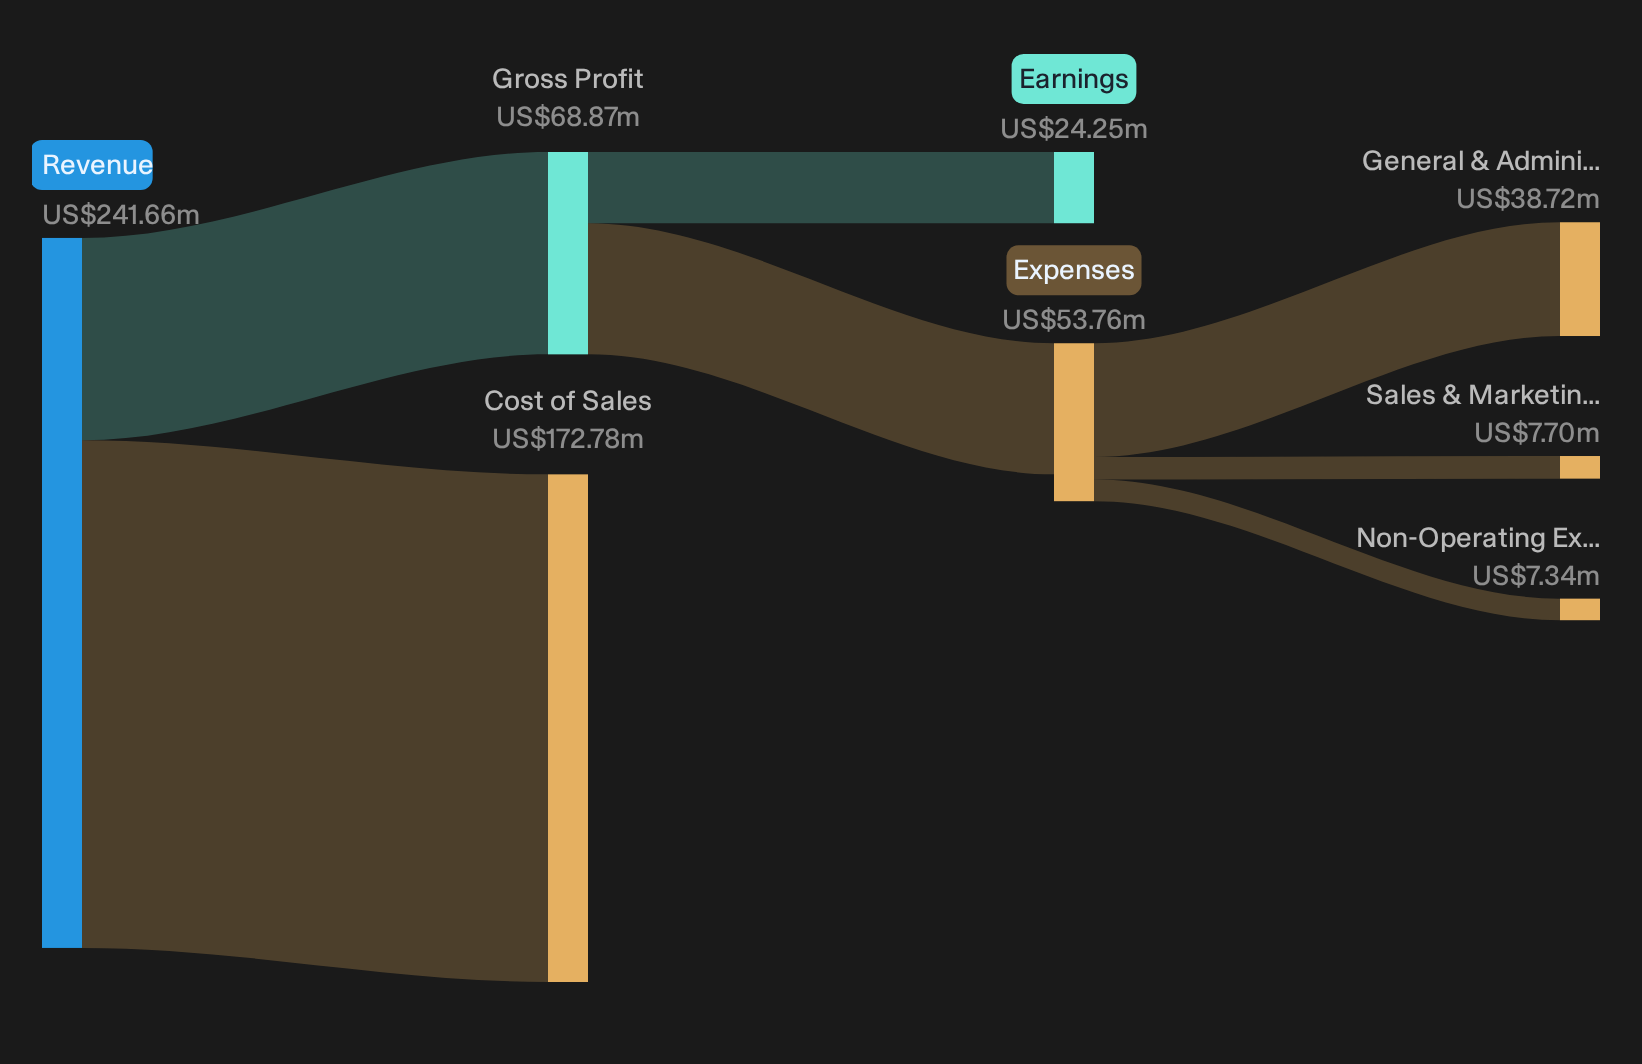
Escalade Bull Case: Margins, Cash, Flexibility
For a bullish narrative on Escalade, the earnings quality matters more than the modest 3% sales decline. Net income rose while revenue slipped, and gross margin moved higher, which fits a thesis that this is a brand portfolio getting more disciplined and profitable, not just bigger. Strong operating cash flow and a net cash position after repaying debt give management room to keep backing product launches and selective deals. For investors who like the multi brand, multi channel story, these numbers lean in favor of a business model that can still generate cash in a soft patch.
Escalade Bear Case: Volume Drag And One Off Help
Bearish arguments on Escalade focus on volume risk and the quality of support behind current earnings. Net sales fell, with pressure in basketball, indoor games and table tennis, which are key everyday recreation categories. Some of the cash and profit lift came from tariff refunds, which are not repeatable by design. Heavy holiday promotions could also lean on pricing if demand slows. All debt being classified as current is a reminder that refinancing and liquidity need attention. Even with better profitability this quarter, concerns around demand durability and cleaner earnings power are not fully addressed.
Do Wall Street analysts think Escalade’s cleaner margins and stronger cash generation justify the current setup or call for a reset? Check the consensus price target analysis for Escalade.
Hunt For Mispriced Earnings Power
Escalade just showed how a cleaner profit story can still meet a limited share price reaction. The real opportunity is spotting stocks that could be undervalued before the market closes that gap.
- Company 1 - 30% below our estimate - uses AI centric networking gear and long term supply deals to anchor recurring infrastructure contracts.
- Company 2 - 48% below our estimate - turns a record project backlog in technology heavy data center builds into tightly scheduled, higher margin modular installs.
- Company 3 - 20% below our estimate - grows a multi feature payments account where rising customer balances and interest sharing deepen fee and yield based revenue.
Those are three of them. See the full list of 29 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com