


EN
Middlesex Water (MSEX) Stock Price Rises After Q3 Earnings Margin Gain
Middlesex Water stock edged up 2.6% to US$56.79 after the market digested its Q3 2026 report, a calm move for what is essentially a regulated utility story. At first glance, traders reacted to a clean headline, with basic earnings per share of US$0.95 on revenue of US$60.2 million.
The real tension sits in the longer view. Earnings over the past year rose faster than sales, lifting net profit margin to 24.5%. That creates a useful split screen for investors. In the short term, the numbers look solid. Over several years, the question is how durable that profitability trend is against a valuation that already reflects a full utility premium.
Like the clean profit margin at Middlesex Water but wary that a full utility premium could cap your upside? Compare this setup with our screener of list of solid balance sheet and fundamentals stocks (25 results) to see how other regulated style stocks pair robust profitability with sturdier fundamentals.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$60.2m vs. US$54.1m (up about 11%)
- Net Income (Q3 2026 vs. Q3 2025): US$18.0m vs. US$13.9m (up about 29%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.95 vs. US$0.77 (up about 23%)
- Net Profit Margin (Q3 2026 vs. prior year): 24.5% vs. 22.0% (margin higher year over year)
Earnings for Middlesex Water look clean on the surface, but investors who care about valuation usually pay closer attention to the cash flowing through the business. If you focus on Middlesex Water's cash generation and how it is priced today, the stock could be a whopping 39% overvalued.
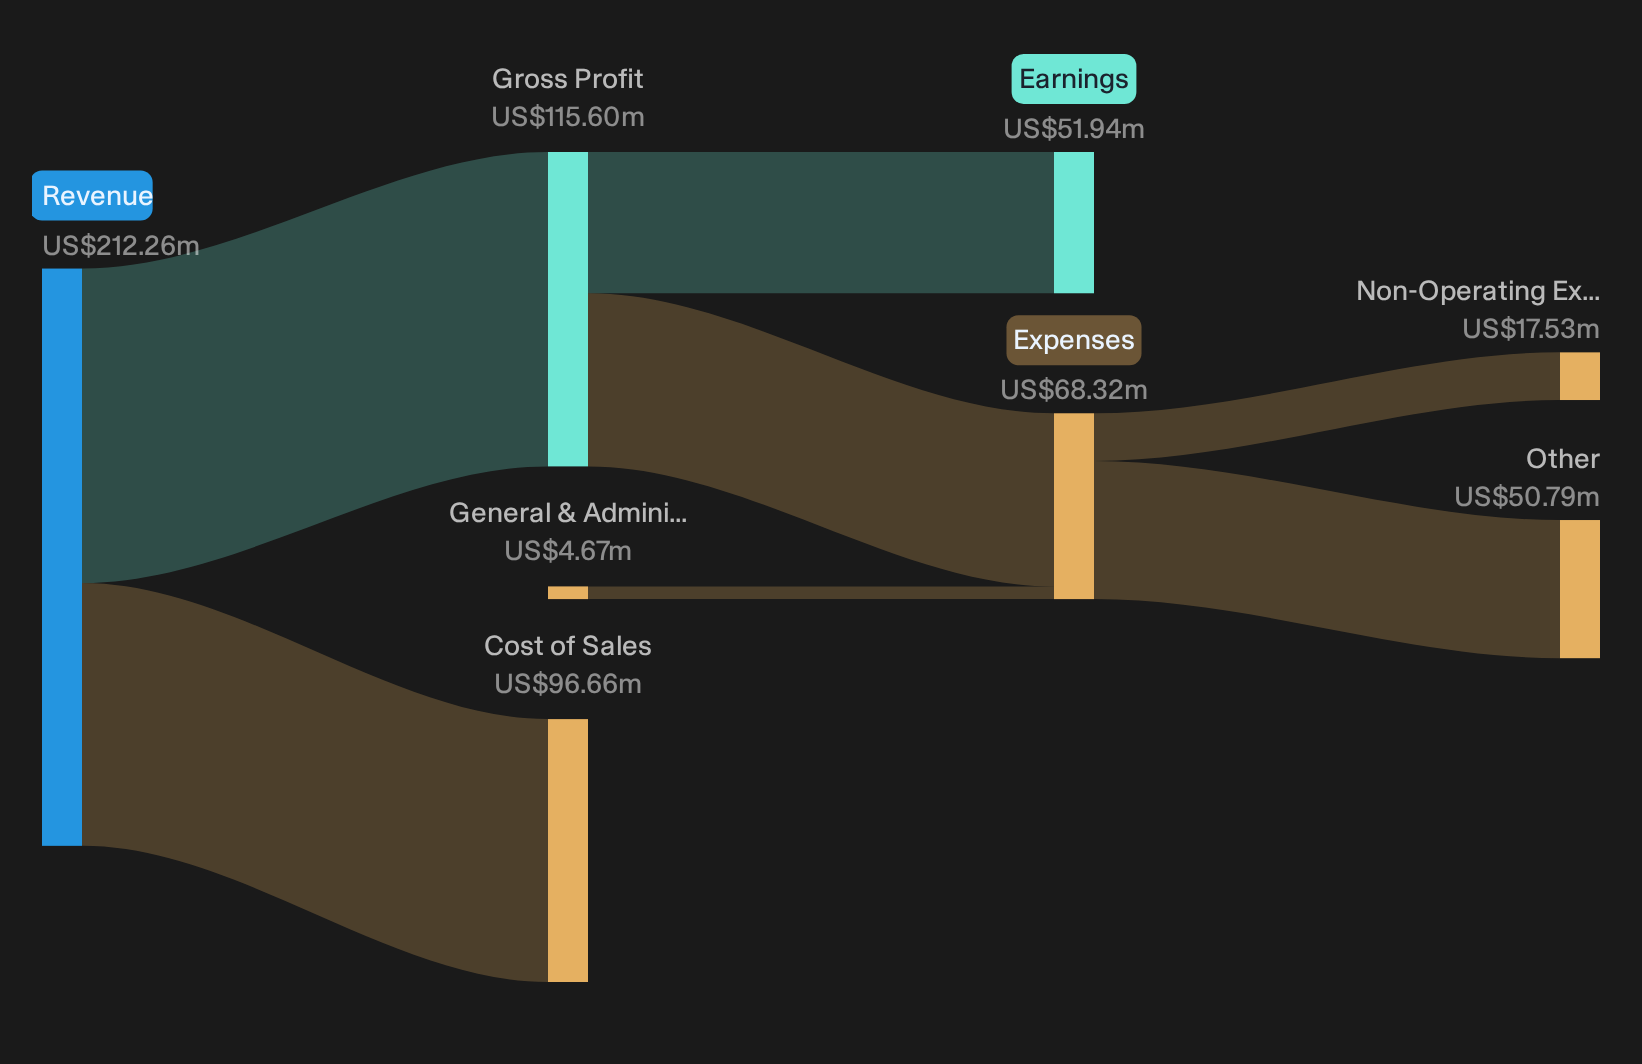
Stronger Q3 supports Middlesex Water optimism
Middlesex Water just delivered revenue of US$60.2m with net income of US$18.0m and basic EPS of US$0.95, all higher than the prior Q3 comparisons. Profitability moved the right way, with net margin at 24.5% versus 22.0% a year earlier. That pattern fits the steady, defensive utility narrative, where a regulated model helps translate modest top line progress into firmer earnings. A 5.56% dividend lift and a 2.6% share move after results also align with an income oriented, mildly bullish view on the business model.
Premium utility story still faces constraints
The Q3 step up in margin and earnings does not erase the usual regulated utility concerns. Revenue growth trails the jump in profit, which can raise questions about how much of the recent strength comes from mix, timing, or cost discipline that might be harder to repeat. The capital intensive profile and rate sensitivity highlighted in the cautious narrative still matter, because the figures say little about funding needs or future allowed returns. A slightly higher share price and modest 90 day decline indicate that enthusiasm is present but contained.
After a jump in earnings that reflects tighter cost controls while debt and dividend coverage appear less comfortable, it is reasonable to ask whether this is the full story or just the visible part of a deeper structural issue. Review the risk analysis for Middlesex Water which shows 2 important warning signsHunt For Mispriced Infrastructure Cashflows
Middlesex Water reports a steady quarter and modest share move that still leaves questions about long term value. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 31% below our estimate - builds high performance chips and networking hardware that keep data moving reliably for hyperscalers and large enterprises.
- Company 2 - 27% below our estimate - sells grid diagnostics and RF testing gear utilities and defense contractors rely on as electrification and aerospace programs scale.
- Company 3 - 48% below our estimate - converts a record backlog of data center and modular construction projects into long duration mechanical and electrical service work.
Three companies from the same screener. Open the full list of 29 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com