


EN
FedEx Freight Holding Company (FDXF) Jumps On Fresh Earnings As Valuation Still Looks Undemanding
FedEx Freight Holding Company (FDXF) just posted third quarter and four-month earnings to September 30, 2026, giving investors fresh numbers on revenue, profits, and per-share performance during its early life as an independent business.
That fresh earnings update landed alongside a sharp move in the stock. FedEx Freight Holding Company’s 1-day share price return of 14.91% and 7-day share price return of 14.53% lifted the shares to US$126.04, although the year to date share price return is still down 16.53%, so near term momentum is improving while the longer trend remains weaker.
Spot opportunities moving on similar earnings momentum by scanning our hand-picked list of 18 high quality undiscovered gems alongside FedEx Freight Holding Company.FedEx Freight Holding Company’s quick rebound, strong recent earnings beat, and softer longer term share performance put the spotlight on valuation. Does the balance of risk and potential reward still lean toward buyers at US$126?
Price-to-Earnings of 28.8x: Is it justified?
On simple valuation math, FedEx Freight Holding Company trades on a P/E of 28.8x, which puts the current $126.04 share price at a lower earnings multiple than both the wider US Transportation industry on 30.6x and the peer group average on 40x.
The P/E ratio tells you how many dollars investors are paying today for each dollar of earnings. For a freight carrier like FedEx Freight Holding Company, it effectively reflects how the market is weighing its earnings profile, sector exposure, and forecast growth against other transportation stocks.
With earnings forecast to grow 16.2% per year and revenue expected to expand 4.7% per year, a P/E below both the industry and peer averages suggests the market is applying a more conservative tag to those future profits. That discount sits alongside a mixed quality picture, including high levels of non cash earnings and profit margins that declined from 15.1% to 7.4%, which could also be holding back the multiple.
Compared with the sector at 30.6x and peers at 40x, the 28.8x P/E signals a clear valuation gap. The market is pricing FedEx Freight Holding Company at a lower earnings multiple than many comparable transportation stocks, which could either reflect caution around its new listing status, governance issues such as a very fresh board and limited independence, or simply a less aggressive view on its future earnings power.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 28.8x (UNDERVALUED)
Still, FedEx Freight Holding Company faces real pressure if freight volumes soften further or if governance concerns around a very new board start to weigh more heavily.
Find out about the key risks to this FedEx Freight Holding Company narrative.
Another View: SWS DCF model on FedEx Freight Holding Company
The market is valuing FedEx Freight Holding Company at $126.04 per share, while the SWS DCF model estimates future cash flows at $152.01 per share. That 17.1% gap points to a stock that screens as undervalued according to this method. Which signal would you weigh more heavily: earnings multiple or cash flow value?
Look into how the SWS DCF model arrives at its fair value.
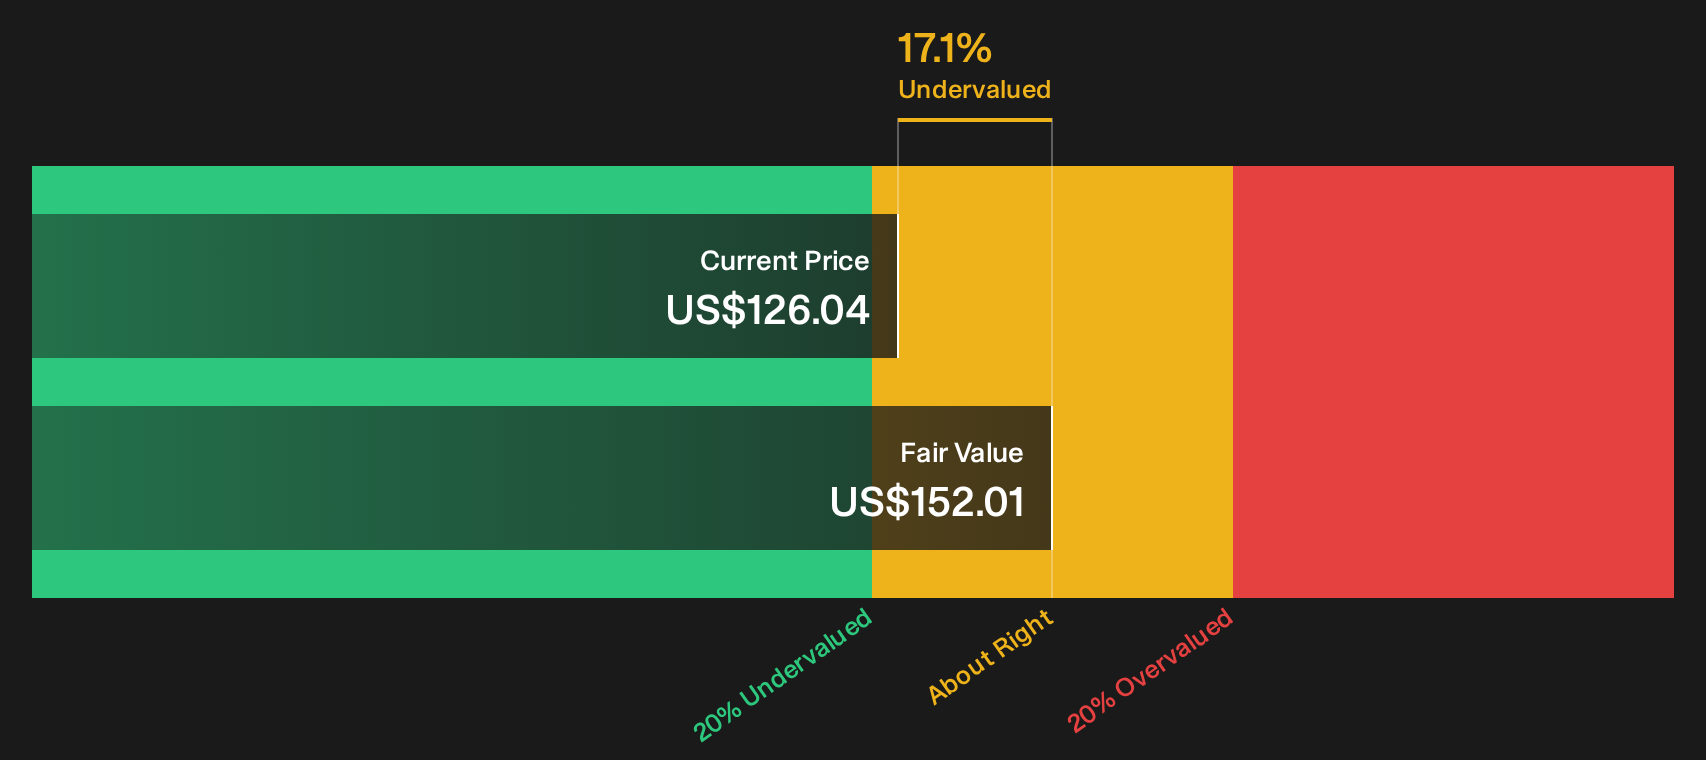
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out FedEx Freight Holding Company for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the numbers and valuation can be confusing, so move quickly to review the full picture and decide what stacks up for you. To see both the upside signals and the areas investors are worried about, start with these 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond FedEx Freight Holding Company?
Do not stop at a single stock. Use the Simply Wall St screener to line up fresh opportunities that fit your style before others get there first.
- Zero in on potential mispricing by scanning a focused set of 29 high quality undervalued stocks that pair quality fundamentals with compressed expectations.
- Prioritise resilience by checking a 30 resilient stocks with low risk scores that highlights companies with stronger balance sheets and fewer red flags.
- Get ahead of the crowd by tracking a 9 elite penny stocks with strong financials that filters for smaller stocks with healthier numbers than many larger peers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com