


EN
Ingersoll Rand (IR) Stock Faces Q3 Earnings Valuation Gap
Ingersoll Rand just reported Q3 2026 numbers that look far stronger than the share price suggests. The stock barely moved, up only 0.05% to about US$80 after the release, even as basic earnings per share increased to US$1.74 on roughly US$2.06b of revenue. That gap between a flat share price and a significant earnings move is the key point. This is a sentiment reset in which traders appear cautious about a report focused on expanding profitability rather than headline revenue growth.
Love that Ingersoll Rand is focusing on profitability but concerned about paying a premium for a stock that barely reacts to stronger earnings? Compare this setup with our curated list of companies in the 29 high quality undervalued stocks that balance solid financials with more compelling valuations.
Q3 2026 Earnings Summary
- Total Revenue, Q3 2026 vs Q3 2025: US$2,064.9m vs. US$1,955.0m (up about 6%)
- Net Income (Excl. Extra Items), Q3 2026 vs Q3 2025: US$669.9m vs. US$244.1m (up about 174%)
- Basic EPS, Q3 2026 vs Q3 2025: US$1.74 vs. US$0.62 (up about 181%)
- Trailing 12-Month Net Profit Margin, Q3 2026 vs Prior Year: 17.2% vs. 7.3% (margin level more than doubled)
Earnings tell you what Ingersoll Rand booked this quarter, but investors who care about valuation usually want to see how consistently those profits turn into cash. When you compare Ingersoll Rand's cash flows with the current share price, the stock could be a modest 14% undervalued.
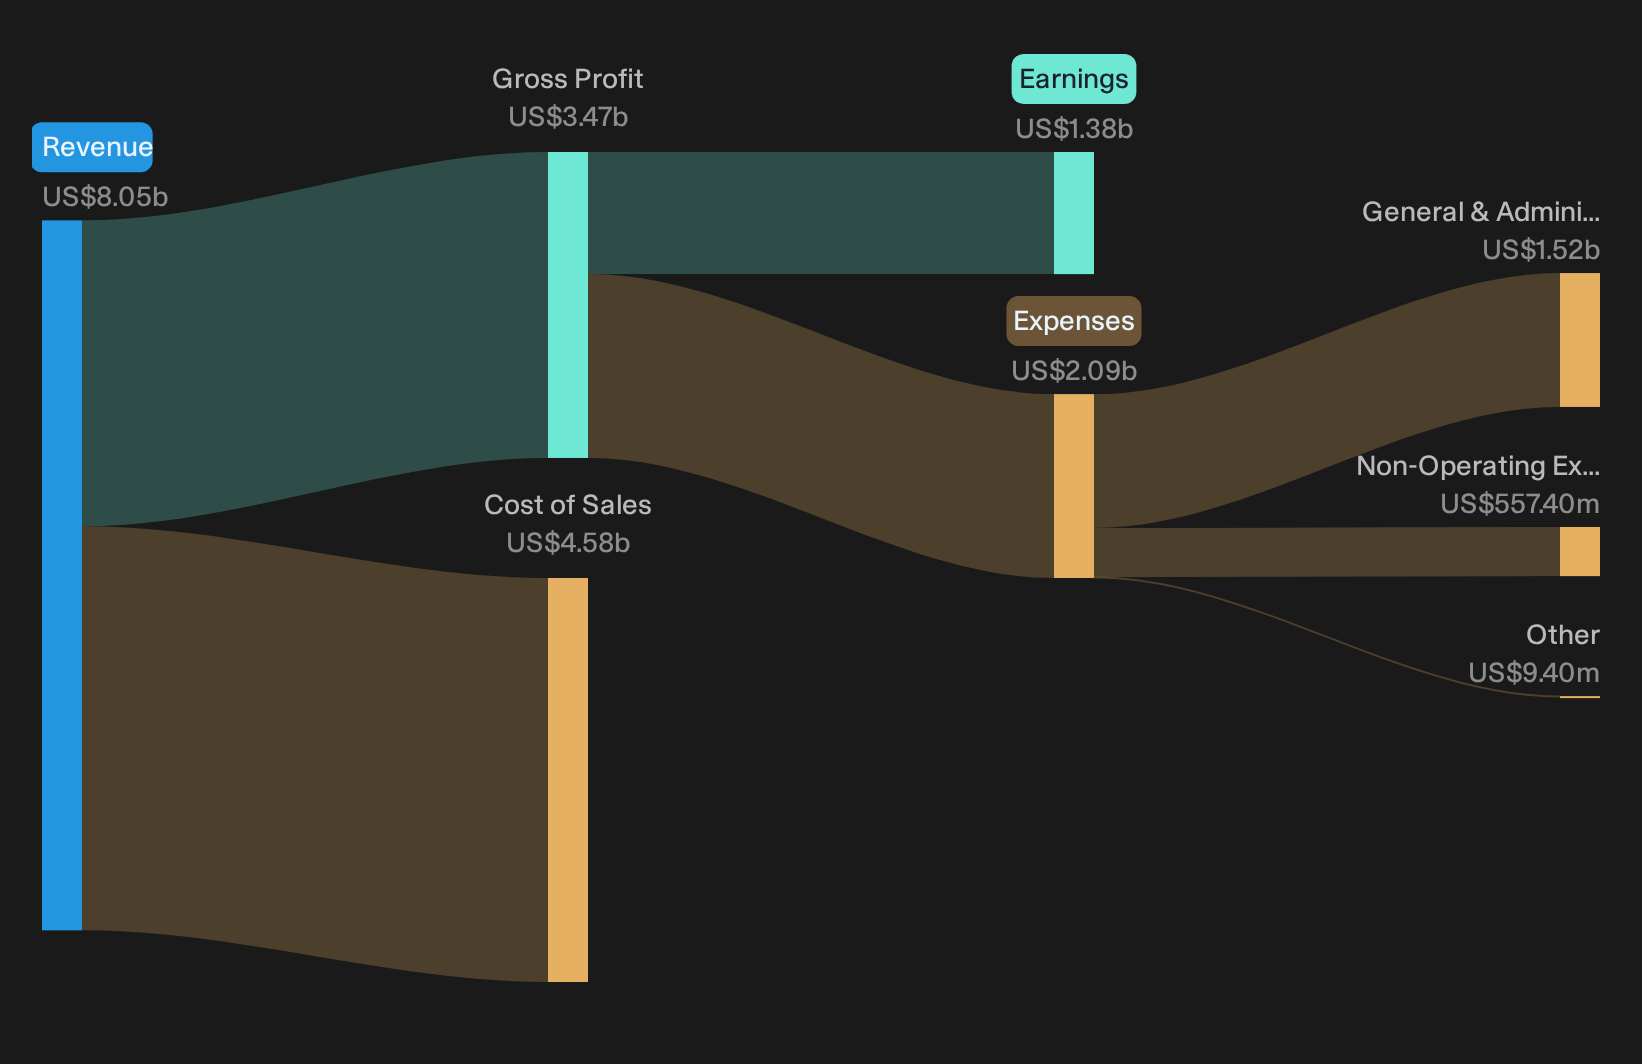
Evaluating Whether M&A And Services Are Really Driving IR
The bullish script argues that Ingersoll Rand’s upside now leans on deeper deal flow and a heavier service tilt rather than pure equipment cycles.
"Bullish analysts expect Ingersoll Rand to keep expanding aftermarket and recurring revenue, supported by higher margin PST growth and an active funnel of bolt on deals, so that earnings quality becomes less cyclical over time."
Q3 shows real, if measured, progress toward that aim. Aftermarket reached 36% of sales and grew in the mid single digits, while P&ST held EBITDA above 32%. M&A is active, with 8 deals closed or signed and management still targeting several hundred basis points of acquired growth, although the 2026 contribution is running below the 400 to 500 bps ambition.
The price and this Narrative do not agree. → Uncover what this Narrative says Ingersoll Rand is actually worth.
Ingersoll Rand: Margin Fears Not Fully Put To Bed
Bearish investors worry that Ingersoll Rand’s acquisition push and China pricing could keep profitability under strain even as recurring revenue grows.
"Bearish analysts expect Ingersoll Rand to see its focus on M&A keep margins under pressure, as integration costs and China price headwinds continue to weigh on profitability."
Q3 does not fully clear that bar. Adjusted EBITDA guidance is unchanged, and management now points to finishing in the lower half of the US$2.13b to US$2.19b range. IT&S margins excluding refunds sit below the 30% level, and the large data center ETO contract starts with below average profitability. The earnings lift is real, but the margin reset concern is not disproved yet.
Hunt For Quiet Mispricings
Ingersoll Rand recently showed how earnings strength and share price can diverge. The real opportunity is finding stocks that appear undervalued before the market reassesses them.
- Company 1 - 47% below our estimate - turns intensive spending on AI data centers into systems powering targeted advertising, enterprise messaging and early mixed-reality hardware.
- Company 2 - 31% below our estimate - supplies cloud superclusters that high-intensity AI developers adopt when they need scalable, multi-cloud compute for training and inference workloads.
- Company 3 - 37% below our estimate - uses acquired banks and lower-cost, diversified deposits to adjust its lending mix and pursue more stable profitability.
Three companies from the same screener. Open all 29 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com