


EN
CubeSmart (CUBE) Stock Gains Focus After Q3 Earnings Beat
CubeSmart came into this Q3 2026 report with a reputation as a steady, income focused self storage real estate investment trust, yet the fresh numbers tell a more active story. The stock jumped 4.0% on the first full trading day after results, pushing the price to US$42.74. That move lines up with one clear headline: Funds From Operations, the key cash earnings metric for storage REITs, landed at the high end of guidance, while same store net operating income turned positive and gave investors a cleaner read on underlying property performance.
If you appreciate CubeSmart’s steady FFO and income profile but want a wider mix of resilient balance sheets and strong cash generators in your watchlist, compare it with our curated screener of list of solid balance sheet and fundamentals stocks (25 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): US$293.968 million vs. US$285.728 million (up about 3%)
- Net Income (Excl. Extra Items, Q3 2026 vs Q3 2025): US$94.355 million vs. US$82.93 million (up about 14%)
- Basic EPS (Q3 2026 vs Q3 2025): US$0.418171 vs. US$0.36247 (up about 15%)
- Funds From Operations (FFO, Q3 2026 vs Q3 2025): Not disclosed for Q3 2026 vs. US$148.971 million (direction not specified for the latest quarter)
Earnings tell part of CubeSmart’s story, but investors who care about what they are paying for usually anchor on the cash flowing through the business. Look at CubeSmart’s cash flows in isolation and the stock could be a clear 20% undervalued.
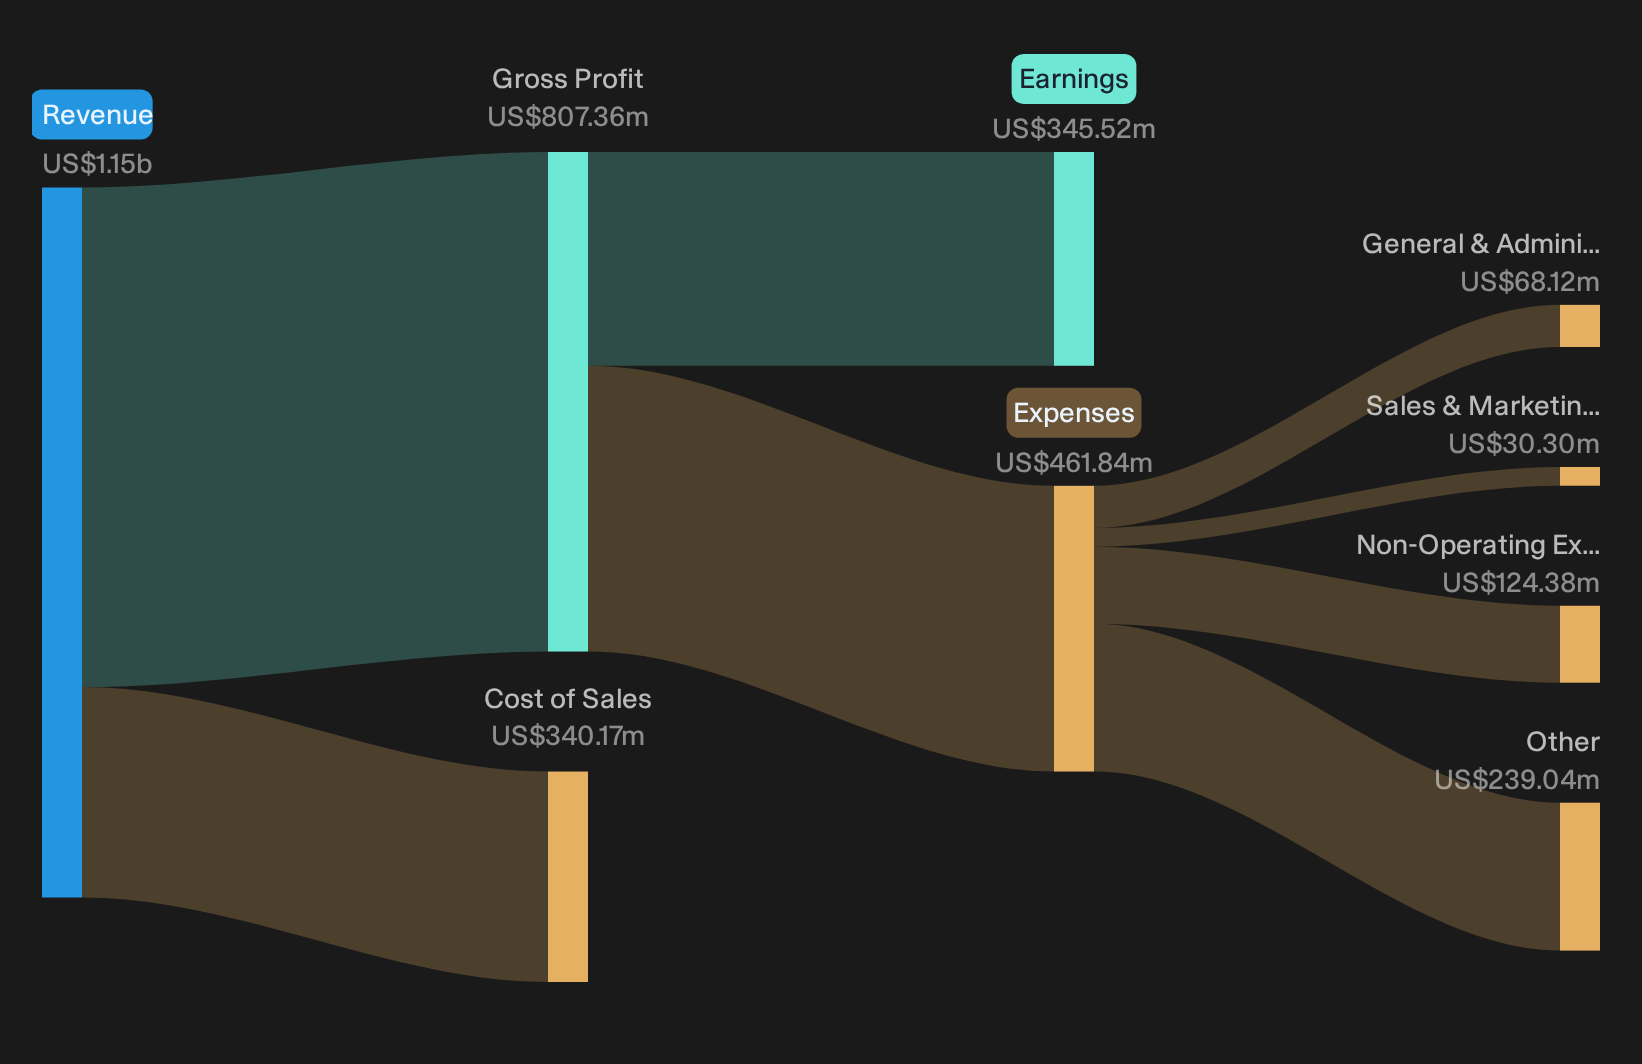
CubeSmart Bull Case: Fundamentals Finally Turn The Corner
The optimistic script hinges on healthier properties converting stabilising demand into cleaner earnings power.
"Easing new supply pressure, with only 19% of CubeSmart's same-store properties affected by new deliveries in 2026 compared with 50% at an earlier peak, leaves a larger share of the portfolio positioned to convert stabilising occupancy into higher revenue and same-store NOI as absorbed projects mature."
Q3 backs that up. Same store revenue growth stepped up to 1.9%, expenses rose a slower 1.3%, and same store NOI increased 2.1%. FFO per share at US$0.66 hit the top of guidance. Urban markets led, with New York revenue up 5.4% and 17 of 20 key markets accelerating.
CubeSmart Bear Case: Cost Creep And Sunbelt Concerns Tested
The cautious view argues that higher operating costs and weaker Sunbelt pricing could cap any recovery.
"Same-store operating expenses are rising faster than same-store revenue, with Q1 2026 expenses up 5.8% against 0.6% revenue growth and Q2 2026 expenses up 4.4% against 0.8% revenue growth. This has already led to declines in same-store NOI and could continue to pressure CubeSmart's net margins and earnings if this gap does not narrow."
Recent figures show that gap narrowing. In Q3, expense growth at 1.3% trailed revenue, flipping same store NOI back to growth. Sunbelt and West Coast markets are described as improving on the second derivative, while the third party platform expanded to 882 stores, which supports fee income rather than signalling weakness.
The price and this Narrative do not agree. → Uncover what this Narrative says CubeSmart is actually worth.
Hunt For Quiet Fundamental Shifts
CubeSmart just reminded investors that sentiment can change quickly when earnings update expectations. The real opportunity is finding stocks that may be mispriced before any valuation reset begins.
- Company 1 - 19% below our estimate - targets overseas teahouse expansion while testing how franchise and company store returns evolve.
- Company 2 - 38% below our estimate - deepens device trade in programs built around refurbishment partners and policy supported recycling incentives.
- Company 3 - 35% below our estimate - sells GPU systems and software stacks used as data center workloads tilt toward AI.
That is three of the list. See all 29 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com