


EN
Xcel Energy (XEL) Q3 Results Spotlight Financing Strain Behind Growth
Xcel Energy just delivered its Q3 2026 scorecard, and the stock barely flinched. Shares ticked up about 1% to US$79.82 into the close, a muted move for a utility that just reported US$1.53 in basic earnings per share and a trailing net margin of 17.9%.
The emotional story is different. Traders appear to be treating this as another steady quarter from a regulated power company. However, the results highlight one issue that will shape sentiment from here: a large capital plan and the related financing needs that keep interest expense pressure in focus, even as profit metrics remain solid.
Love Xcel Energy’s steady earnings profile but concerned about the capital spending and interest cost drag on future returns? Compare that pattern with utilities and infrastructure stocks that pair regulated cash flows with stronger balance sheets in our list of solid balance sheet and fundamentals stocks (25 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$4,172 million vs. US$3,915 million (up 6.6%)
- Net Income (Q3 2026 vs. Q3 2025): US$960 million vs. US$524 million (up 83.2%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$1.53 vs. US$0.89 (up 72.4%)
- Trailing Net Margin (TTM to Q3 2026 vs. TTM to Q3 2025): 17.9% vs. 13.5% (higher profitability level)
Earnings tell one story about Xcel Energy, but investors who care about what the business is worth usually pay closer attention to the cash coming in and out of the company. Look through Xcel Energy's cash flows alone and the stock could be a modest 11% overvalued.
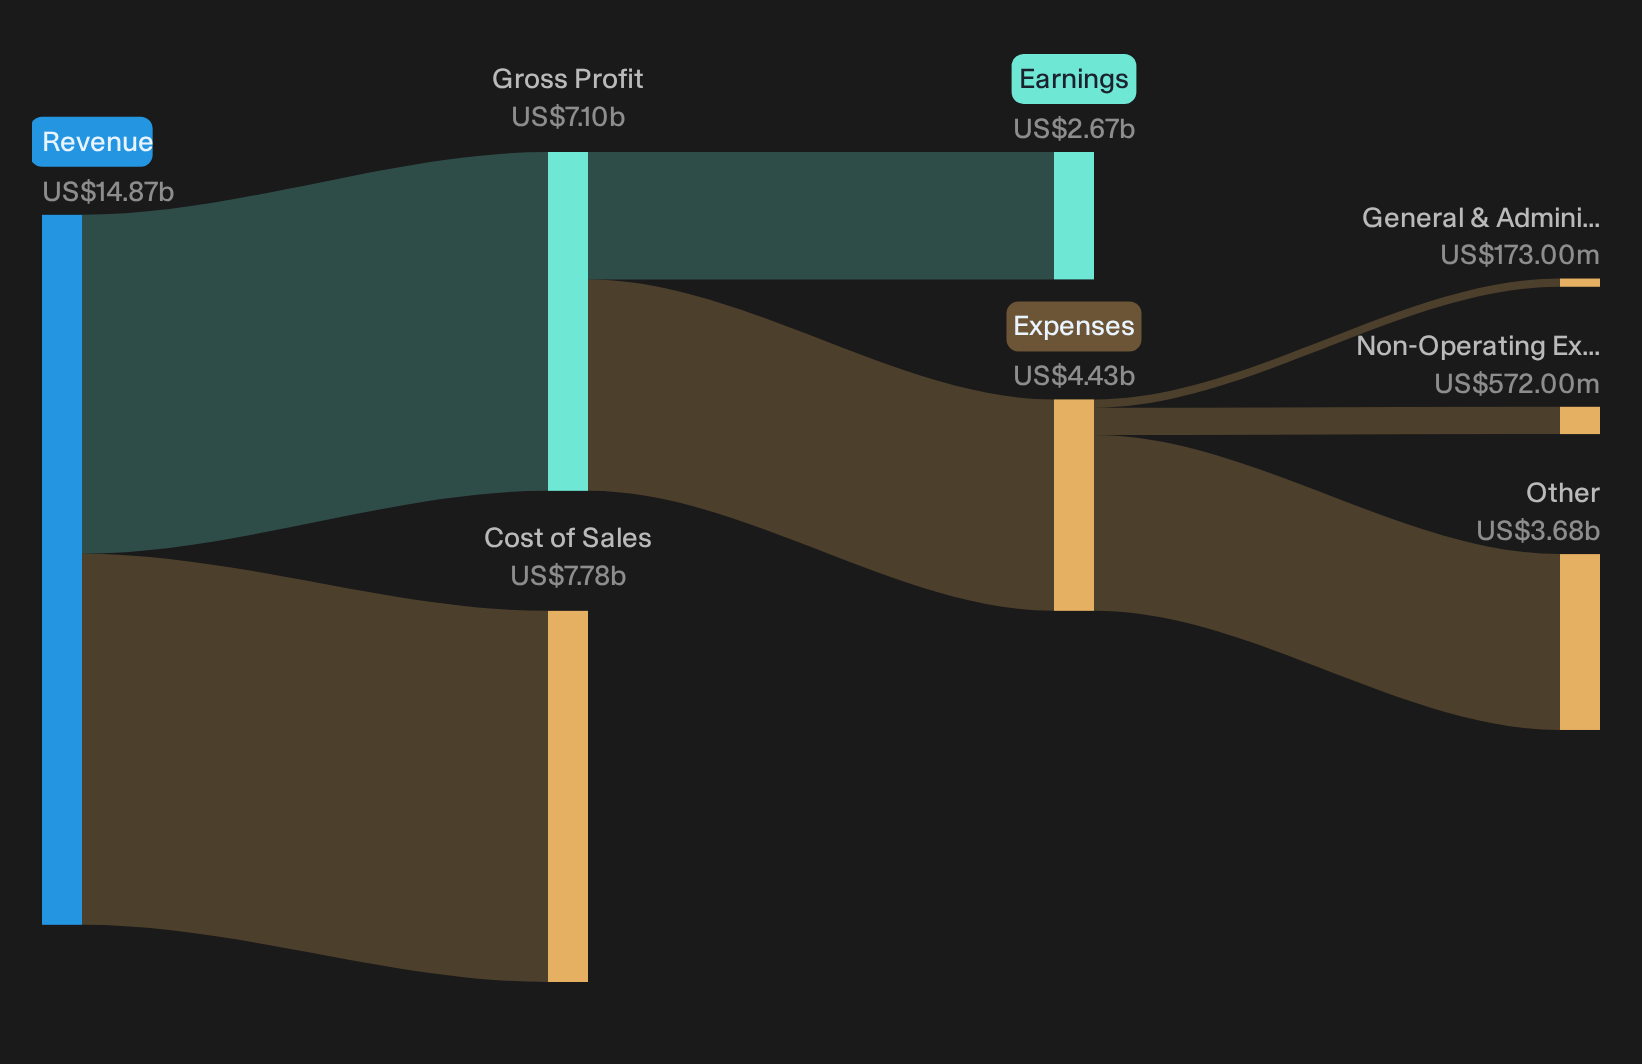
Xcel Energy’s Growth Story Meets Early Benchmarks
The bullish pitch rests on Xcel Energy turning a large capital agenda into sustained earnings expansion that lines up with management’s long term framework.
"Analysts expect Xcel Energy to use its more than $70b five year capital plan and multi decade clean energy and transmission build out to support long term EPS growth in line with management’s 6 to 8+% and 9+% through 2030 guidance."
Q3 ongoing EPS of US$1.52 and narrowed 2026 guidance of US$4.10 to US$4.16, plus new 2027 guidance of US$4.48 to US$4.62, all align with that 6 to 8% style glidepath. Roughly US$14b of 2026 capex and AFUDC support indicate that the buildout is already contributing to earnings, not just appearing as capex line items.
Capital Load, Wildfire Risk Test The Bear Story
The bear side argues that fire liabilities and a heavy build program could pressure the balance sheet and constrain this growth narrative.
"Wildfire risk remains an overhang for Xcel Energy, as research highlights that potential wildfire related liabilities could weigh on the balance sheet and the ability to comfortably fund the roughly 60b to 70b clean energy and grid program tied to data center demand."
Wildfire mitigation spending is already lifting O&M, while higher interest costs and equity dilution reduced Q3 EPS by US$0.23 in total. The updated 2027 to 2031 plan adds about US$26b of debt and US$8b of equity, with a targeted FFO, which is funds from operations, to debt ratio of 17%. That indicates financing strain is present, even as management cites headroom later in the decade.
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all.
Hunt For Mispriced Cash Flows
Xcel Energy just showed how a busy capital plan can keep sentiment split even when profitability holds up. The real opportunity could sit in stocks the market has not fully corrected yet.
- Company 1 - 38% below our estimate - uses government-backed trade-in subsidies and eco-conscious consumers to support a recommerce engine for used devices.
- Company 2 - 29% below our estimate - scales a low-cost digital bank model that turns rising customer engagement into higher revenue per active account.
- Company 3 - 47% below our estimate - pours heavy spending into AI infrastructure to support targeted ads, business messaging and mixed-reality products.
Three companies from the same screener. Open all 29 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com