


EN
Silgan Holdings (SLGN) Q3 Earnings Contrast Record Adjusted EPS And Margin Pressure
Silgan Holdings came into this Q3 2026 report with the stock already grinding higher, up about 16.6% over the past month, and the latest session added another 2.6% to close near US$40. The reputation is simple: a steady packaging supplier that is supposed to quietly compound earnings. The headline this time was different. Management delivered record adjusted earnings per share of US$1.31 and about US$2.0b of quarterly revenue, while investors barely flinched. That gap between a calm share price and punchy profit performance is the real story to watch.
Love the record US$1.31 per share and US$2.0b in revenue from Silgan Holdings but unsure if this kind of steady compounder profile is what you want more of in your portfolio? Compare it against a curated screener of similar quality stocks in our list of solid balance sheet and fundamentals stocks (25 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$2,040.2m vs. US$2,008.7m (up 1.6%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$105.0m vs. US$113.3m (down 7.3%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.99 vs. US$1.06 (down 6.6%)
- Trailing 12-Month Net Profit Margin (Q3 2026 vs. Q3 2025): 3.9% vs. 4.9% (compression of 1 percentage point)
Silgan boosted 2026 EPS guidance but stayed vague on 2027 cash. Ask Charlie what could unlock Silgan’s 2027 free cash flow.
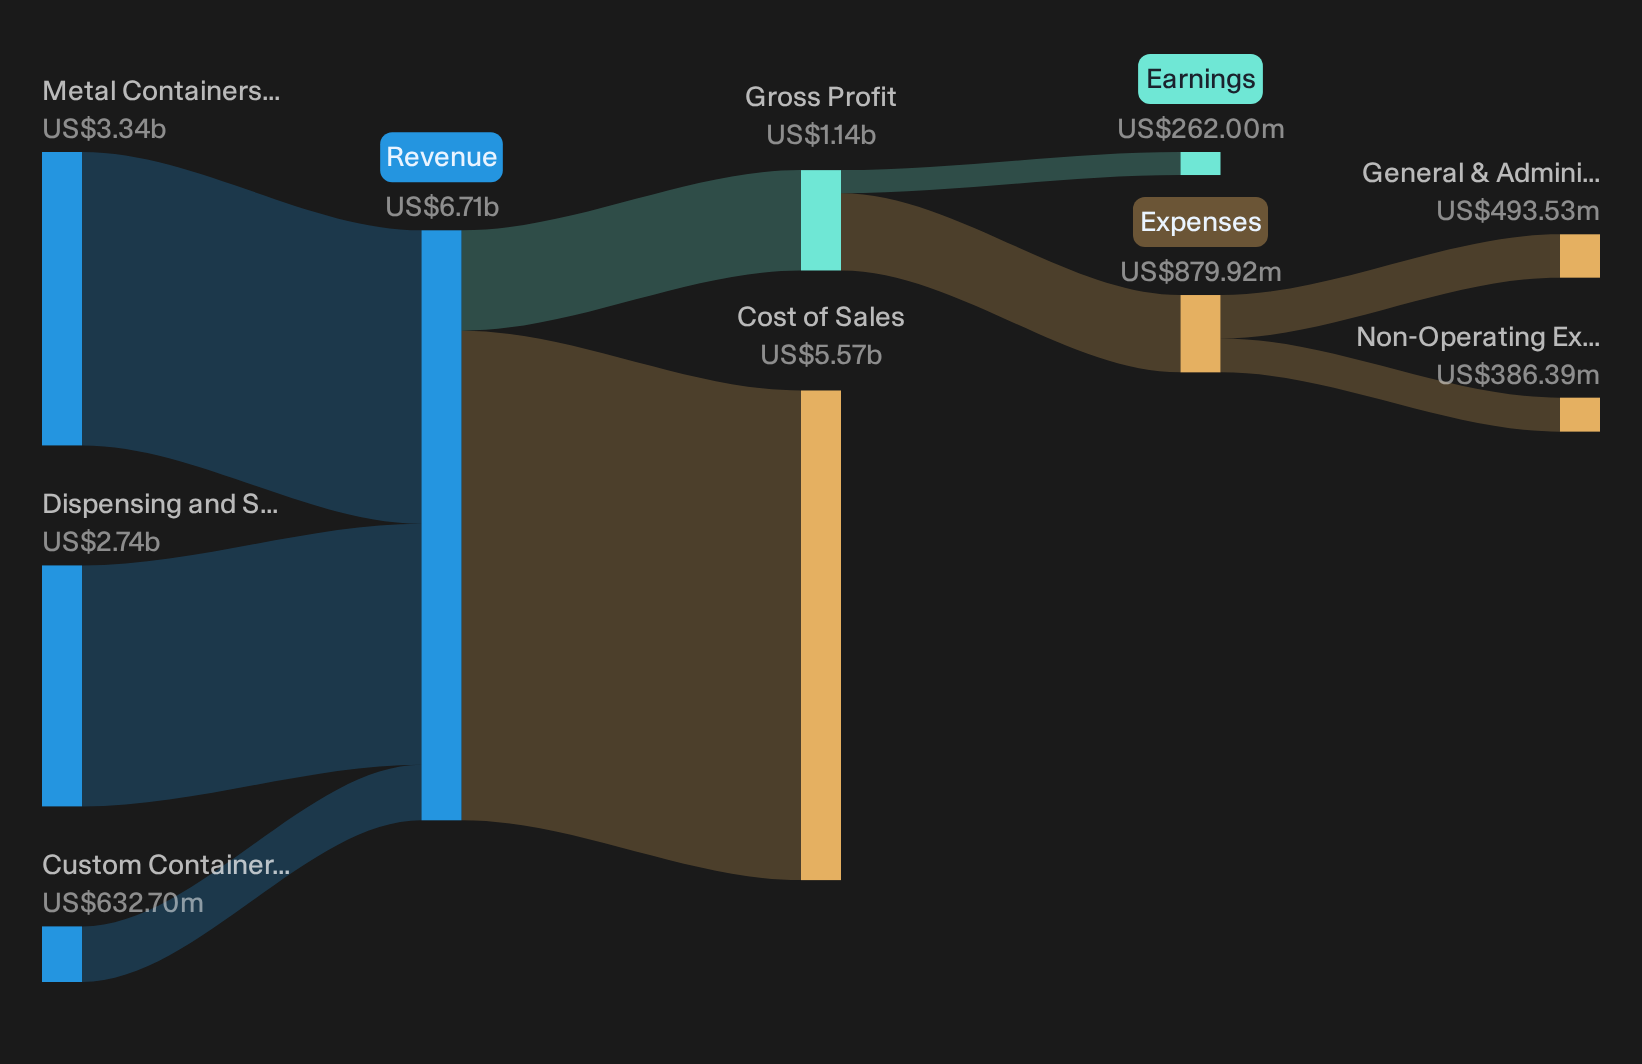
Silgan’s Cash‑Backed Shift Meets Key 2026 Markers
Supporters say Silgan Holdings is turning into a cash and contract story rather than a simple packaging volume story.
"Growth Is Not The Story, Cash Backed Earnings Quality Is"
The latest quarter lines up with that idea. Record adjusted EPS of US$1.31 with only 1.6% revenue growth shows earnings quality doing more work than volume. Custom Containers hit record adjusted EBIT while volumes fell as lower margin work was exited, which fits the mix shift claim. Management raised full year adjusted EPS guidance to a range of US$3.83 to US$3.93 and reaffirmed roughly US$450m of 2026 free cash flow, so the cash targets that support the bullish case remain intact for now.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Silgan Bear Case: Cost Friction Still Visible
Bears argue Silgan Holdings lacks enough margin and cash cushion when costs flare up or volumes wobble.
"Even with management targeting roughly US$450 million of annual free cash flow and benchmarking all capital allocation, including M&A, against share repurchases, external commentary that points to about 16.8% gross margin and a weak free cash flow margin suggests that any shortfall in earnings or higher capital intensity could again restrict capacity for reinvestment and dividends."
The latest quarter does not fully clear that hurdle. Net income excluding extra items fell 7.3% and basic EPS slipped 6.6%, while the trailing net margin compressed by 1 percentage point. The earnings cushion that would fully defuse this concern is not yet in place, even with reaffirmed US$450m free cash flow guidance.
Hunt For Quiet Price Dislocations
Silgan Holdings just reminded investors that earnings strength and share price reaction do not always move together. The real opportunity could be spotting stocks that could be undervalued before more investors fully price in the shift.
- Company 1 - 47% below our estimate - turns heavy spending on AI ads, infrastructure and devices into more personalized campaigns and new revenue streams.
- Company 2 - 34% below our estimate - turns long duration optical and solar supply contracts into steadier demand for its materials tied to data and energy buildouts.
- Company 3 - 38% below our estimate - builds a device recommerce network that matches trade in subsidies with refurbished supply for consumers.
Three companies from the same screener. Open every one of the 29 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com