


EN
Aecon Group (TSX:ARE) Stock Wavers Despite Strong Q3 Earnings Rebound
Aecon Group just closed at CA$49.23 after Q3 2026 earnings, with the stock coming off a choppy month that left it down about 9% over 30 days. That short term wobble meets a headline that is much harder to dismiss. The builder posted CA$1.92b in quarterly revenue and swung to a quarterly profit of CA$52.9m, a sharp break from losses earlier in the year.
For traders, the move in the share price may feel like the whole story. For anyone thinking in years rather than days, the real signal is the earnings rebound and what that may indicate for Aecon’s longer term cash generation and valuation strain.
Like the earnings recovery at Aecon Group but worried about how choppy the ride has been lately? Check out our list of construction and infrastructure peers that pair steadier price action with cleaner balance sheets in the list of solid balance sheet and fundamentals stocks (6 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): CA$1,920.6m vs. CA$1,530.2m (up about 26%)
- Net Income (Q3 2026 vs Q3 2025): profit of CA$52.9m vs. profit of CA$40.0m (higher earnings year on year)
- Basic EPS (Q3 2026 vs Q3 2025): CA$0.77 per share vs. CA$0.63 per share (EPS improved)
- Backlog (Q3 2026 vs prior quarter Q2 2026): CA$14.6b vs. the prior quarter level (up 39% quarter on quarter; record order book)
Tired of scrolling through dense tables and earnings summaries for Aecon Group? Get the full financial picture in an interactive format with a clear view of the company’s valuation setup in our company report for Aecon Group.
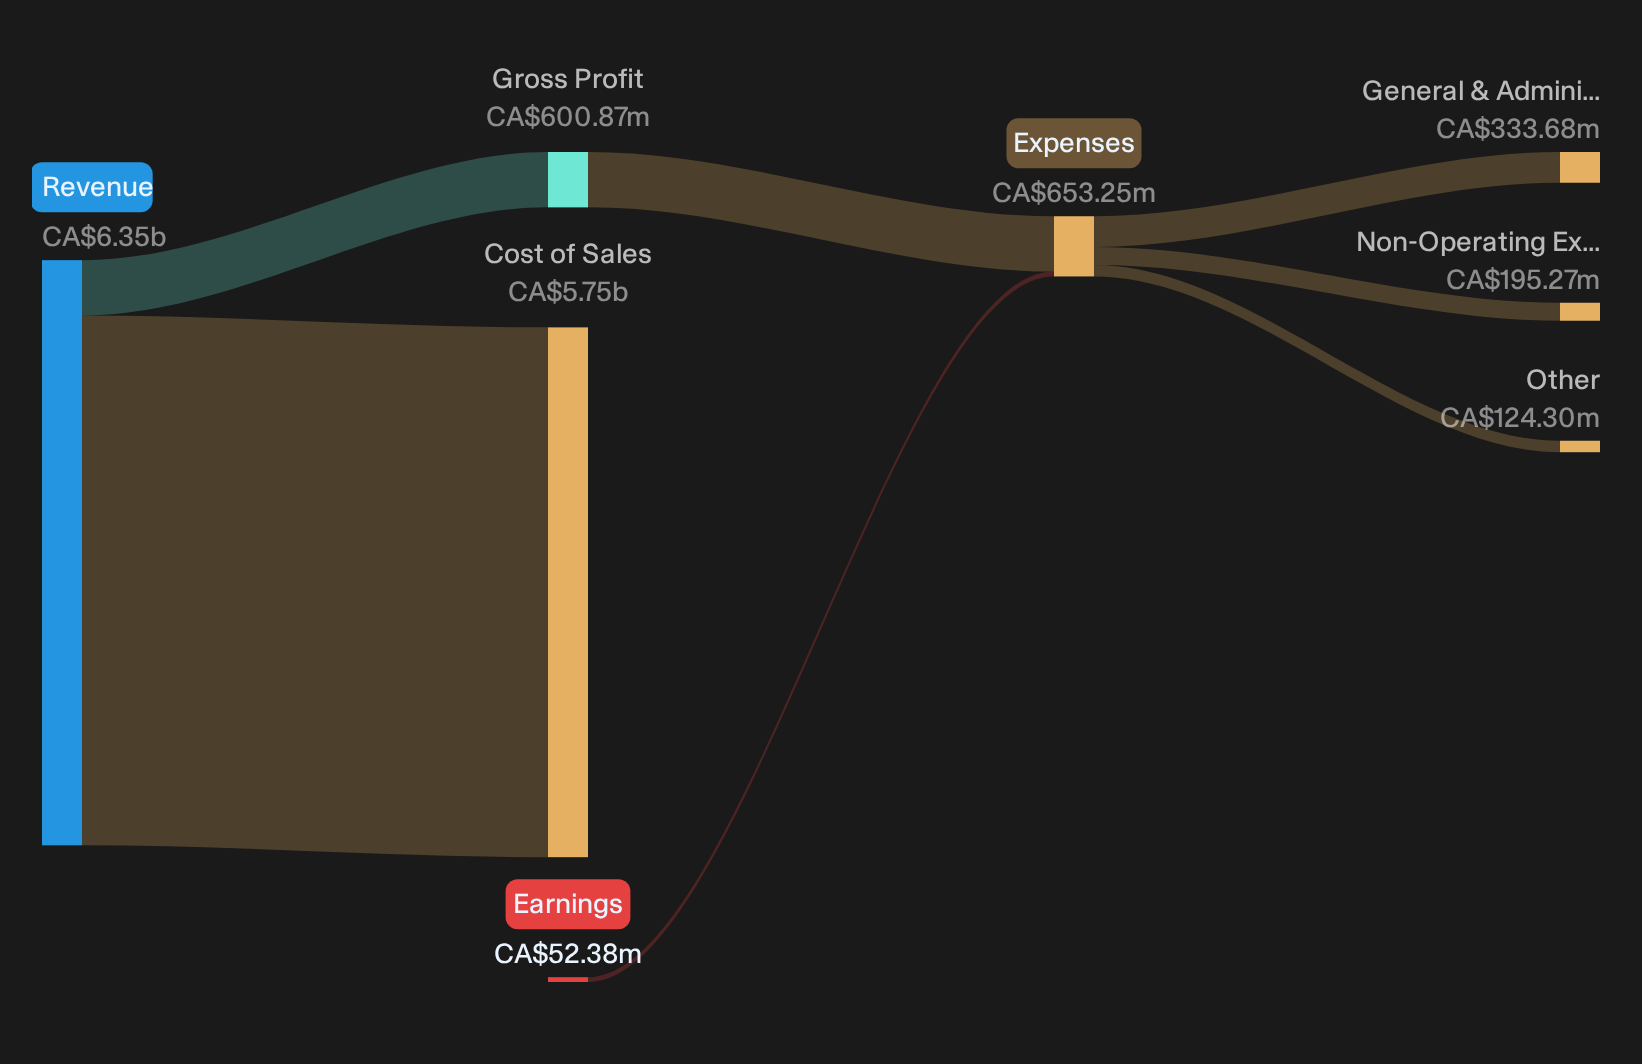
Aecon backlog story meets real execution milestones
Aecon’s bullish pitch hangs on backlog depth turning into steadier work in power and nuclear, not just raw volume.
"Record reported backlog of $10.7b and $9.5b of new awards in 2025, heavily tied to power generation, nuclear, utilities and mass transit, gives multi year visibility on activity levels that can support revenue and earnings durability."
Q3 backlog of $14.6b, up sharply quarter on quarter, shows that pipeline has expanded rather than faded. About 81% is in collaborative or variable price contracts, which lines up with the aim for durability instead of risky fixed price exposure and is already helping construction EBITDA margins improve.
Aecon execution risk thesis vs current contract mix
Bears focus on whether a heavier diet of complex programs and legacy work will choke off margin repair at Aecon.
"Aecon is still working through legacy fixed price and Western Civil contracts that reduced 2025 Adjusted EBITDA by $94 million and are expected to remain a drag until commercial close out, so any additional issues on these or similar contracts could cap the margin improvement that bullish assumptions rely on, directly pressuring net margins and earnings."
Legacy projects still produced a CA$9m negative gross profit in Q3, so the drag has not disappeared. Yet construction adjusted EBITDA margin improved to 6.8%, helped by better civil and nuclear performance and a contract book now mostly on lower risk terms, which runs against the idea that old contracts fully cap recovery.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
Hunt For Quiet Earnings Power
Aecon Group reminds investors that earnings can shift quickly once backlog converts into active projects. The real opportunity is in stocks that might be undervalued before expectations change.
- Company 1 - 46% below our estimate - uses premium mall locations and an expanding online channel to reach higher spending shoppers.
- Company 2 - 21% below our estimate - adds an acquired avionics platform that deepens aftermarket exposure as aerospace programs ramp and facilities expand.
- Company 3 - 35% below our estimate - rolls smaller engineering acquisitions into long contract programs using shared digital tools and delivery hubs.
That is three of the list. See all 3 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com