


EN
Domino's Pizza (DPZ) Cuts 2026 Expansion Plans, Is The Stock Still A Bargain?
Domino's Pizza (DPZ) is back in focus after management cut store expansion plans for 2026 and trimmed same-store sales guidance, citing franchisee profitability pressures and softer consumer spending in key markets.
The recent reset in Domino's Pizza guidance comes after a tougher stretch for shareholders, with the share price down about 26% year to date and the 1-year total shareholder return declining nearly 20%. At the same time, the shorter term 30-day share price return of 4.7% hints at stabilising sentiment as investors weigh slower expansion against ongoing market share gains and legal overhangs.
Capture how Domino's Pizza fits into a tougher consumer backdrop by lining it up against 29 high quality undervalued stocks, focusing on companies that combine resilient cash generation with balance sheets built to handle slower growth.Domino's Pizza now trades below the average analyst target after a sharp reset in expectations. Is that discount a cushion for patient investors or a warning that the market sees more trouble ahead?
Most Popular Narrative: 12% Undervalued
Domino's Pizza last closed at $313.71, while the most followed narrative pegs fair value closer to $356.48. This frames the current discount as a central part of the story rather than a side detail.
The full national rollout on DoorDash and last year's Uber Eats integration remains a live driver, with Domino's Pizza now the top pizza brand on both platforms and management indicating that around 50% of these orders are incremental, which points to additional delivery revenue and franchise royalty growth that is not yet fully reflected in earnings.
See why 37 investors see Domino's Pizza as 12% undervalued.
Result: Fair Value of $356.48 (UNDERVALUED)
Still, the narrative breaks quickly if U.S. same store sales remain stuck near flat, and franchisee profitability continues to pressure new store openings and royalty growth.
Find out about the key risks to this Domino's Pizza narrative.
Another View: Domino's Pizza Through Cash Flows
The popular fair value story around Domino's Pizza leans on analyst targets and earnings multiples. A different lens comes from the SWS DCF model, which estimates future cash flow value at $287.67, below the current $313.71 share price. That flags Domino's as overvalued on this framework and raises a simple question for you: Which signal matters more, the narrative discount or the cash flow drag?
Look into how the SWS DCF model arrives at its fair value.
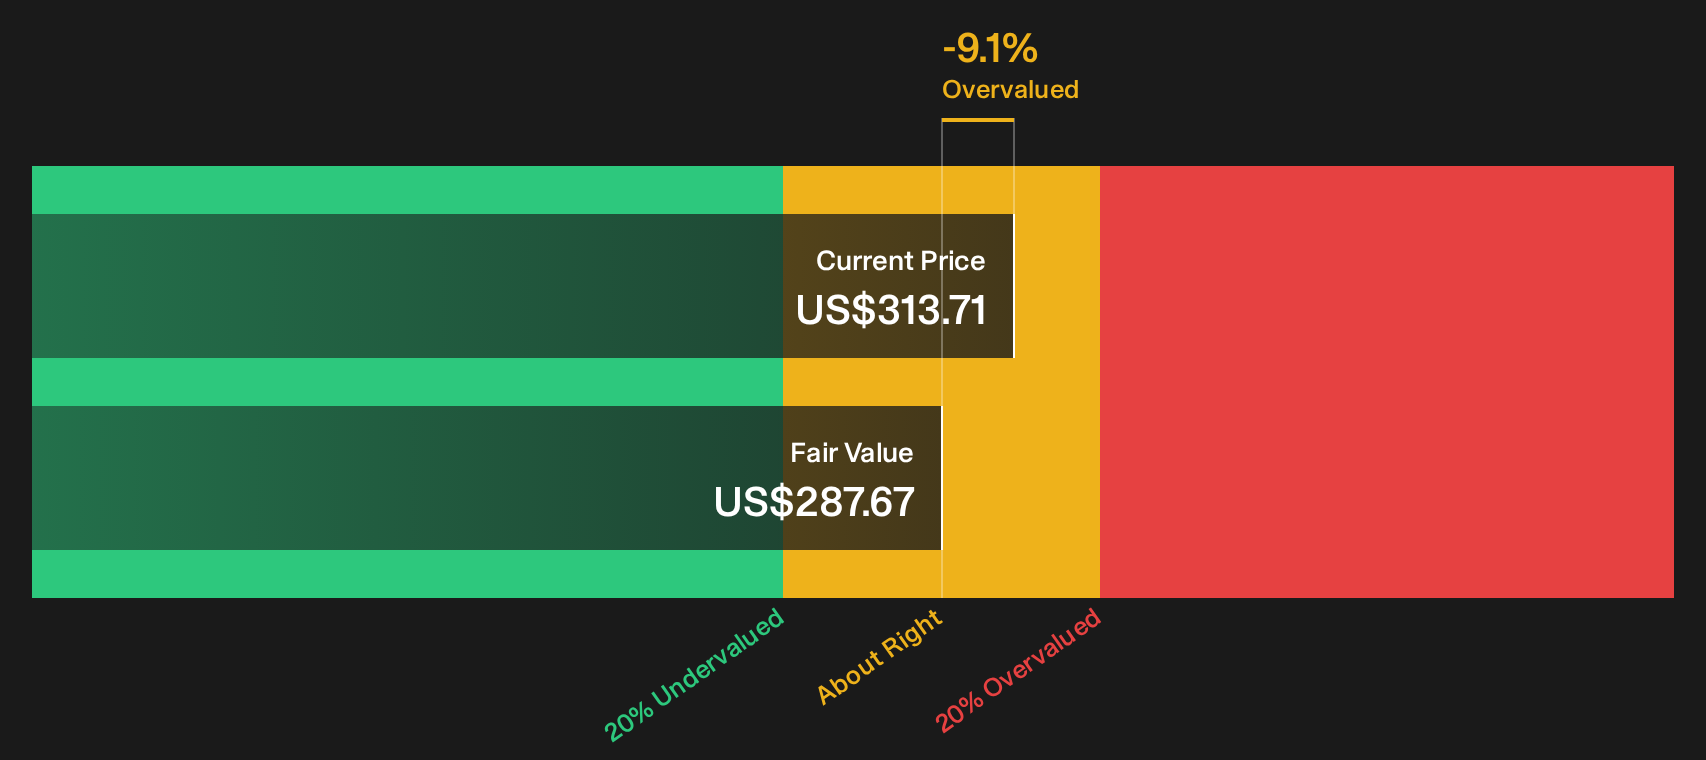
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Domino's Pizza for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Domino's Pizza is clearly split, with some investors focused on pressure points and others on potential upside drivers. Move quickly, review the numbers, and form your own stance using the full breakdown of 5 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Domino's Pizza?
If the split views on Domino's Pizza have you thinking harder about where to put fresh capital, broaden your watchlist with a few targeted stock ideas.
- Target steadier potential outcomes by reviewing companies screened as having 30 resilient stocks with low risk scores that may suit investors who prefer calmer portfolio moves over sharp swings.
- Hunt for strong balance sheets by checking the list of solid balance sheet and fundamentals (25 results) so you are not relying solely on optimistic headlines or momentum alone.
- Spot opportunities the crowd might be missing by scanning 18 high quality undiscovered gems, before attention shifts and the rest of the market catches up.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com