


EN
Tenet Healthcare (THC) Q3 Earnings Lean On Margin Gains And One Offs
Tenet Healthcare stock barely flinched after Q3 2026 earnings, closing up 0.9% around US$273. That is a muted move for a hospital and ambulatory care operator that just posted adjusted earnings per share of US$6.64 and lifted its full year adjusted EBITDA outlook to as much as US$5.2b.
Short term traders see a quiet tape. Long term holders see a business leaning hard on margin strength and cash generation while also relying on sizeable one off benefits that will not repeat forever, a mix that will matter far more than today’s 1 day gain.
Like the margin story at Tenet Healthcare but uneasy about those one off benefits that will not stick around forever? Compare this setup against a list of solid balance sheet and fundamentals stocks (25 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$5,631m vs. US$5,289m (up about 6.5%)
- Net Income, excl. extra items (Q3 2026 vs. Q3 2025): US$1,000m vs. US$342m (up very strongly)
- Basic EPS (Q3 2026 vs. Q3 2025): US$12.48 vs. US$3.89 (up more than 3x)
- Net Profit Margin, trailing 12 months vs. prior year: 13.1% vs. 6.5% (much stronger profitability, helped by a US$938m one off gain)
Prefer clean charts instead of slogging through dense earnings tables and footnotes? See Tenet Healthcare’s full financial picture with a visual breakdown of its valuation in the company report for Tenet Healthcare.
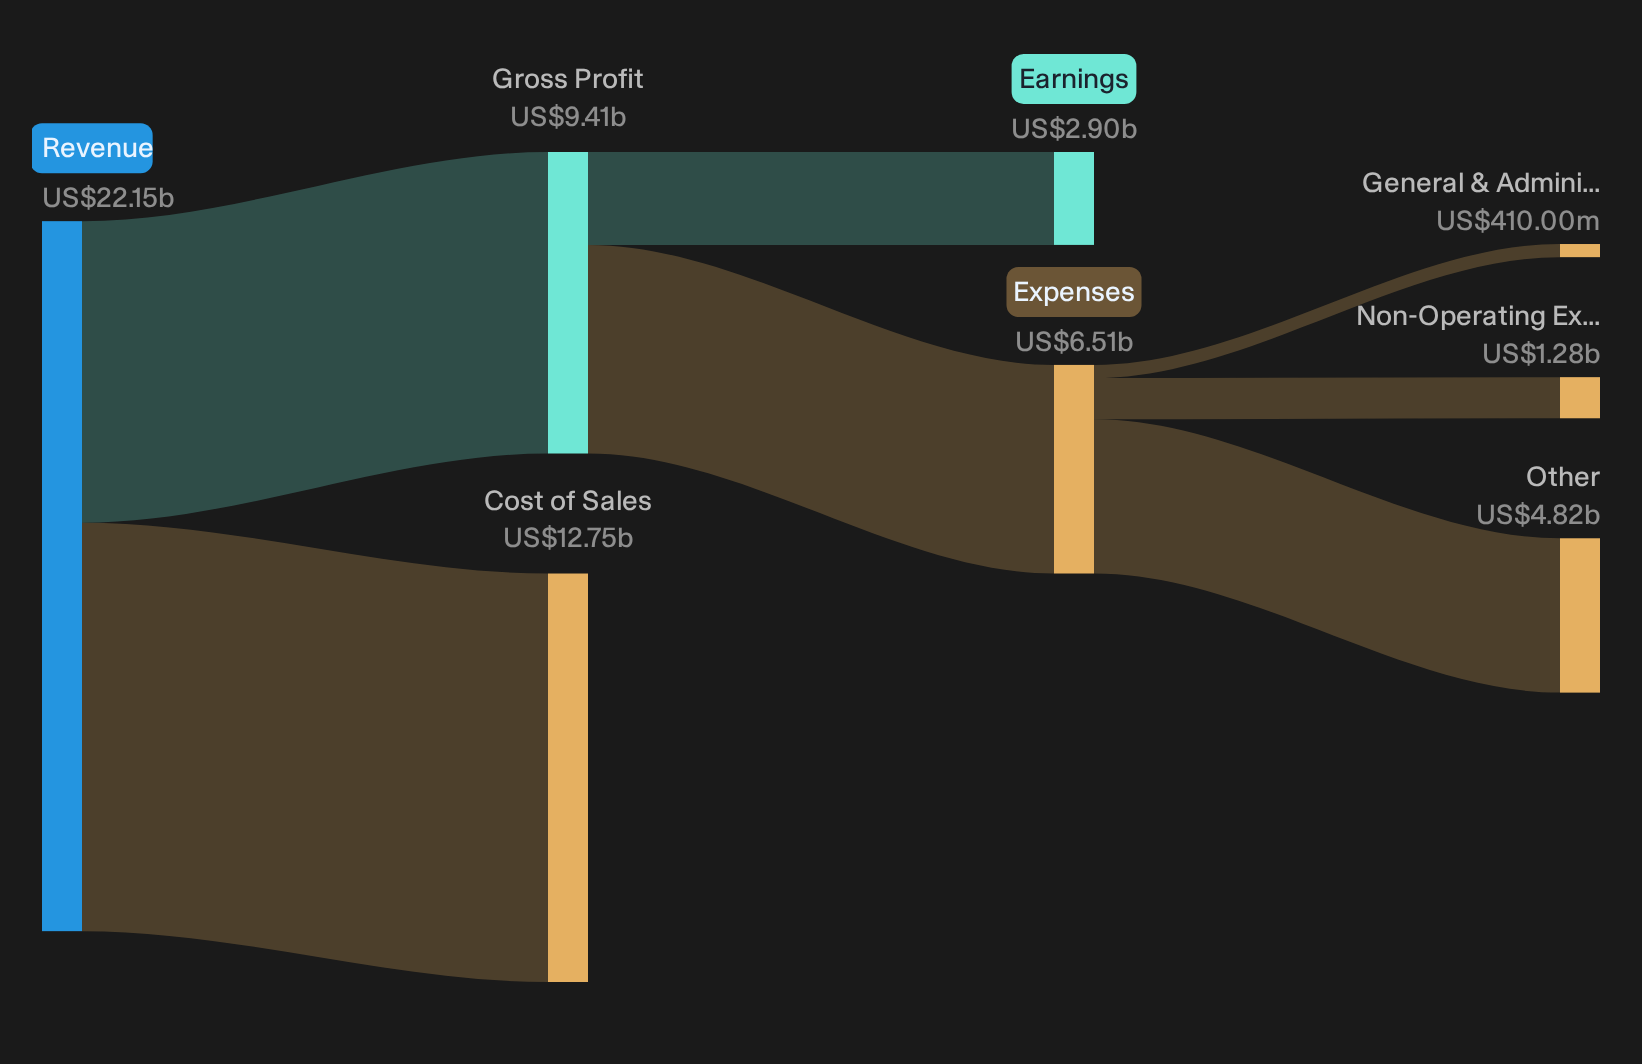
Evaluating Tenet Healthcare’s High-Acuity Earnings Story
"Tenet Healthcare is committing roughly US$700 to US$800 million of 2026 capex largely to hospitals, with recent builds and expansions in areas like cardiovascular, neurosurgery, trauma and NICU. These can support a mix shift toward higher acuity services that influence revenue per admission and hospital EBITDA margins."
Tenet Healthcare is starting to put that ambition into the income statement. Same hospital adjusted admissions grew, while higher acuity mix and tighter length of stay management helped lift hospital profitability. In addition, USPI is showing strong same facility revenue growth, with net revenue per case up 6.1% and double digit joint replacement volume gains. Those are tangible milestones for the high acuity, surgery led earnings thesis, even if part of the margin strength is temporarily amplified by Conifer related benefits.
One Narrative disagrees with today's price. → See where this Narrative says Tenet Healthcare should trade.
Tenet Healthcare: Bears Still Waiting For Cost Stumbles
The cautious view says Tenet Healthcare’s cost and tech program is running out of easy wins and that incremental savings will fade just as payer mix risk bites.
"Management’s three part cost program, with traditional productivity, clinical efficiencies and technology or AI initiatives, has already reduced contract labor to about 2% of salaries, wages and benefits and lowered certain analytics costs. This signals that the easiest savings are likely realized and that any slowdown in incremental efficiency gains could limit further adjusted EBITDA margin expansion."
This quarter does not fully validate that concern. Core adjusted EBITDA rose and hospital margins expanded, yet about US$450m of 2026 EBITDA still comes from non repeating Conifer transition benefits. Bears have not seen a clear cost miss, but they can argue that genuine productivity milestones remain unproven once that one off tailwind rolls off.
Hunt Quiet Dislocations Now
Tenet Healthcare just reported results that highlight how a strong earnings story can still leave investors debating the quality of the run rate. The real opportunity could be spotting stocks that could be undervalued before expectations catch up.
- Company 1 - 19% below our estimate - expands a teahouse network into new markets while balancing same store activity with franchise and company store economics.
- Company 2 - 34% below our estimate - converts long duration optical and solar supply agreements and customer prepayments into higher volume tied to data and energy infrastructure projects.
- Company 3 - 20% below our estimate - adds payment volume as more customers use its accounts, cards and platform integrations with banks for cross border transfers and deposits.
Three companies from the same screener. Open every one of the 29 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com