


EN
SGH (ASX:SGH) Could Be 15% Undervalued As WesTrac Rebuild Work Lifts Cash Flow
Event driven focus on SGH’s cash flow story
Fresh analysis around SGH (ASX:SGH) has zeroed in on its Discounted Cash Flow valuation, linking projected free cash flow strength to rising service intensity and record rebuild work at WesTrac.
Recent trading has been a bit of a reset for SGH. The A$40.76 share price sits after a 1 month share price return of 8.64%, even though the share price has fallen 7.85% over 3 months and the year to date share price return is down 12.96%. That pullback contrasts with a 3 year total shareholder return of 45.19% and a 5 year total shareholder return of 99.11%. This helps explain why fresh attention is going back to whether the current price still lines up with the DCF backed cash flow story.
Scan other cash flow driven opportunities alongside SGH with a curated set of 1 high quality undervalued stocks that combine solid balance sheets with proven free cash generation.
SGH has almost doubled investors over five years, yet the share price has just reset and the DCF work still points to a discount. Is most of the cash flow upside ahead or already reflected?
Most Popular Narrative: 15% Undervalued
On the most followed view of SGH, a fair value of A$48.02 sits above the A$40.76 last close, so the current quote is framed as a discount built on cash flow, services intensity and capital discipline rather than pure sentiment.
SGH’s capital allocation model, with leverage reduced to about 1.8x EBITDA, a planned A$500m on market buyback and continued investment in high cash generative projects, is described as being positioned to lift earnings per share and support future returns on equity if operating cash flow remains strong.
See why 15 investors see SGH as 15% undervalued.
Result: Fair Value of A$48.02 (UNDERVALUED)
Still, if Australian construction or mining activity softens, or competitive pricing at Coates persists, the SGH cash flow narrative could come under pressure.
Find out about the key risks to this SGH narrative.
Another View on SGH’s valuation
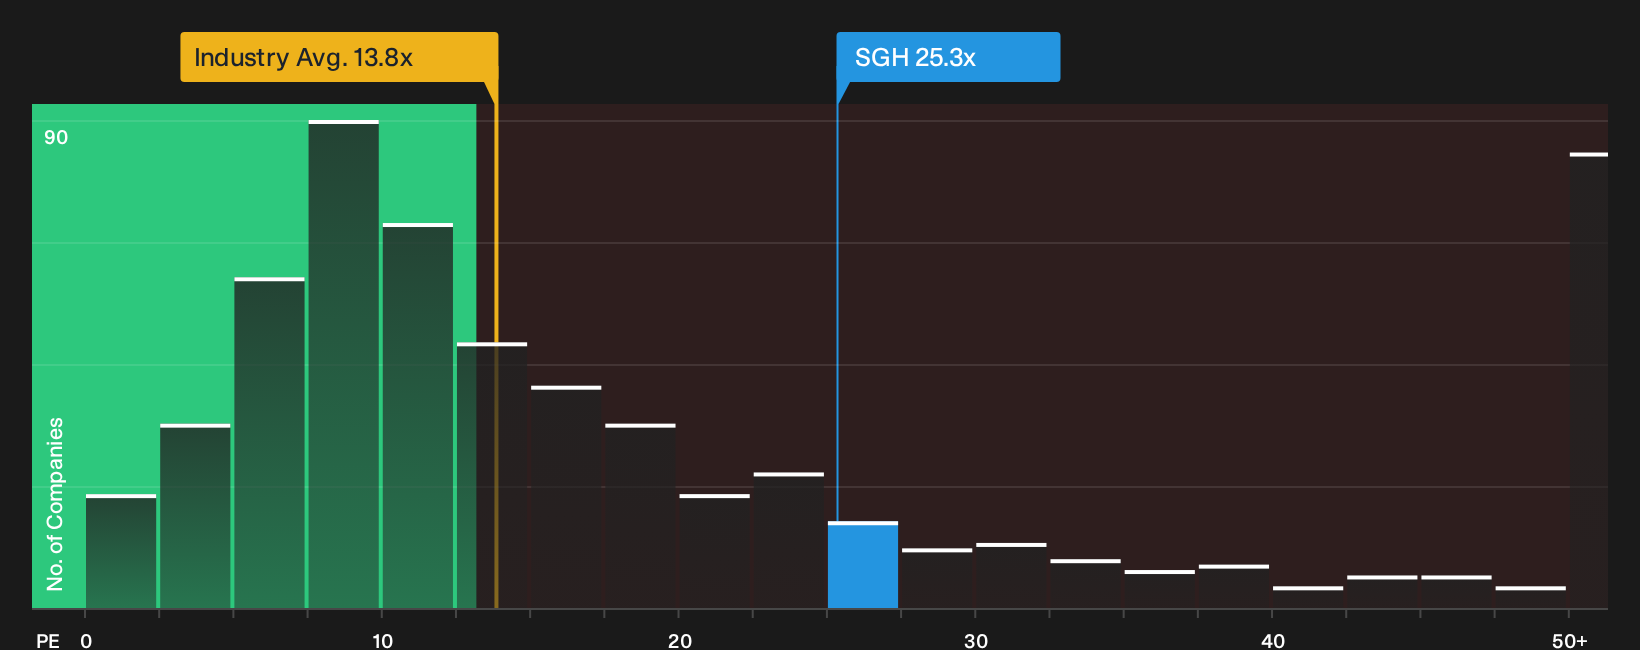
The cash flow story points to value, but SGH’s A$40.76 share price also equates to a P/E of 25.3x. That is richer than the Global Trade Distributors group at 13.8x and above peers at 20.4x, even though the fair ratio sits higher again at 29.7x.
This mix, where the headline multiple looks expensive against the sector yet below the fair ratio, leaves you weighing upside against the risk that sentiment cools before earnings catch up.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on SGH’s valuation story so far. If you want to move fast and base your stance on the underlying numbers, weigh up the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond SGH?
SGH gives you one angle on cash flow and valuation. To really sharpen your watchlist, broaden your search to other targeted opportunities built from the same data driven approach.
- Target resilient, lower volatility opportunities by scanning a 6 resilient stocks with low risk scores that filters for businesses with stronger risk profiles and more predictable fundamentals.
- Hunt for mispriced quality by reviewing a curated 15 high quality undiscovered gems that highlights companies with solid fundamentals that many investors still overlook.
- Strengthen the defensive side of your portfolio by focusing on a 4 dividend fortresses that screens for higher yielding payers with more robust financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com