


EN
Phibro Animal Health (PAHC) Stock Looks Fully Priced At Current Levels
Phibro Animal Health has delivered a powerful 3 year share price run, and that kind of climb naturally puts fresh attention on whether the current valuation is still supported by its earnings. With the stock now at US$38.86, the question is how much of the business's profit power is already reflected in that price.
- The share price has gained 235.8% over the past 3 years, which makes it important to test how firmly those returns are anchored in the company’s earnings profile.
- The business model depends on converting animal health product sales into steady profits, so the durability of those earnings can shape how investors think about what they are willing to pay for the stock.
- Your read on Phibro Animal Health is one view; the desks covering it have another. See what analysts think Phibro Animal Health's shares could be worth.
The issue now is whether Phibro Animal Health's current share price is appropriately aligned with its earnings when measured against the Fair Ratio benchmark.
To put Phibro Animal Health’s 3 year share price run in context, it can help to compare it with other businesses that pass a similar quality filter such as the 30 high quality undervalued stocks
Where Does Phibro Animal Health Sit on Earnings?
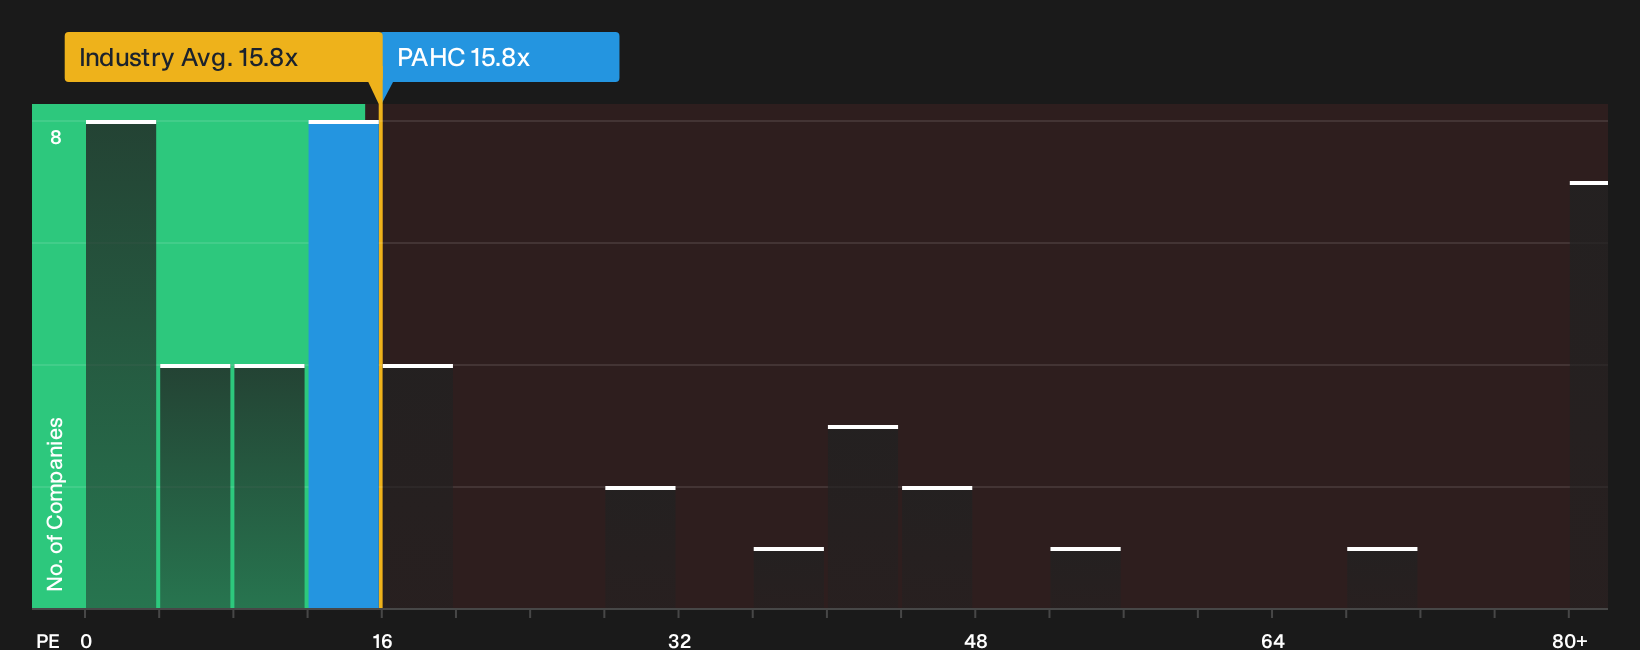
The P/E ratio is a useful fit for Phibro Animal Health because investors often look at this business through the lens of its earnings power. On that yardstick, the stock trades on a P/E of 15.8x, which is very close to the broader pharmaceuticals sector average of 15.8x and well below the peer group average of 32.9x. That suggests the market is pricing Phibro Animal Health’s profit stream more like a typical industry player than a high premium peer, despite the recent share price run.
The Fair Ratio framework, which adjusts for factors such as profitability, growth profile, size and risk, points to a level that is broadly aligned with where the shares trade today. So the current 15.8x earnings multiple does not flag Phibro Animal Health as clearly overvalued or clearly undervalued on this model, and the question becomes whether you think the underlying earnings quality and risks justify paying roughly this kind of sector level price tag. Explore the numbers behind Phibro Animal Health's P/E valuation.
The Phibro Animal Health Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St pick up where this valuation puzzle for Phibro Animal Health's P/E leaves off by spelling out what kind of future growth, margins and earnings path would need to unfold for the current share price to look meaningfully high or low. Each scenario ties a fair value estimate to a clear storyline about Phibro Animal Health's possible catalysts and risks, so you can track over time which version appears to be gaining traction.
Community views on Phibro Animal Health split between those who see more upside left in the transformation story and those who think a lot is already priced in.
Bull case: 17% undervalued
"The planned closure of the Chicago Heights manufacturing facility, with anticipated annual adjusted EBITDA savings of US$15 million to US$20 million from fiscal 2028 and a smaller benefit already expected in fiscal 2027, points to structural margin improvement that is not fully reflected in current earnings-based valuation metrics..."
Discover why this Narrative puts Phibro Animal Health at 17% undervalued.
Bear case: 11% overvalued
"Although Phibro Animal Health reports strong Animal Health segment growth, the sharp step down from about US$27 million of above average margin virginiamycin sales in Brazil in FY2026 to only minimal revenue assumed for FY2027 could leave a persistent gap that mix shift and vaccines may not fully cover..."
Explore why this Narrative puts Phibro Animal Health at 11% overvalued.
The share price is only the starting point for Phibro Animal Health
Valuation tells you what the market is paying today, while analyst projections sketch out where earnings and cash flows might head over the next few years. Explore where analysts expect Phibro Animal Health to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com