


EN
BorgWarner (BWA) Stock Price Slides Despite Firm Q3 Earnings
The market hit BorgWarner first. The stock dropped about 3% to US$51.63 on Friday, extending a tough run over the past month and quarter. That is the short term reaction to Q3 2026 earnings.
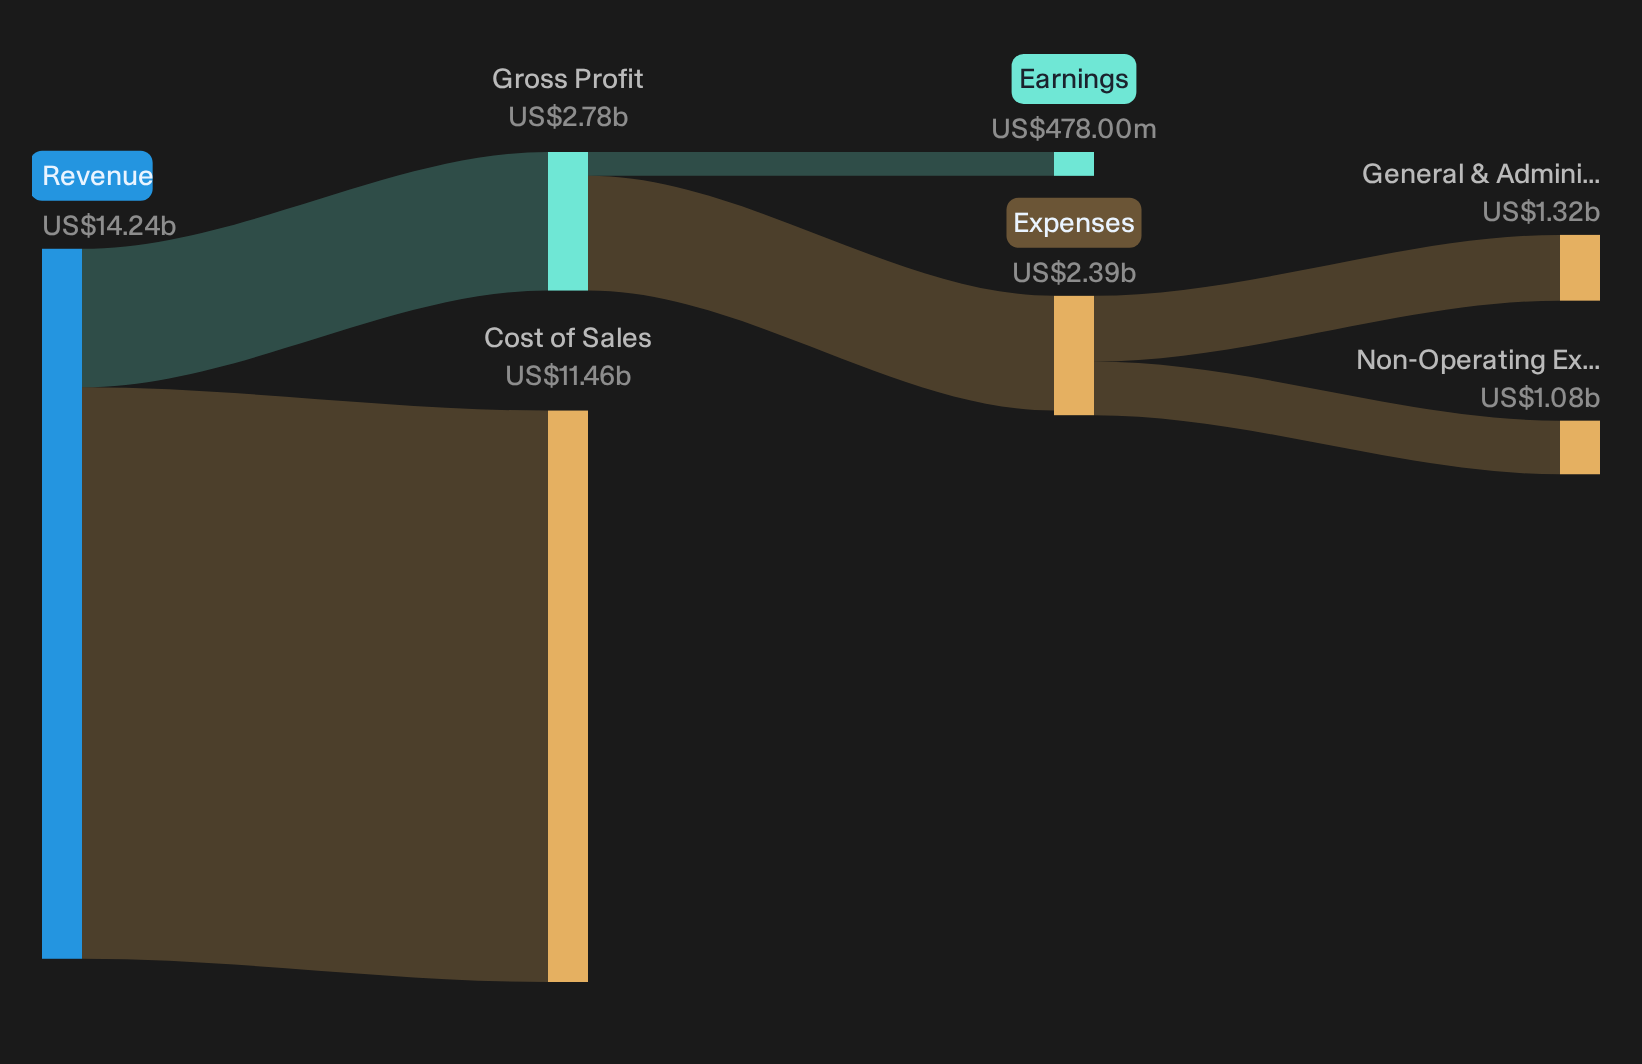
The headline result tells a different story. BorgWarner delivered roughly US$3.5b in sales with an adjusted operating margin of 10.9% and management lifted full year adjusted EPS guidance to a range of US$5.20 to US$5.35. Short term traders focused on the price slide. Longer term investors are more likely to focus on margins holding firm while the business invests in its electric and industrial future.
Love BorgWarner’s solid Q3 margins, but wary of buying into a stock that just slid on the headline reaction. Use the list of solid balance sheet and fundamentals stocks (25 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$3,487m vs. US$3,591m (declined 2.9%)
- Net Income, Excl. Extra Items (Q3 2026 vs. Q3 2025): US$221m vs. US$158m (increased 39.9%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$1.10 vs. US$0.74 (rose 48.4%)
- Adjusted Operating Margin (Q3 2026 vs. Q3 2025): 10.9% vs. 10.7% (expanded 0.2 percentage points)
BorgWarner beat on margins and raised EPS, but flagged new industrial risks. Ask Charlie what BorgWarner isn’t saying about its 2027 industrial bets.
BorgWarner’s Non Auto Shift Starts To Show Up
The bullish premise says BorgWarner can tilt its earnings mix toward non auto power and electrification rather than just talking about it.
"Record new product awards across both Foundational and eProduct portfolios, including hybrid and BEV components like iDMs, battery management systems and eXD solutions, indicate a sizeable pipeline that is expected to support future revenue and contribute to adjusted EPS growth as programs launch."
Q3 gives early, measurable proof. Light vehicle eProduct sales reached US$630m and rose 33% year on year, with Europe driving most of the lift. Awards for high voltage inverters, integrated drive modules and Chinese eMotors, plus the Wolfspeed silicon carbide deal, extend that pipeline. TurboCell and broader industrial revenue are still pre ramp, yet the auto side of the shift is clearly moving from order book to income statement.
One Narrative disagrees with today's price. → See where this Narrative says BorgWarner should trade.
BorgWarner Bear Case: Execution Risks Still Unproven
Bears argue BorgWarner is stretching itself on spending for new projects and that cash generation could crack under the strain.
"The decision to ramp capital spending to around 4.5% of sales to support turbine generators and multiple new vehicle launches raises execution risk. Any cost overruns or slower volume ramp could pressure free cash flow from the guided US$900 million to US$1.1b range and restrain future margin expansion."
Q3 shows neither a clear break nor clear stress. Adjusted operating margin held at 10.9%, guidance for 10.7% to 10.9% and US$900m to US$1.1b free cash flow is intact. However, turbine and broader industrial revenue remain largely future dated, so the capex ramp is not fully tested by current earnings.
Hunt For Mispriced Earnings Power
BorgWarner just showed how a busy quarter and a sliding share price can tell two different stories. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 38% below our estimate - grows a once niche drink into a mainstream staple as retailers expand branded and private label shelf space.
- Company 2 - 31% below our estimate - anchors critical digital infrastructure where data is processed, connected, and secured as enterprises scale new workloads.
- Company 3 - 41% below our estimate - rents composite access mats that large utilities rely on for long duration grid and pipeline projects.
That is three of the list. See every one of the 30 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com