


EN
West Fraser Timber (TSX:WFG) Stock Can Q3 Results Ease Margin Pressure?
West Fraser Timber just posted Q3 2026 earnings showing another quarter in the red, yet the stock closed today at CA$93.70 after drifting lower over the past month. The headline is simple: the company generated US$1.363b of revenue but still reported a net loss of US$80m. That mix of solid sales and ongoing losses has traders asking whether the recent share price weakness already captured the bad news or whether this is the start of a harsher rethink on profitability.
Love West Fraser Timber’s scale and revenue base, but concerned that recurring losses might signal deeper profitability issues. Compare this setup with companies that pair solid balance sheets and resilient cash generation in our list of solid balance sheet and fundamentals stocks (6 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$1,363 million vs. US$1,307 million (modest year on year increase in sales)
- Net Loss (Q3 2026 vs. Q3 2025): loss of US$80 million vs. loss of US$204 million (year on year narrowing of losses)
- Basic EPS (Q3 2026 vs. Q3 2025): loss of US$1.02 per share vs. loss of US$2.59 per share (per share loss reduced year on year)
- Adjusted EBITDA Margin (Q3 2026 vs. Q2 2026): US$38 million or 3% of sales vs. US$59 million or 4% of sales (quarter on quarter margin compression)
Prefer clear charts instead of another page of detailed earnings tables and footnotes? See West Fraser Timber’s full financial picture, including how its valuation compares with those latest losses, in the company report for West Fraser Timber.
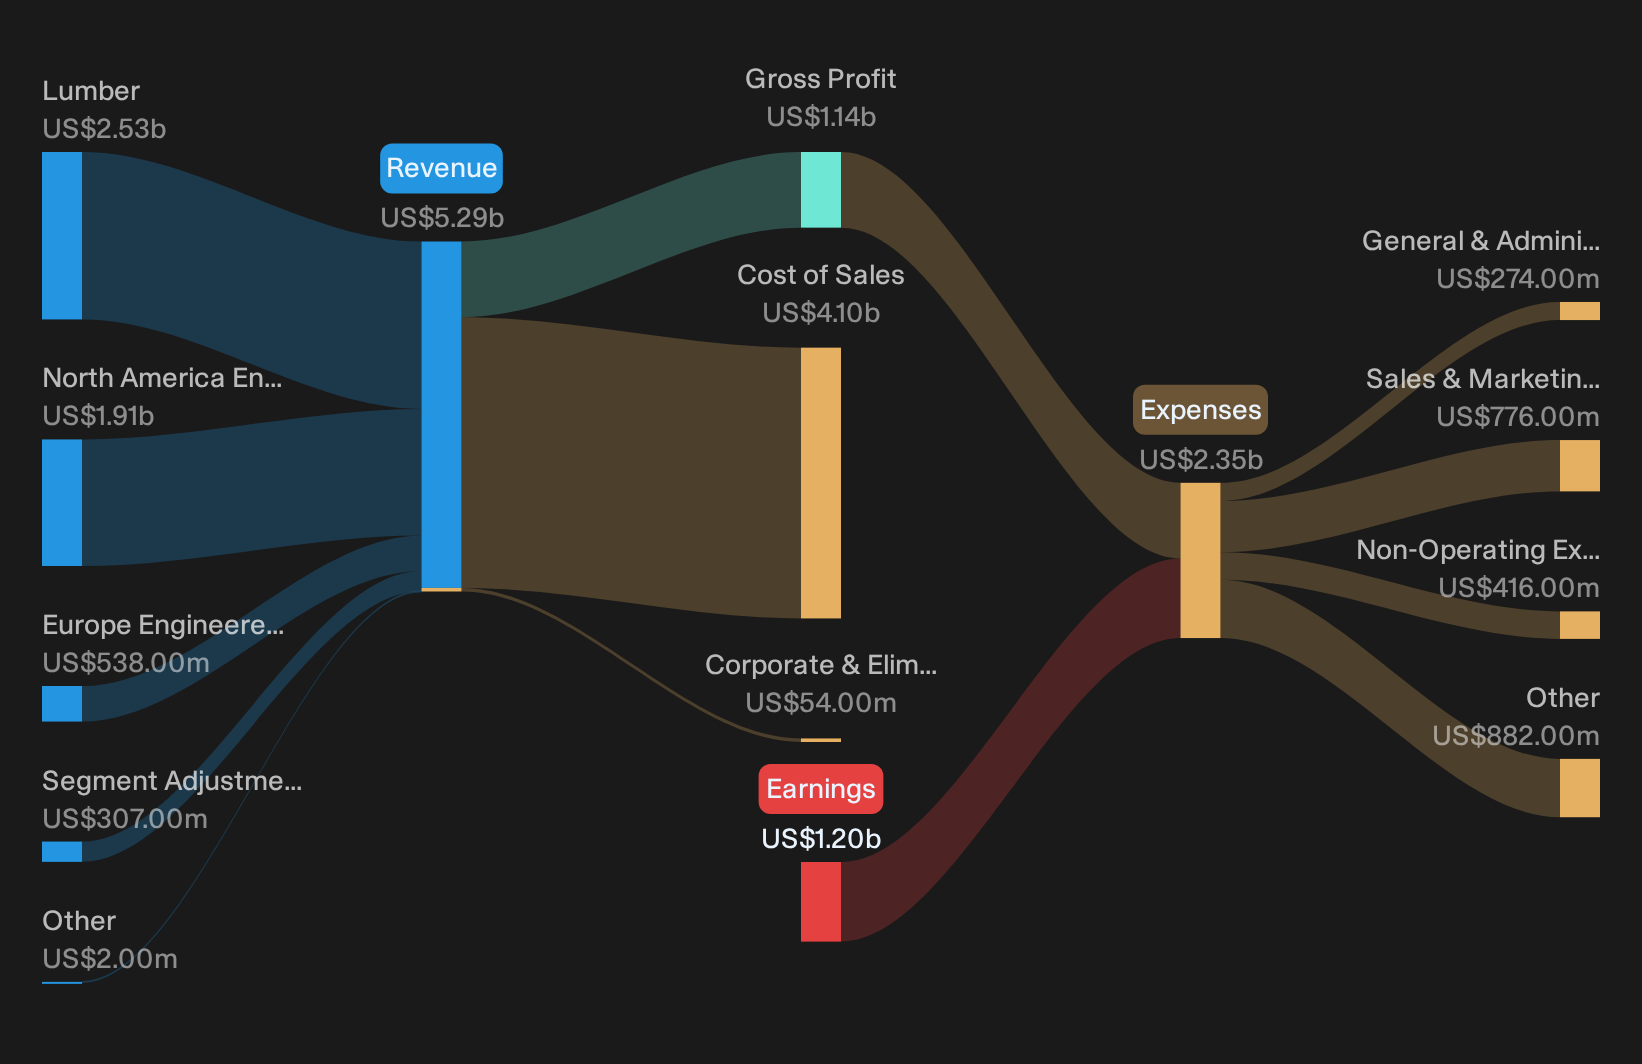
West Fraser bull case runs into margin reality
Supporters argue West Fraser Timber has built the right engine for the upswing once demand improves.
"The company's continued investment in mill modernization, operational technology, and flexibility in production helps lower its cost structure, positioning West Fraser to expand margins and boost earnings as demand recovers and cyclical markets improve."
Q3 results show that ambition remains a work in progress. Adjusted EBITDA margin sits at 3%, down from Q2, and the North American engineered wood products unit posted an adjusted EBITDA loss. Curtailments at Huguley and Leola signal that even with prior upgrades, some assets still struggle to earn their keep at current pricing.
West Fraser bear case tests earnings stability
The skeptical view is that weak housing, trade friction and higher input costs could keep West Fraser Timber stuck in a low profit zone.
"Lingering macroeconomic and trade challenges, weak housing demand, and ongoing cost pressures threaten West Fraser Timber's earnings stability, cash flow strength, and margin recovery prospects."
Q3 numbers lean toward that caution. The group stayed loss making despite US$1.363b of revenue. OSB pricing softness and higher resin and diesel costs pushed North American engineered wood products into the red. Indefinite curtailments and an expected US$200 to 220m impairment in Q4 highlight that pressure on volumes, tariffs and costs is already forcing hard restructuring decisions.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
Hunt Quiet Disconnects In Plain Sight
West Fraser Timber highlights how revenue strength can differ from reported profitability. The real opportunity could sit in stocks that could be undervalued before the gap closes.
- Company 1 - 35% below our estimate - uses index inclusion, contract wins and acquisitions to deepen recurring infrastructure and water program work.
- Company 2 - 46% below our estimate - targets higher income shoppers with premium mall expansion and a sharpened omnichannel setup supporting full price sell through.
- Company 3 - 21% below our estimate - turns a swelling aerospace and defense backlog, new facility and aftermarket acquisition into higher margin electronic content.
That is three of the list. See the full list of 3 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com