


EN
FMC (FMC) Stock Rebounds After Q3 Earnings Expose Pricing Reset
FMC just dropped its Q3 2026 report and the market loved it on first read. The stock jumped about 30% in Friday trading to US$6.20, a sharp move for a chemicals producer that has been treated as a troubled turnaround story. The headline, however, is not growth. It is a painful hit to profitability, with adjusted EBITDA pulled deeply into loss territory by roughly US$672 million of commercial actions that slashed channel pricing and inventory values.
Shareholders see a rebound on the screen. The income statement shows a company paying upfront for that reset with very heavy losses.
Impressed by FMC’s sharp share price reaction but uneasy about a turnaround that currently rests on deep profitability hits and heavy commercial resets? If you want a reference list of companies where balance sheets and fundamentals are already doing more of the heavy lifting, check out the list of solid balance sheet and fundamentals stocks (25 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$105.9 million vs. US$542.2 million (fell 80.5%)
- Net Income/Loss, excluding extra items (Q3 2026 vs. Q3 2025): loss of US$2,030.1 million vs. loss of US$546.1 million (loss deepened 271.7%)
- Basic EPS (Q3 2026 vs. Q3 2025): loss of US$15.26 per share vs. loss of US$4.36 per share (loss per share widened 250.0%)
- Total Revenue, trailing 12 months to Q3 2026 vs. trailing 12 months to Q3 2025: US$2,814.9 million vs. US$4,131.6 million (fell 31.9%)
FMC took a huge one-time hit to reset channel pricing. Ask Charlie what makes FMC confident about a 2027 inflection.
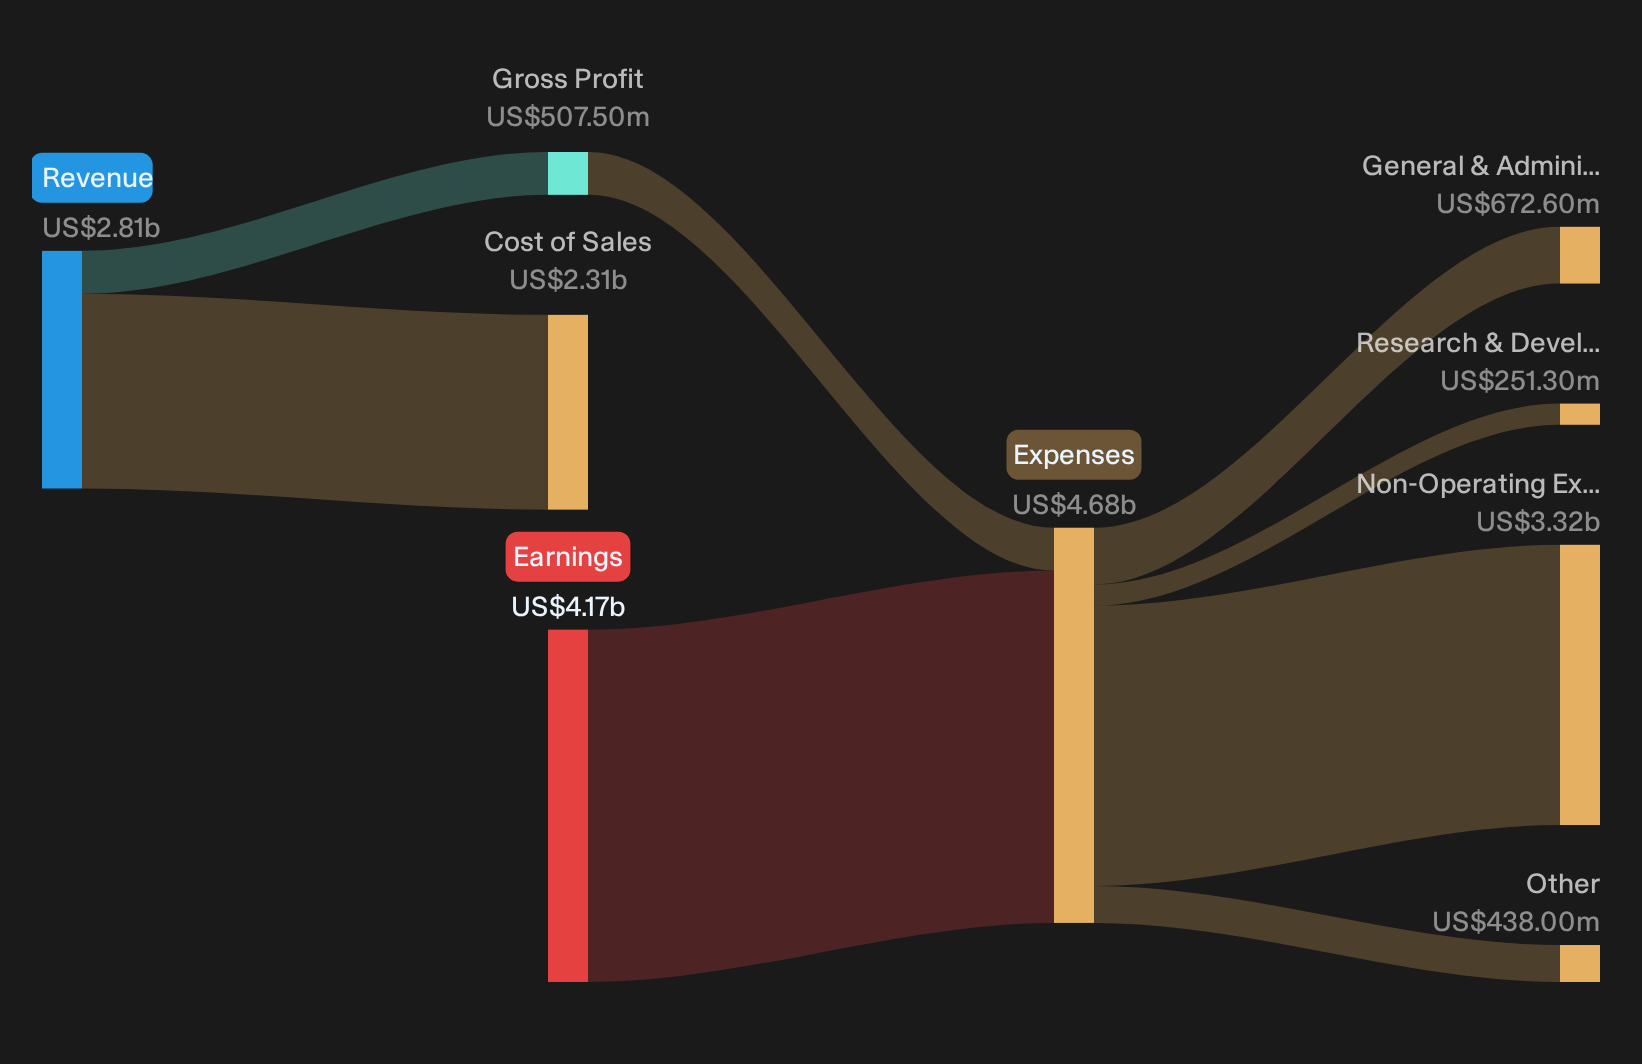
FMC Deleveraging Ambition Meets Profit Hit Reality
Bullish FMC holders frame today’s pain as the entry fee for a cleaner balance sheet and a richer product mix over time.
"Bullish analysts expect FMC to use asset sales, licensing deals, restructuring and a larger product pipeline to restore growth, improve cash generation and reduce leverage over the next few years."
The quarter only partially lines up with that script. Management did pull the restructuring lever, with heavy commercial and pricing actions plus about US$180 million of 2026 restructuring cash, and free cash flow before those charges hovered around breakeven. Net debt is guided to roughly US$3.1b after planned India and Delaware transactions. The balance sheet reduction leg of the thesis still needs clearer, executed milestones.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
FMC Bear Case: Pricing Pain Now On The Scorecard
Bearish views hinge on FMC never regaining real pricing power in its legacy insecticides and herbicides.
"Although FMC has lowered manufacturing costs for Rynaxypyr and is pursuing higher value mixtures, the rapid expansion of quality generics and the shift of partner volumes toward lower cost supply leaves little room for price discipline."
The Q3 reset leans toward that concern. Roughly US$672 million of commercial actions and high single digit price declines embedded in Q4 guidance show pricing concessions already hitting earnings. Underlying Q3 adjusted EBITDA of US$113 million, well below earlier expectations, also signals that even excluding one off actions, the portfolio is not yet shaking off generic pressure.
Hunt For Quieter Fundamental Setups
FMC just showed how quickly sentiment can shift when earnings and expectations meet. The real opportunity is finding stocks that could be undervalued before the market quietly closes that gap.
- Company 1 - 31% below our estimate - builds connectivity hardware, custom chips and embedded software that anchor expanding digital infrastructure workloads.
- Company 2 - 41% below our estimate - rents modular composite mat networks that keep long-duration energy and utility projects moving over difficult terrain.
- Company 3 - 30% below our estimate - embeds paid AI assistants into productivity, coding and security tools used in day-to-day enterprise workflows.
Those are three of them. See every one of the 30 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com