


EN
Pediatrix Medical Group (MD) Stock Climbs As Q3 Earnings Back Resilience
Pediatrix Medical Group came into Q3 2026 earnings with its stock already on a steady climb over the past month, and the latest print just added more fuel. The shares closed at US$29.81, up 2.2% on the day, as investors reacted to a headline quarter built around solid profitability and a clean balance sheet.
The real swing factor was earnings power. Basic EPS landed at US$0.59 on revenue of US$501.4m, supported by adjusted EBITDA of US$85.5m and leverage just under 1x. For a physician services group, where strain often shows up in debt and margins first, this report leaned firmly toward resilience.
If you appreciate the earnings power and low leverage at Pediatrix Medical Group but are looking for more ideas with similar balance sheet strength, take a look at our curated screener of stocks on the list of solid balance sheet and fundamentals stocks (25 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$501.4m vs. US$492.9m (up about 1.7%)
- Net Income, excl. extra items (Q3 2026 vs. Q3 2025): US$47.0m vs. US$71.7m (down about 34.5%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.59 vs. US$0.85 (declined about 30.5%)
- Adjusted EBITDA (Q3 2026 vs. Q3 2025): US$85.5m compared with a prior period that included a US$20.9m net gain on divested businesses (the current quarter reflects profitability without that gain)
Tired of scrolling through walls of Pediatrix Medical Group figures and footnotes? Get the full financial picture in a clean, visual format, including a clear view of its balance sheet strength, inside the company report for Pediatrix Medical Group.
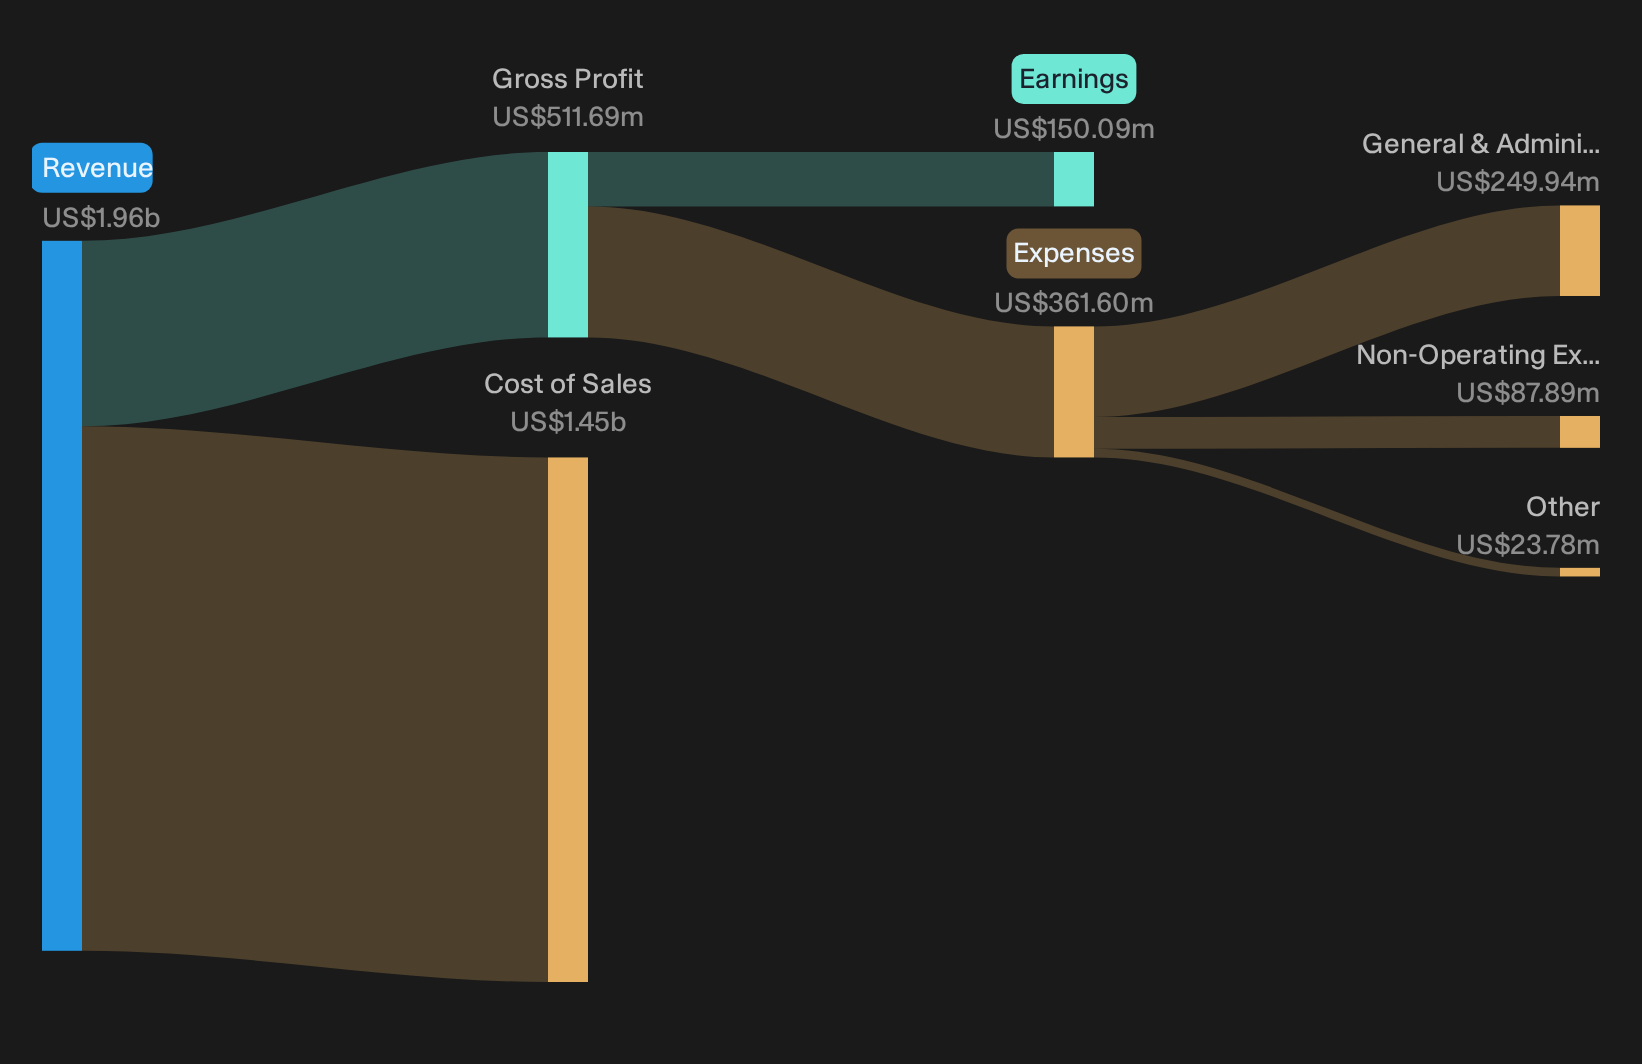
Pediatrix Earnings Resilience Thesis Meets First Real Test
The bullish story on Pediatrix Medical Group hinges on earnings holding up even if volumes stay soft. One key claim has been that disciplined pricing and capital returns can do more of the heavy lifting.
"The main thing that has to go right is that Pediatrix Medical Group continues to offset flat-to-declining NICU and patient service volumes with resilient payer mix, efficient revenue cycle management, and controlled G&A and salary costs."
Q3 shows early proof of concept. Same unit volumes were only slightly higher, and same unit pricing also contributed 30 bps, helped by payer mix and hospital fees. EBITDA guidance tightened to US$290m to US$300m with leverage under 1x, and buybacks continued. Together these data points align more with an earnings resilience script than with a volume recovery story.
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all.
Bear Case On Pricing Resets As Volume Drags Persist
Bearish analysts argue that Pediatrix Medical Group is leaning too hard on price and mix while core activity quietly erodes.
"While Pediatrix Medical Group is currently sustaining revenue growth through higher pricing supported by improved collections, payer mix and neonatal acuity, management already expects the revenue cycle tailwind to fade in the second half of 2026. This could expose flat to declining same-unit volumes and pressure both top line and net margins once pricing gains slow."
Q3 largely supports that concern. Same unit volumes only added 30 bps and revenue cycle tailwinds already reduced pricing by a little over 100 bps. EBITDA guidance tightened, yet operating cash flow fell versus last year. The bearish milestone of fading pricing with only marginal volume help is now in view.
Hunt Quiet Disconnects In Plain Sight
Pediatrix Medical Group just showed how a mixed quarter can still support a firm earnings story when balance sheet risk stays contained. The real opportunity could be finding stocks that look misaligned before everyone spots a potential disconnect.
- Company 1 - 46% below our estimate - targets rising demand for larger LED displays as smart transportation and youth sports venues refresh their visual systems.
- Company 2 - 41% below our estimate - grows recyclable mat rentals that utilities and energy projects use for faster, lower-impact worksite access.
- Company 3 - 30% below our estimate - integrates generative AI into productivity and developer tools that enterprises adopt for routine workflow and code deployment.
That is three of the list. See all 30 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com