


EN
Veralto (VLTO) After The Earnings Beat And Higher Outlook Looks Close To Fair Value
Veralto (VLTO) just cleared Q3 expectations, reporting adjusted earnings of $1.18 per share on US$1.51b in revenue, and management lifted full year EPS guidance despite earlier share underperformance.
The latest beat and higher guidance have quickly shifted sentiment around Veralto, with the 1-day share price return of 6.77% at US$111.10 capping a 30-day share price return of 17.79% and a 1-year total shareholder return of 13.22%. The 3-year total shareholder return of 59.10% points to momentum that has been building over a longer stretch.
Scan how Veralto's earnings beat compares with other potential breakouts in quality-focused industrials by running the list of solid balance sheet and fundamentals (25 results).
After a 17.79% move in a month and a price now close to analyst targets, the market has repriced Veralto fast. Do current fundamentals still suggest room on the upside, or has most of the easy gain already passed?
Most Popular Narrative: 3% Undervalued
Veralto closed at $111.10 against a widely followed fair value narrative of $114.00, so the recent rally still sits just below that anchor. The gap is small, but the story behind it leans heavily on recurring cash flows from water and packaging workflows rather than a one off quarter.
Robust and accelerating demand for water reuse, analytics, and treatment solutions driven by global water scarcity, rising regulatory pressure, and sustainability goals is translating into strong volume sales growth across both industrial and municipal customers, pointing to sustained revenue and margin expansion.
See why 15 investors see Veralto as 3% undervalued.
The most followed storyline values Veralto using a discount rate of 7.24% and arrives at that $114.00 figure, which is only about 2.5% above the last close. That narrow gap signals that expectations for water demand, digital workflows and cost programs are already reflected in the current price. Any change in those pillars could quickly shift the perceived upside or downside.
Result: Fair Value of $114 (UNDERVALUED)
Still, the bullish fair value story for Veralto depends heavily on analyst forecasts for revenue growth and margin gains, as well as on investors continuing to pay a premium P/E multiple.
Find out about the key risks to this Veralto narrative.
Another View: Veralto On Earnings Multiples
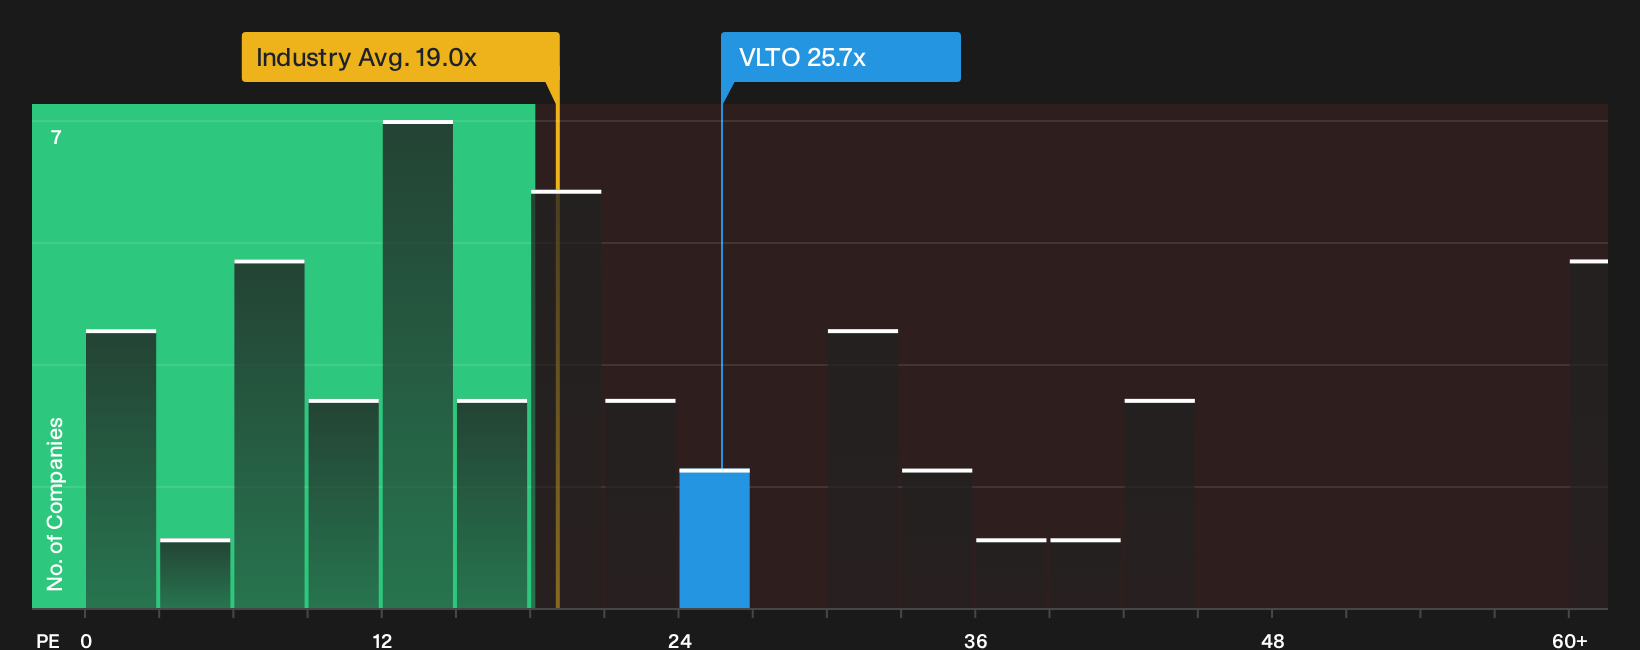
The story changes once the focus shifts from DCF to what investors are actually paying for Veralto today. The stock trades on a P/E of 27.4x, above the US Commercial Services sector at 19x and above its own fair ratio of 21.6x. That gap points to valuation risk if sentiment cools or growth assumptions soften, so how comfortable are you paying a premium for this cash flow profile?
To see how this premium stacks up against the underlying numbers and what the market might be pricing in, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Veralto is clearly improving, yet the mix of supporting data and open questions means your own judgment matters more than ever. Move quickly, examine the assumptions on both sides, and weigh the 3 key rewards against the 1 important warning sign highlighted in 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Veralto?
If Veralto sharpened your focus, do not stop here. Broaden your watchlist now with a few targeted screens that surface clear, differentiated setups.
- Hunt for quality at a discount by scanning companies that currently screen as 30 high quality undervalued stocks.
- Strengthen your income stream by zeroing in on resilient payers filtered through the 5 dividend fortresses.
- Protect your downside first by reviewing stocks that pass the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com