


EN
CAVA Group (CAVA) Opens New Restaurants As Earnings Near And Valuation Debate Builds
Earnings expectations meet new restaurant openings
CAVA Group (CAVA) is drawing attention as investors weigh its upcoming quarterly earnings against fresh expansion moves, including a new Greenfield, Wisconsin location that adds to the fast casual Mediterranean chain's growing footprint.
This mix of near term financial expectations and on the ground growth gives you two focal points. Quarterly numbers signal how the business is performing today, while the latest openings show how management is trying to build CAVA Group's presence across the United States.
Over the past year, CAVA Group’s 9.3% total shareholder return contrasts with a 3-year total shareholder return of about 63.5%. The share price, now at US$58.74, shows mixed momentum, with a strong 7-day share price return of 9.8% alongside a 90-day share price decline of about 10%.
Recent headlines around the Greenfield opening, a planned Madison location in mid November, and an upcoming earnings release on November 4 have kept attention on how fresh restaurant growth and shifting earnings expectations are influencing both sentiment and perceived risk around the stock.
Spot 18 high quality undiscovered gems that, like CAVA Group, pair expanding footprints with growing revenue and earnings profiles.CAVA Group’s share price has sprinted ahead over the past week while still trading well below the average analyst target. The real puzzle is where fair value sits between that recent move and the broader range of estimates.
Most Popular Narrative: 29% Undervalued
CAVA Group’s widely followed valuation story pegs fair value at about $82.75 per share, well above the last close at $58.74. This puts the current rally and upcoming earnings into sharper focus for anyone weighing risk against potential upside.
Current valuation implies the share price already reflects continued rapid unit growth, solid restaurant level margins in the mid 20s and effective use of cash including the US$100m buyback, so the stock appears priced for strong execution rather than for disappointment.
See why 73 investors see CAVA Group as 29% undervalued.
Result: Fair Value of $82.75 (UNDERVALUED)
Still, the bullish CAVA Group story can unravel if new locations outpace leadership depth or if food safety issues resurface and significantly reduce customer traffic.
Find out about the key risks to this CAVA Group narrative.
Another View: CAVA Group looks expensive on earnings
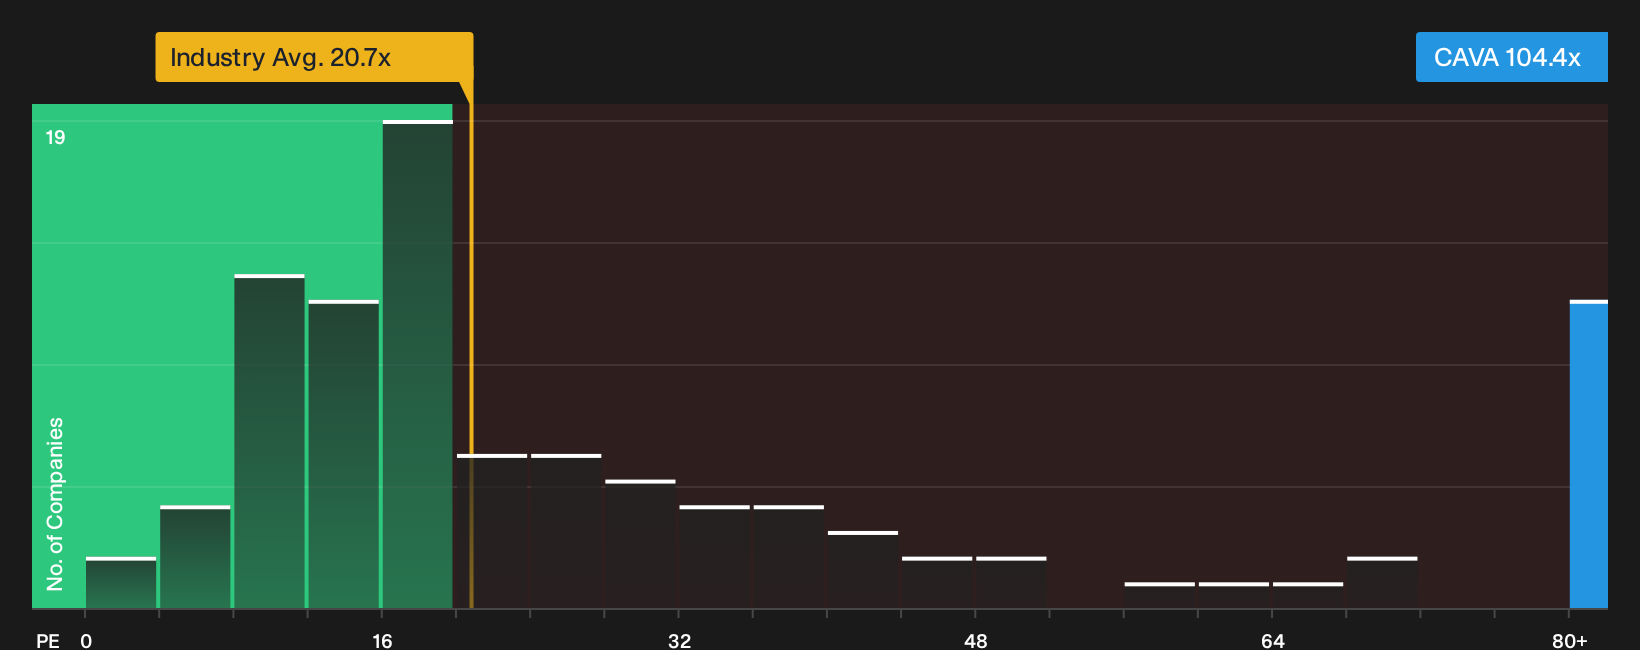
The story changes once you step away from that US$82.75 fair value and look at simple earnings multiples. CAVA Group trades on a P/E of 104.4x, far above both its peer average of 32.2x and the US Hospitality sector at 20.7x, while the fair ratio sits at 27.5x.
That kind of gap means even small disappointments could matter for anyone focused on shorter holding periods. A move toward the fair ratio would rely more on sentiment resetting than on new profit data, which raises the question of how comfortable investors are paying over 100x earnings for this growth story.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether CAVA Group’s story skews more toward opportunity or risk right now? Move quickly, pull up the data, and weigh both sides using 1 key reward and 1 important warning sign.
Looking for more CAVA Group style investment ideas?
If you only stop at CAVA Group, you could miss other compelling opportunities that match your risk comfort and return goals across different corners of the market.
- Target quality-first opportunities by scanning a list of solid balance sheet and fundamentals (23 results) that can handle shocks better than weaker peers.
- Zero in on potential mispricing by checking a 30 high quality undervalued stocks that combine robust fundamentals with market skepticism.
- Strengthen the income side of your plan by reviewing a short list of 6 dividend fortresses that aim for yield without ignoring resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com