


EN
What Is Drawing Fresh Attention To Richelieu Hardware (TSX:RCH)?
Index inclusion puts Richelieu Hardware in dividend spotlight
Richelieu Hardware (TSX:RCH) has just been added to the S&P/TSX Canadian Dividend Aristocrats Index, a move that can pull the stock onto the radar of dividend-focused funds and rules-based mandates.
Recent trading has been mixed. Richelieu Hardware’s share price is CA$37.94 after a 1-day share price return of 1.47%, while the 30-day and 90-day share price returns of 4.26% and 6.99% suggest momentum has picked up despite a year-to-date share price return that is down 4.82%. Over a longer horizon, investors have received a 2.21% total shareholder return over 1 year, but total shareholder returns over 3 and 5 years are down 5.44% and 7.24% respectively. The index inclusion therefore arrives at a time when the market’s view on the stock’s long run appeal is still rebuilding.
Compare Richelieu Hardware’s new dividend spotlight with other income-focused opportunities by scanning our hand picked 3 dividend fortresses that meet strict yield and stability criteria.
Richelieu Hardware now trades in the dividend spotlight after a stretch of muted long term returns. Has the recent index driven enthusiasm already priced in most of the upside, or is the bigger rerating still ahead?
Preferred P/E of 22.5x for Richelieu Hardware: Is it justified?
On simple earnings terms, Richelieu Hardware trades on a P/E of 22.5x, which leaves the stock looking expensive relative to both its own fair ratio and direct peers, even as the share price sits at CA$37.94.
The P/E ratio links the current share price to earnings per share. For a distributor such as Richelieu Hardware, this yardstick helps you judge how much investors are willing to pay for each dollar of profit in a relatively mature industrial niche.
Richelieu Hardware is described as good value when stacked up against the wider North American Trade Distributors industry average of 24.1x P/E. However, that comfort fades when you compare the same 22.5x multiple to a peer group average of 13.6x. The gap to an estimated fair P/E of 18.2x is even starker and points to a level that the market could move towards if sentiment cools.
Explore the SWS fair ratio for Richelieu Hardware.
Result: Price-to-earnings of 22.5x (OVERVALUED)
Still, Richelieu Hardware faces pressure if earnings growth slows or peers re-rate lower. This could challenge a premium P/E and temper index-driven enthusiasm.
Find out about the key risks to this Richelieu Hardware narrative.
Another view on Richelieu Hardware’s value
The earnings multiple paints Richelieu Hardware as expensive, and the SWS DCF model points in the same direction. At CA$37.94, the share price sits above an estimated future cash flow value of CA$28.58, which implies limited valuation cushion if sentiment or earnings expectations soften.
Investors who want to see how sensitive that output is to different assumptions can Look into how the SWS DCF model arrives at its fair value.
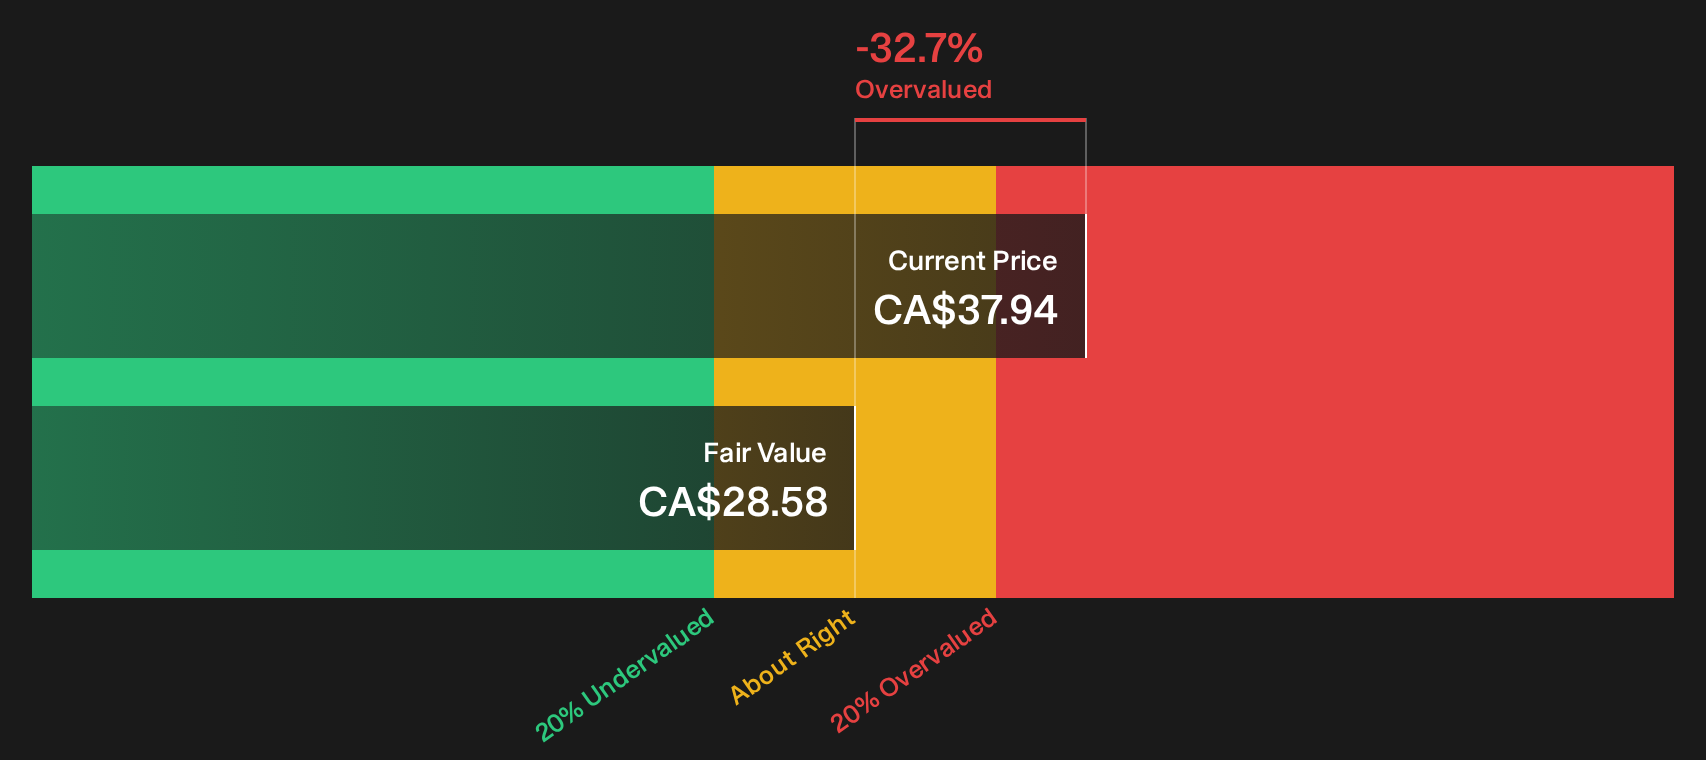
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Richelieu Hardware for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 4 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals run through the Richelieu Hardware story, so if this move onto the dividend radar has your attention, act quickly and check the underlying data for yourself, then weigh both sides of the argument with the 1 key reward and 1 important warning sign
Looking for more investment ideas beyond Richelieu Hardware?
If Richelieu Hardware has sharpened your focus on quality and valuation, use this momentum to review a broader watchlist and refresh your next set of ideas.
- Target stronger value potential by scanning a curated pool of resilient businesses through the 4 high quality undervalued stocks.
- Lock in greater balance sheet resilience by reviewing companies screened in our list of solid balance sheet and fundamentals (6 results).
- Get ahead of the crowd by checking a focused 8 high quality undiscovered gems before other investors start paying attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com