


EN
Earnings Beat Could Reshape The Case For Western Digital Stock
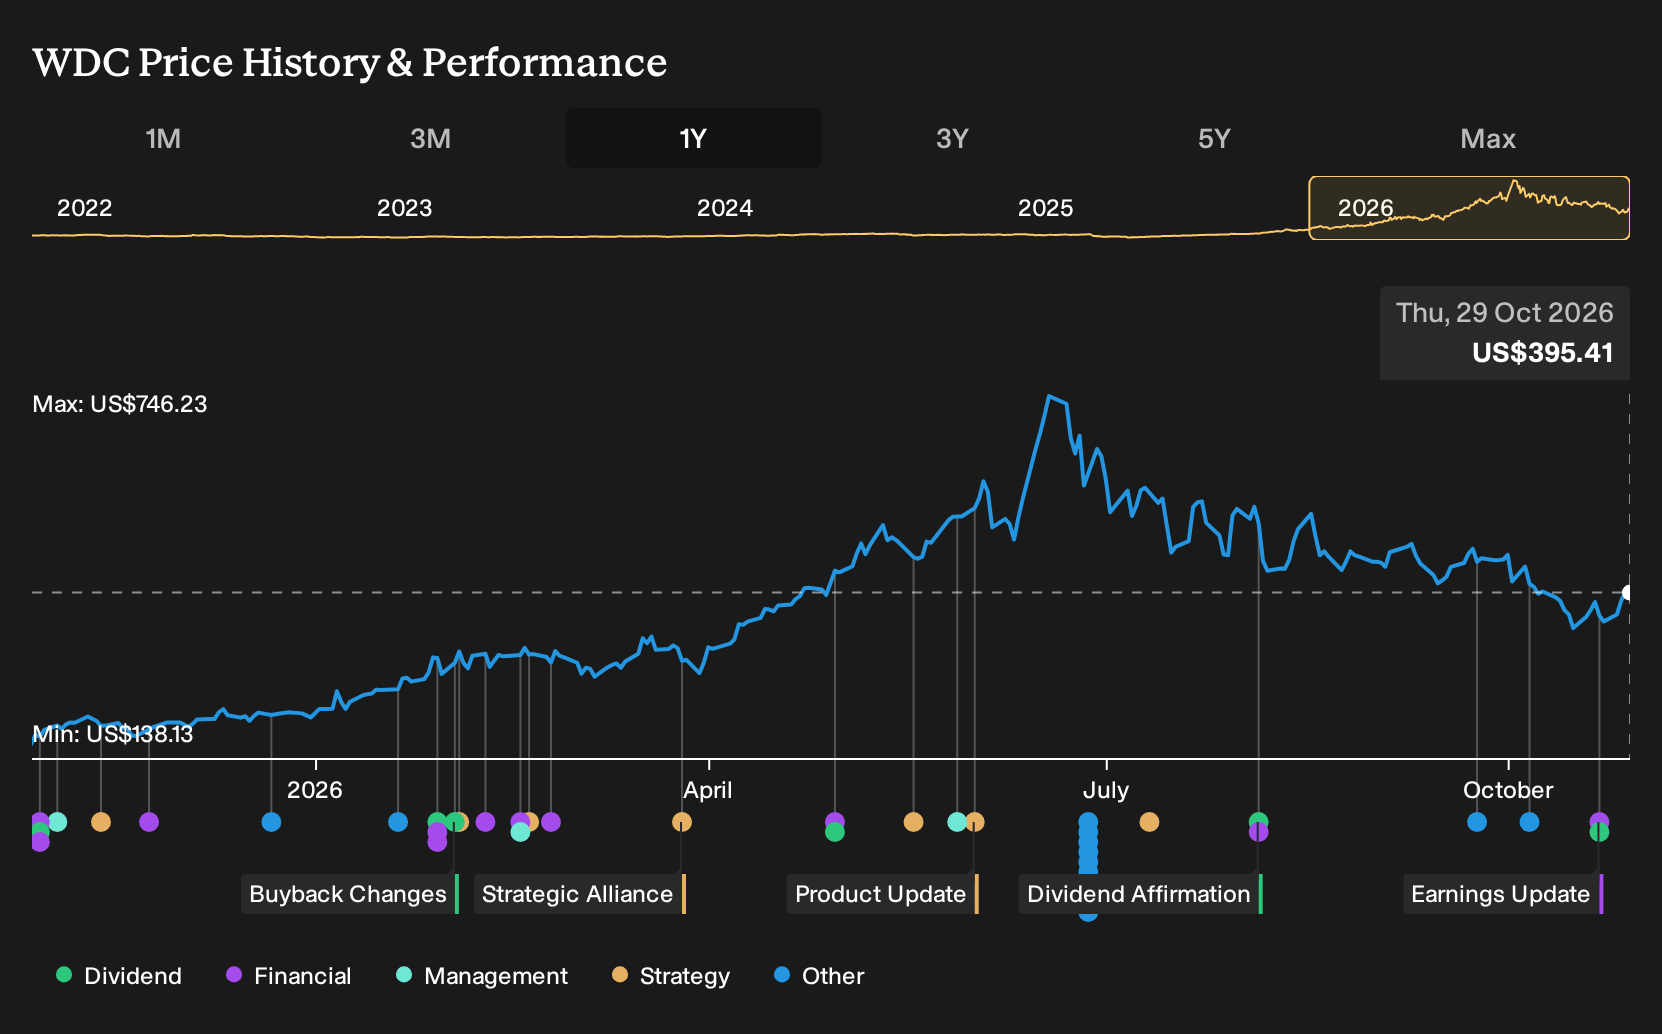
- Western Digital reported fiscal Q1 2027 sales of US$4.381b and net income of US$1.779b, with basic EPS from continuing operations of US$4.86 and a 17% higher quarterly dividend of US$0.175 per share announced for payment in December 2026.
- Results were heavily driven by demand for high-capacity storage in AI infrastructure, with management highlighting better demand visibility, favorable pricing and a product roadmap that leans on new technologies such as HAMR to support future shipments.
- This article examines how Western Digital's AI driven storage earnings may influence the existing investment narrative around margins and growth.
Scan how Western Digital's AI driven momentum compares with other storage and chip plays by reviewing the hand picked 54 AI infrastructure stocks benefiting from similar demand trends.
Western Digital Investment Narrative Recap
For Western Digital shareholders, the big belief is simple: AI and cloud workloads keep pushing storage requirements higher, and the company keeps filling that need with higher capacity HDDs at attractive economics. The latest quarter fits that story, with US$4.381b in sales and US$1.779b in net income supported by strong AI driven demand.
The key short term swing factor is whether Western Digital can hold pricing and cost per terabyte as it ramps newer technologies like HAMR and ships more high capacity drives. Execution hiccups or a weaker pricing backdrop would matter, especially with a major competitor already in market on 44TB HAMR products.
The dividend increase to US$0.175 per share, up 17%, is the announcement that really ties into this earnings print. It feeds directly into the thesis that Western Digital is producing enough cash from AI led demand to both invest in next generation drives and return money to shareholders.
For you as an investor, that higher payout sharpens the focus on cash generation, capital allocation discipline, and resilience through a storage cycle. If margins were to compress as HAMR ramps or if pricing softened, sustaining both investment needs and the dividend at this level could become the pressure point to watch.
Western Digital AI Storage Assumptions And Valuation Setup
Western Digital's narrative projects US$31.9b revenue and US$16.0b earnings by 2029. Analysts are building this on 35.2% yearly revenue growth and an earnings increase of about US$6.7b from US$9.3b today.
Discover how Western Digital's fair value indicates a 65% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
For Western Digital, the alternate view that matters most here is pricing pressure. The most bearish analysts already worked off a story where cloud buyers gain leverage and kept their models to roughly US$29.5b revenue and US$16.3b earnings by 2029. That is far more cautious. These Q1 results could prompt both camps to revisit their assumptions, so treat this as your cue to compare several narratives, not just one headline number.
Explore 6 other Western Digital fair value estimates, including one that suggests there could be as much as 17% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Western Digital research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Western Digital. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Western Digital's overall financial health at a glance.
Looking For More Western Digital Style Ideas?
If Western Digital's AI driven storage story has sharpened your thinking, you can use that same lens across the wider market. The Simply Wall St Screener can help you quickly surface other stocks that fit different risk, quality, and income profiles without getting buried in noise.
- If you care most about valuation and underlying quality, start with a focused group of companies screened as 30 high quality undervalued stocks that could merit a closer look on your watchlist.
- If balance sheet strength matters more to you than headline growth, you can focus on businesses from the list of solid balance sheet and fundamentals (23 results) to see which ones line up with your risk limits.
- If income is your priority, you can scan the 7 dividend fortresses to find yields that might complement a total return approach anchored by AI and storage exposure.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com