


EN
DoorDash (DASH) Stock May Be Above Fair Value As Grocery Deal Looms
DoorDash shares have more than doubled over the past three years, yet the stock is currently down sharply over the past year, which puts fresh attention on whether recent earnings can still support the price you see on screen. With a headline acquisition agreement for Instacart and a push into drone delivery now shaping the story, the real question is how much of that potential is already baked into what you are paying for DoorDash today.
- Over the past three years, DoorDash has delivered a return of about 104%, so anyone looking at the stock today is effectively judging whether that kind of rerating can be backed up by the company’s earnings power.
- The planned US$17b purchase of Instacart may support higher long run profit expectations by pairing DoorDash’s restaurant reach with a much larger grocery footprint, while also raising questions about future integration costs and the timing of any earnings uplift.
- The analysts covering DoorDash have run their own numbers. See what analysts think DoorDash's shares could be worth.
The issue now is whether DoorDash’s current share price, after that three year run and the Instacart deal announcement, is justified by the earnings the business is generating today and is expected to produce over time.
If you want to test the same earnings question you are asking of DoorDash across a wider field, run the numbers on 30 high quality undervalued stocks.
Does DoorDash Look Pricey on Earnings?
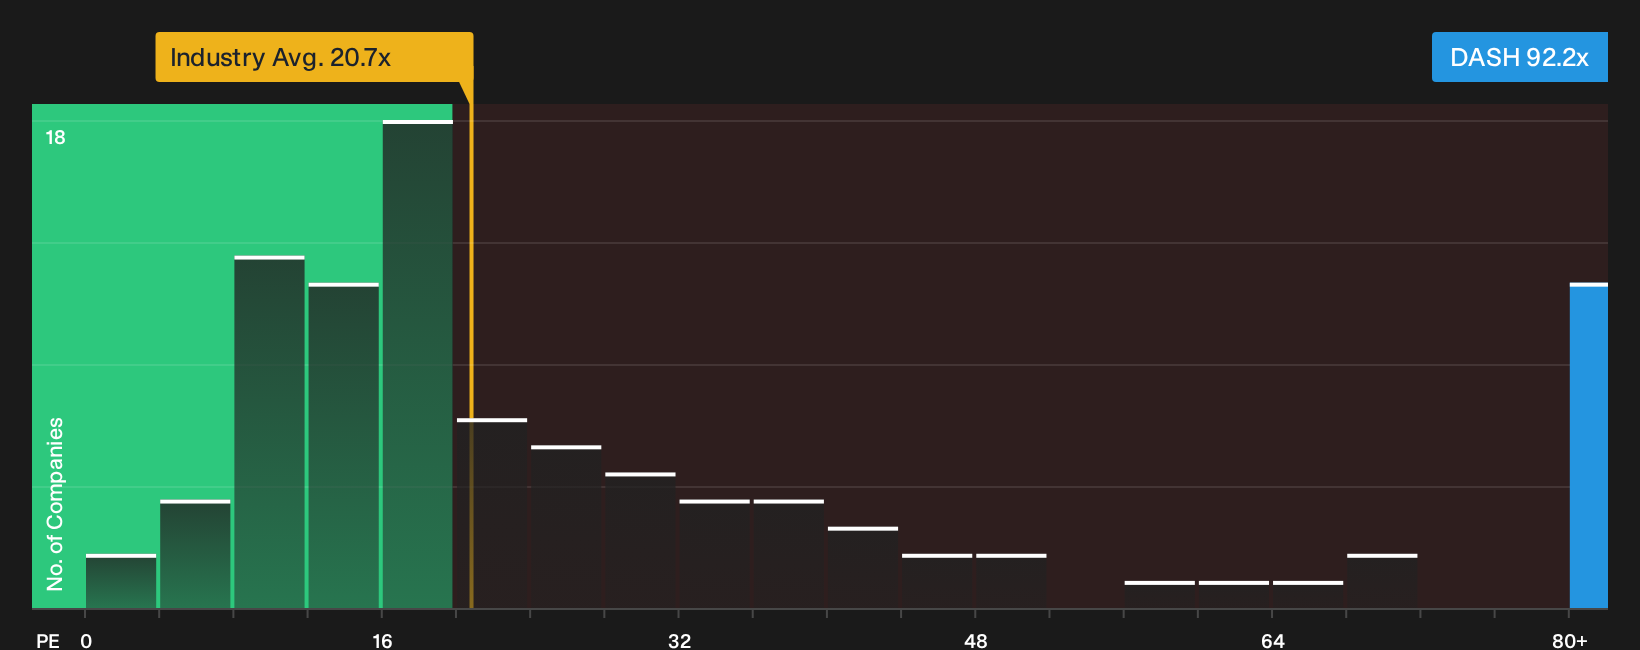
The P/E ratio is the cleanest way to see what you are paying today for each dollar of DoorDash earnings. On this yardstick, the stock trades on about 92.2x, which is almost three times the broader hospitality industry average of roughly 20.7x and also a steep premium to the peer group near 31.7x.
The fair P/E range implied by DoorDash’s own fundamentals model comes out materially lower, so the current 92.2x sits above what that framework would flag as justified and screens as overvalued on this metric. Because the market has already reacted to the Instacart deal news with a stronger share price, that richer multiple suggests investors are paying today for a lot of integration success and future profitability. Explore the numbers behind DoorDash's P/E valuation.
The DoorDash Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the DoorDash valuation puzzle leaves off. They spell out which assumptions on growth, profitability and earnings would need to play out for the stock to be worth meaningfully more or less than today's price, and instead of a single P/E or model result, each one lays out its own fair value logic so you can see how those inputs line up with DoorDash's reported numbers over time.
One of the top community narratives on DoorDash: 30% undervalued
Record performance of DashPass and Wolt+ subscriptions supports a growing base of recurring, higher margin revenue and higher gross profit per MAU...
Discover why this Narrative puts DoorDash at 30% undervalued.
DoorDash’s price is only one piece of the decision
Before treating DoorDash as just an earnings and multiples story, it is worth checking the underlying risk checks that have triggered concern in our research, since those could change how you weigh everything else. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com