


EN
What ExxonMobil Doubters Overlooked
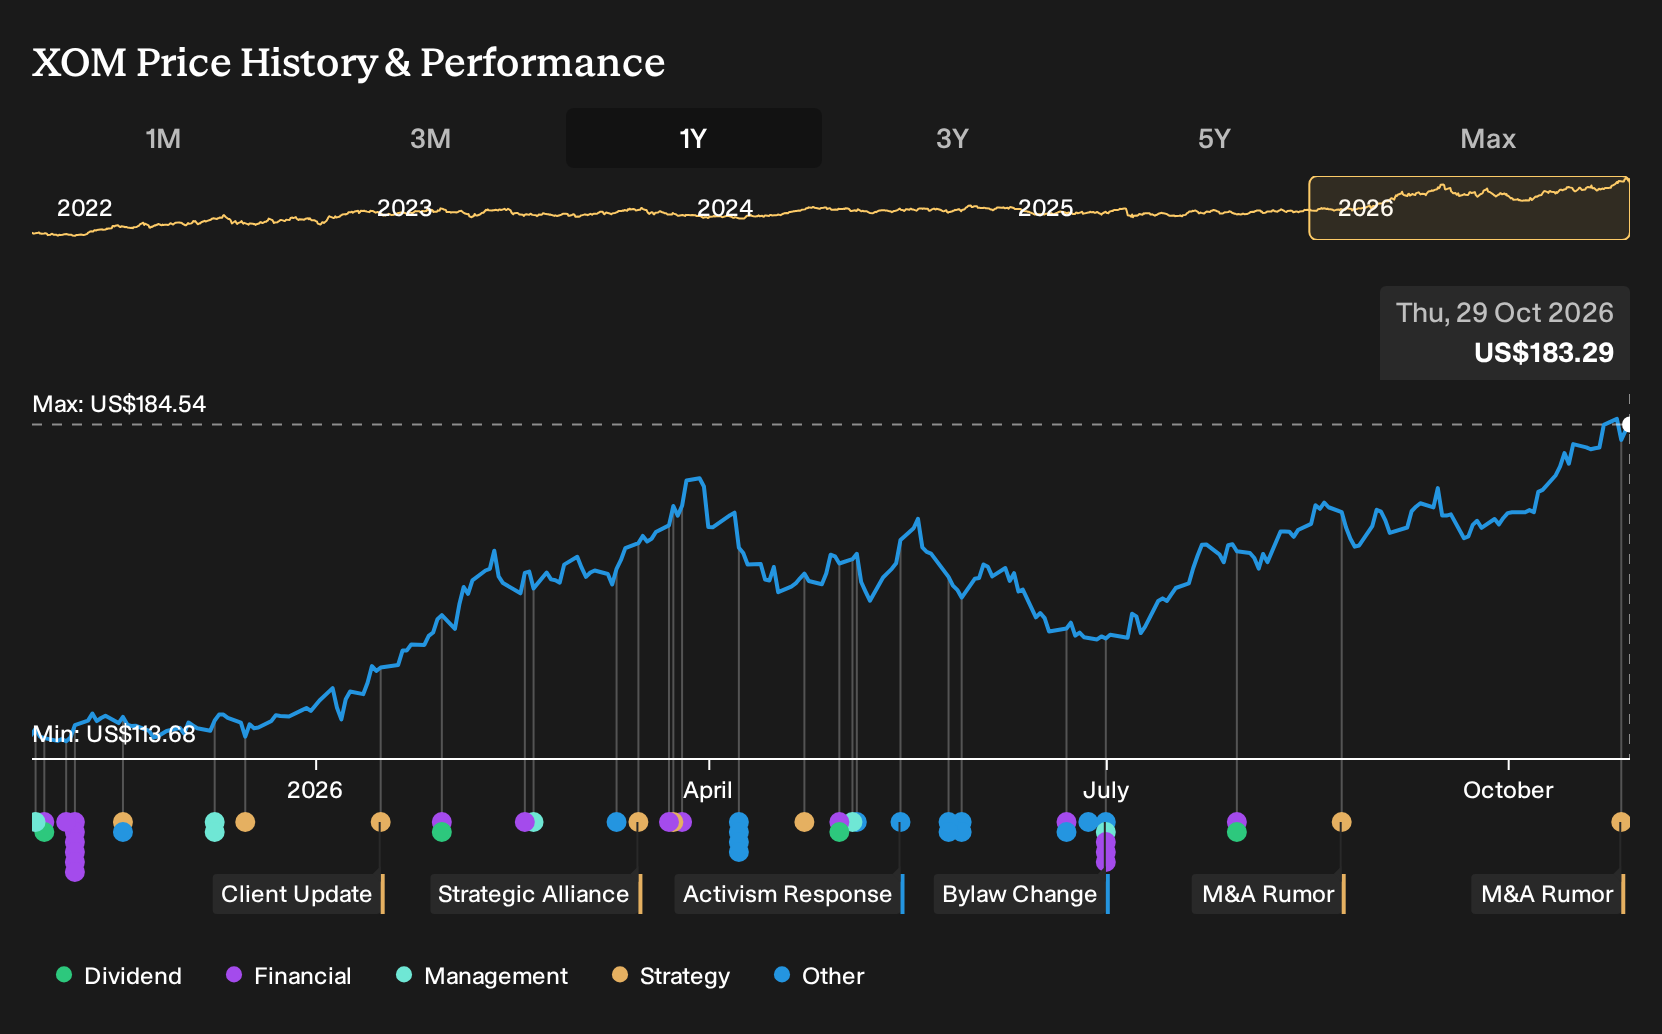
ExxonMobil’s latest quarter put something very tangible on the table, with record production feeding into higher earnings and yet another dividend check on the way. For ExxonMobil shareholders, the return over the past year was 64.4%, including dividends. If you were weighing a buy back on 29 October 2025, what would you have needed to believe about Guyana, the Permian and capital returns to take that risk before these results arrived?
If the move has made ExxonMobil harder to judge, start where the gap is still open and scan 30 high quality undervalued stocks.
The Two ExxonMobil Stories Investors Were Arguing About
The shares cost US$116 at the start of the period, so anyone buying ExxonMobil then had to pick a side in a live debate about its future.
On the bullish view, the fair value sat at US$124. This price was implied by faith that Guyana and the Permian would lift volumes and net margins as advanced technologies reshaped recovery efficiency and the cost base.
The bearish narrative put fair value at US$78. This was based on expectations that reliance on fossil fuel revenues and a tough energy transition would drag revenue growth by 1.0% a year and hold profit margins near 7.9%.
What The Results Changed For The ExxonMobil Debate
The clearest new fact is ExxonMobil’s Q2 2026 report, where revenue moved from US$79,477m to US$114,529m and net income from US$7,082m to US$14,525m. Net margin shifted from 8.9% to 12.7%. That combination, alongside record output in Guyana and the Permian, aligned more closely with the optimistic thesis. At the same time, geopolitical risks and derivative losses reminded investors that the cautious story had not disappeared.
The lesson is simple. When a bullish case leans on margin expansion and volume from specific assets, treat those as the first claims to test. Track segment production and net margin in each set of reported numbers instead of relying on share-price moves to answer the question for you.
What ExxonMobil’s Price Is Asking You To Believe Now
ExxonMobil trades at US$183 today. The selected Narrative’s Fair Value sits above the current price and leans on a story of lower cost barrels, stronger refining earnings and a wider role for lower carbon projects across the portfolio.
On that view, the market still does not fully credit the shift toward advantaged production, cost savings from data and automation, and new technology led product lines.
"Shift toward lower cost, higher return production as advantaged assets in Guyana, the Permian and LNG move toward roughly 65% of total output by 2030. This can influence revenue resilience and unit earnings across future cycles."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Looking Beyond ExxonMobil’s Rigs
ExxonMobil spends heavily on rigs, pipelines and complex development plans. You could also look at the other side of that equation.
Every well drilled in the Permian needs access to the underlying rock. Somebody controls those mineral rights and collects a slice of production.
Instead of funding drilling programs, that owner waits while operators spend the capital. The checks arrive when wells on that acreage start producing.
It is a very different risk profile from ExxonMobil’s. The interesting question is how you judge an asset that lives in the ground while others decide when to tap it.
That argument has a Narrative and a number behind it. → See the company one Narrative values 20% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com