


EN
What Myers Industries (MYE)'s Sales Growth And Net Loss Means For Shareholders
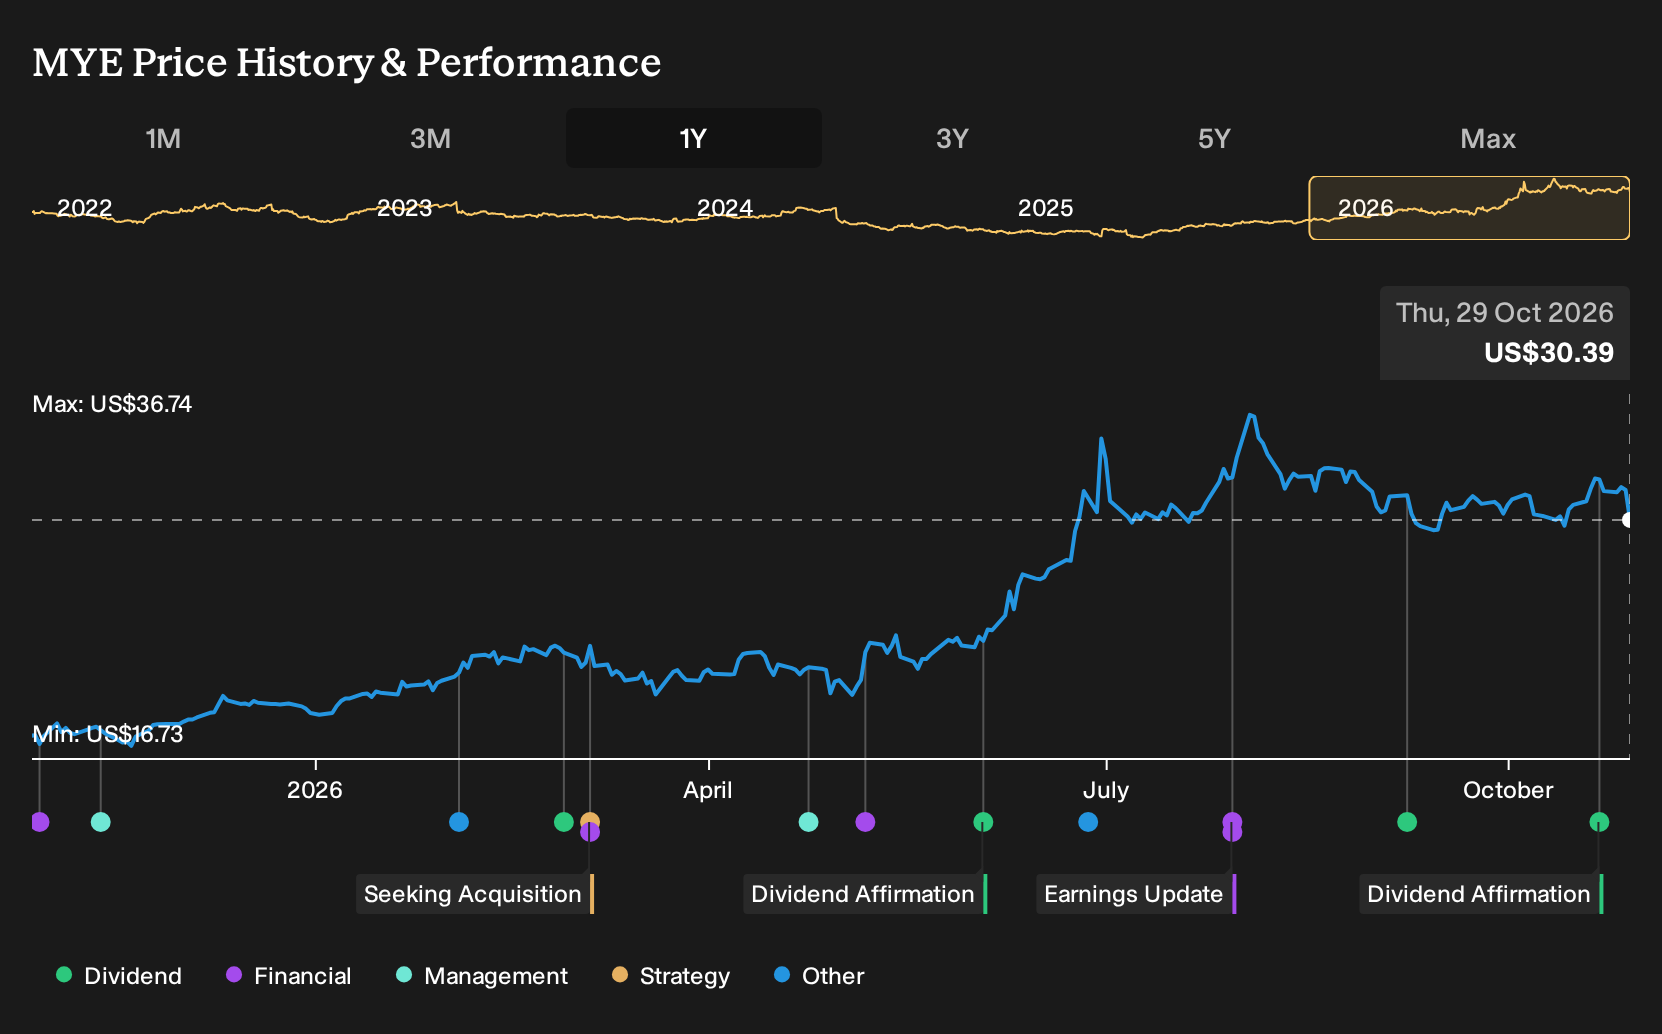
- Myers Industries reported third quarter 2026 sales of US$171.34 million and a net loss of US$0.865 million, and affirmed a US$0.135 quarterly dividend payable in early 2027.
- The mix of higher revenue but a quarterly loss, compared with prior year profit, highlights pressure on profitability even as activity levels held up.
- This article examines how Myers Industries' mixed quarter, with higher sales but a net loss, reshapes the existing investment narrative.
Scan how Myers Industries' earnings wobble compares to peers by reviewing the hand picked list of solid balance sheet and fundamentals (23 results) that may handle profit pressure very differently.
Myers Industries Investment Narrative Recap
To own Myers Industries, you need to be comfortable with a story where higher value infrastructure and defense products offset pressure in RV and consumer exposed lines. The latest quarter showed sales at US$171.34 million but a small net loss of US$0.865 million. That mix keeps the spotlight on execution in composite matting and ammunition packaging rather than on pure volume growth.
The most important near term catalyst is how effectively Myers Industries manages costs and pricing against resin inflation and softer end markets. The quarterly loss, while modest, keeps margin resilience in focus. The largest current risk remains extended weakness in RV related demand combined with any delay in passing through higher input costs.
The earnings release for the third quarter and first nine months of 2026 is the key update to work with. Revenue for the quarter and year to date was higher than the prior period, while quarterly profitability slipped to a small loss and nine month net income fell to US$17.34 million from US$23.6 million. That split between top line and bottom line is where the story now lives.
This matters for the existing catalysts around portfolio simplification, infrastructure backlogs, and military packaging. Higher sales in the period suggest activity in those focus areas, while the earnings decline underlines that cost control and pricing remain critical. For you, the question is whether the margin pressure proves temporary or becomes a persistent drag on the thesis.
What The Current Myers Industries Forecasts Assume
Myers Industries' narrative projects US$677.3 million revenue and US$95.2 million earnings by 2029. Analysts are building this around a 7.1% yearly revenue decline and an earnings increase of about US$44.5 million from earnings today of US$50.7 million.
Discover why Myers Industries' fair value points to a 22% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community bracket Myers Industries between US$37 and about US$105 per share, a very wide spread for such a small sample. That gap sits against rising sales, a recent quarterly loss, resin cost risk, and reliance on infrastructure and defense orders. You should expect opinions to diverge and review multiple community viewpoints before forming your own stance.
Explore another Myers Industries fair value estimate, including one that suggests it could be worth just $37.00!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Myers Industries research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Myers Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Myers Industries' overall financial health at a glance.
Looking For More Investment Ideas Beyond Myers Industries?
If the Myers Industries story has sharpened your thinking about risk, income and valuation, it can help to line it up against other opportunities that share some of the qualities you care about most.
- Prefer to focus on quality at a reasonable price? Scan a 30 high quality undervalued stocks that meets strict fundamentals filters and might offer a more attractive entry point.
- Rely on portfolio income as a key part of your returns? Shortlist a group of 7 dividend fortresses that emphasise yield and payout consistency.
- Want to sleep easier during rough patches? Start with a 30 resilient stocks with low risk scores that screens for resilient balance sheets and lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com