


EN
Rocket Companies (RKT) Swings To Profit, Is It Still 25% Undervalued?
Rocket Companies (RKT) just released Q3 2026 results, reporting revenue of US$3.28b and net income of US$709m. The company moved from a loss a year earlier to a profit, drawing fresh attention to the stock.
Rocket Companies’ share price has reacted to the Q3 surprise, with a 1-day share price return of 3.03% and a modest 7-day gain of 1.53%. However, the year-to-date share price return is down 40.04%, and the 1-year total shareholder return is down 25.22%, so recent momentum is improving off a weak longer-term base.
Compare Rocket Companies’ earnings swing with hand-picked housing and financials peers by scanning the 30 high quality undervalued stocks screen that combines solid cash generation with sturdier balance sheets.
Rocket Companies has swung back into profit while the share price is still far below where it started the year. Is this a moment to step in, or a reason to wait for a cheaper entry before committing fresh capital?
Most Popular Narrative: 25% Undervalued
Rocket Companies is priced at $11.92, while the most followed narrative framework places fair value closer to $15.99. The gap between price and modelled worth is front and center for anyone reassessing Q3.
The move to a revenue mix where more than 70% comes from servicing, purchase, home equity, personal loans, Redfin and Rocket Money subscriptions shifts Rocket Companies further away from pure rate driven refinance exposure and can support a steadier base for revenue and earnings.
The build out of AI tools that cut prospecting time, raise conversion and support roughly US$300b of fixed origination capacity with fewer production staff gives Rocket Companies room to add volume without matching growth in expenses, which can support net margins.
What is behind 35 investors see Rocket Companies as 25% undervalued.
Result: Fair Value of $15.99 (UNDERVALUED)
Still, the narrative around Rocket Companies can break if mortgage rates stay elevated and housing activity remains soft, or if Redfin and Mr. Cooper integrations underdeliver.
Find out about the key risks to this Rocket Companies narrative.
Another View: Rocket Companies On Earnings Multiples
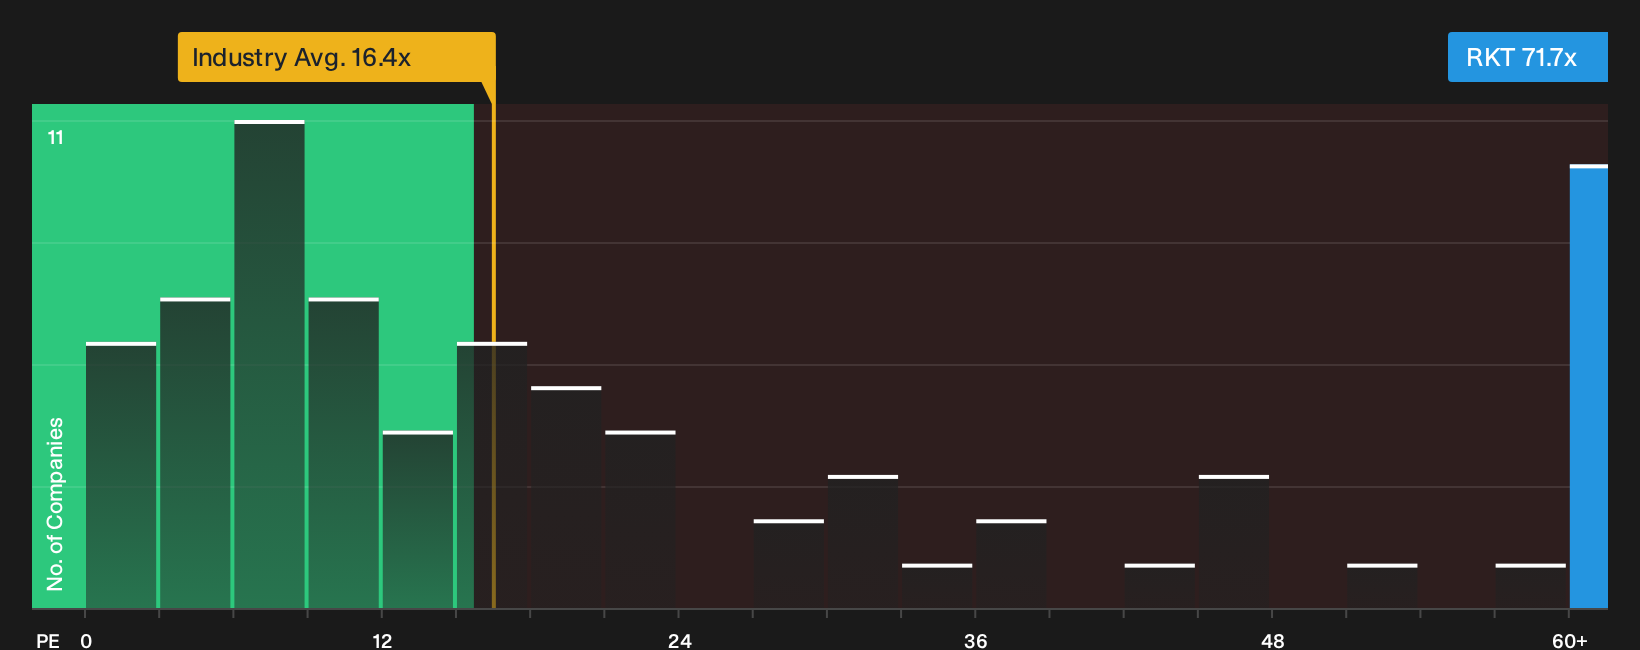
The fair value story for Rocket Companies leans on detailed cash flow work, yet the P/E snapshot tells a tougher story. At 71.7x earnings, the stock trades at more than 4x the US Diversified Financial industry on 17x and well above its own fair ratio of 26.7x.
That kind of gap leaves less room for error if margins or growth fall short, because the share price already assumes a rich outcome. The question for investors is simple. Does the quality of earnings and future growth outlook justify paying such a premium multiple?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on valuation and risk can easily pull you in opposite directions, so move quickly and stress test the thesis yourself by weighing the 4 key rewards and 1 important warning sign.
Looking for more Rocket Companies style investment ideas?
If Rocket Companies has sharpened your focus, do not stop here. Use targeted stock screens to surface fresh ideas before the crowd reaches them.
- Target resilient compounders by scanning a list of solid balance sheet and fundamentals (23 results) that can help you filter for financial strength before headlines catch up.
- Hunt for mispriced opportunities using a 18 high quality undiscovered gems and spot quality businesses that wider markets may not be paying attention to yet.
- Prioritise sleep at night holdings by running a 30 resilient stocks with low risk scores designed to highlight companies with more muted risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com