


EN
Naturgy (BME:NTGY) Q3 Results Reveal Margin Pressure Behind Solid Earnings
Naturgy Energy Group stock closed at €29.66 on 30 October, with a flat month behind it and only a small slip over the past week. Q3 2026 results then landed with a clear message. Earnings power held solid while the pressure point sat in profitability.
For an integrated gas and power utility, a net profit margin near 10% and quarterly net income of €543 million matter more than the short term price flicker. The immediate reaction focused on headline earnings per share softness. The longer view is now shifting to whether these margins can hold against forecast revenue and earnings trends over the coming years.
Love Naturgy Energy Group's solid net income but concerned about the pressure on profitability ratios? See how that trade off compares across a list of solid balance sheet and fundamentals stocks (202 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): €5,277 million vs. €4,625 million (up about 14.1%)
- Net Income (Q3 2026 vs Q3 2025): €543 million vs. €521 million (up about 4.2%)
- Basic EPS (Q3 2026 vs Q2 2026): €0.586 vs. €0.739 (down about 20.7%)
- Net Profit Margin (Trailing 12 Months vs Prior Year): 10.4% vs. 10.0% (modest margin improvement)
Earnings tell one story, but if you care about what you are really paying for Naturgy Energy Group, the cash generation behind those profits matters just as much.
On Naturgy Energy Group's cash flows alone, the stock could be a solid 16% undervalued.
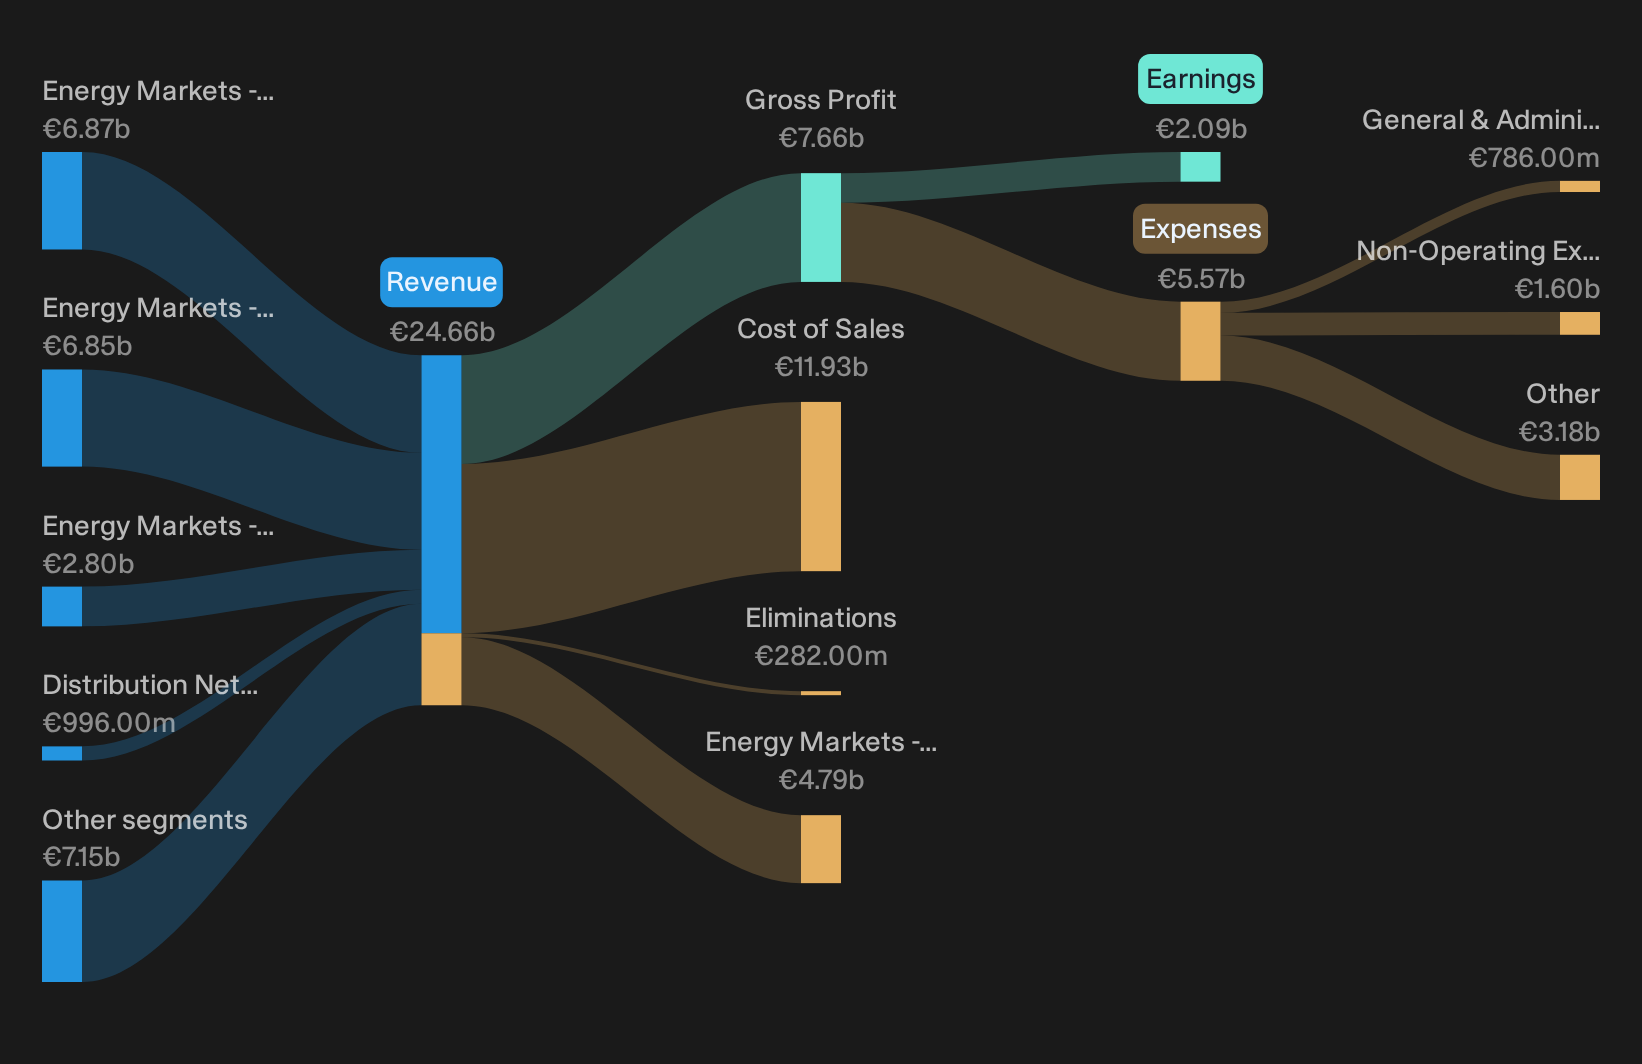
Resilient Naturgy earnings thesis on trial
The bullish view depends on Naturgy Energy Group turning its model and project pipeline into repeatable cash generation rather than one off strength.
"Analysts expect Naturgy Energy Group to keep using its integrated gas and power model, cost efficiency gains and upgraded earnings guidance to support a resilient earnings profile in volatile energy markets."
Q3 2026 numbers give that claim partial support. Revenue of €5,277 million and net income of €543 million both sit ahead of Q3 2025, and the trailing 12 month net margin edges higher to 10.4%. Basic EPS softness versus Q2 2026 shows resiliency is not uniform across quarters.
Naturgy risk narrative around supply and renewables
The bear case argues that weak links in supply and green power could slowly chip away at Naturgy Energy Group's earnings base.
"If pressure in Naturgy Energy Group's supply segment persists, with lower industrial gas demand, reduced regulated gas tariff margins and higher ancillary service costs, earnings from this part of the business could weaken further and weigh on consolidated EBITDA, net income and cash generation."
Q3 2026 net income of €543 million and a 10.4% trailing margin do not show visible deterioration at group level. Basic EPS declining versus Q2 2026, together with management commentary on margin pressure, suggests those segment headwinds are not fully neutralised either.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
Hunt For Quiet Fundamental Setups
Naturgy Energy Group shows how resilient earnings can reshape expectations for a business. The real opportunity is recognizing stocks that may be undervalued before the market revisits their fundamentals.
- Company 1 - 37% below our estimate - uses a recent acquisition, dealer consolidation and direct channels to steer demand into higher margin sleep and home comfort products.
- Company 2 - 32% below our estimate - redirects automated capacity toward composite cylinders and clean energy equipment that buyers prefer over legacy industrial packaging options.
- Company 3 - 43% below our estimate - supplies composite structures and aftermarket service bundles that aircraft programs adopt as they redesign cabins and mobility platforms.
That is three of the list. See every one of the 201 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com