


EN
Toronto-Dominion Bank (TSX:TD), What Is Behind The Fresh Attention?
Why TD’s new app feature matters for the stock
Toronto-Dominion Bank (TSX:TD) has rolled out a new in-app journey that lets customers pull money from outside institutions straight into TD accounts through a single, guided process that removes several manual steps.
The upgrade builds on TD Digital Direct Deposit and leans into a clear theme. Management is using digital tools to make switching everyday banking to TD quicker, less messy and more attractive for both new and existing clients.
Toronto-Dominion Bank’s new in-app transfer flow lands at a time when momentum in the stock has clearly picked up. The share price sits at CA$178.13 after a 30 day share price return of 5.51% and a year to date share price return of 37.21%. The 1 year total shareholder return of 60.07% and 3 year total shareholder return of 153.14% point to investors rewarding the broader mix of digital upgrades, recent funding moves in the bond market and ongoing balance sheet deployment.
Scan how Toronto-Dominion Bank’s digital push compares with peers by reviewing our curated 8 resilient stocks with low risk scores, which is built around balance sheet strength and more resilient business models.
Toronto-Dominion Bank’s sharp re‑rating and digital push point to a business story, yet the speed of the move also hints at hotter sentiment. Which side carries more weight once the valuation is stripped back?
Most Popular Narrative: 1% Undervalued
On the most followed view, Toronto-Dominion Bank’s fair value of CA$180.07 sits just above the latest close at CA$178.13. As a result, the market is treating TD as almost fully priced while still leaving a small implied gap for the story to play out.
The main requirement is that TD turns its strong capital position and large AI and cost reduction programs into sustained efficiency improvements that more than offset higher AML remediation and growth spending.
The current valuation implies the share price already reflects a fairly valued, bullish view on TD delivering record-level profitability with a CET1 ratio moving toward 13%, material buybacks of over $13 billion in 2027, and rising contributions from U.S. and wholesale businesses.
See why 186 investors see Toronto-Dominion Bank as 1% undervalued.
Result: Fair Value of CA$180.07 (UNDERVALUED)
Still, the story around Toronto-Dominion Bank can change quickly if U.S. AML remediation costs escalate further or if AI efficiency gains come in below current expectations.
Find out about the key risks to this Toronto-Dominion Bank narrative.
Another View: What TD’s P/E Ratio Is Telling You
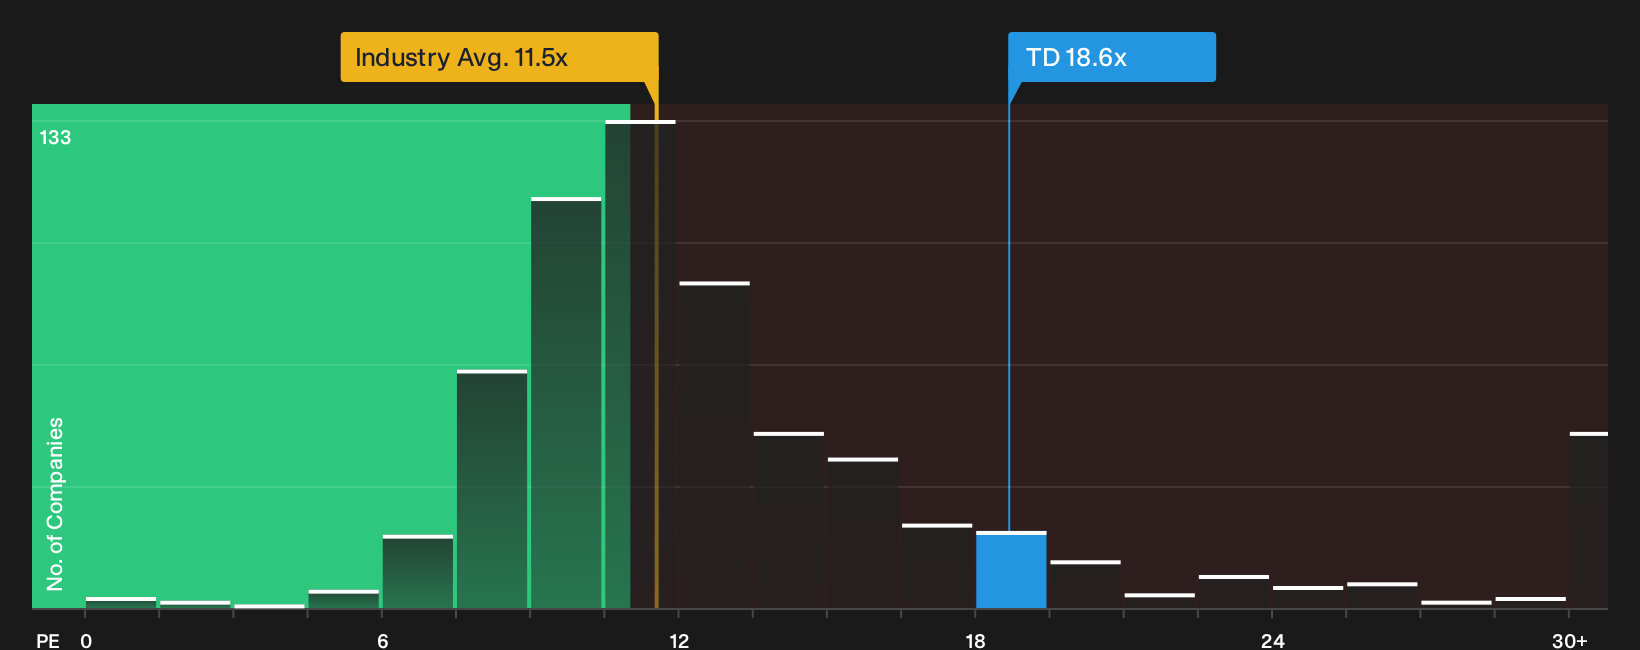
Toronto-Dominion Bank may look slightly undervalued on a fair value of CA$180.07, yet its current P/E of 18.6x sits above a fair ratio of 16.6x, the 17.6x peer average and the 11.5x North American banks level. That gap points to valuation risk if sentiment cools.
For a closer look at how earnings multiples and fair ratio interact with TD’s recent rerating, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Still unsure whether current optimism around Toronto-Dominion Bank feels justified or a touch over-heated? Act quickly to review the underlying data points, then pressure test that view against the 3 key rewards.
Looking for more investment ideas beyond Toronto-Dominion Bank?
Do not stop with one ticker when the market offers so many different angles. Broaden your watchlist with targeted screens that match what you care about most.
- Look for potential mispricings by scanning a curated set of companies flagged as having room in their valuation through the 4 high quality undervalued stocks.
- Strengthen your income stream by reviewing established businesses screened for higher yields and payout consistency using the 3 dividend fortresses.
- Prioritise resilience by filtering for companies with sturdier finances through the list of solid balance sheet and fundamentals (6 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com