


EN
IonQ (IONQ) Stock Looks Reasonable On Fresh Quantum Networking Funding
IonQ has been through a sharp reset in 2026, yet the share price still reflects a company that radically changed early investors' capital over the past few years. With that backdrop, the live question is whether the current valuation can be squared with what IonQ has built on its balance sheet, in particular its book value.
- Over the past 3 years, IonQ has delivered a total return of about 184.7%, which puts a lot of weight on whether the balance sheet can support that kind of re-rating.
- Fresh funding from the Air Force Research Laboratory and a focus on full stack quantum networking may support expectations for future contracts and capital spending needs that matter when you line the share price up against book value.
- The analysts covering IonQ have run their own numbers. See what analysts think IonQ's shares could be worth.
The issue now is whether IonQ's current share price around US$31.72 is adequately backed by its book value when compared with the industry average.
If you want to test the same book value question across a wider group of quantum computing plays, take a look at 25 quantum computing stocks.
Is IonQ Fairly Priced on Book Value?
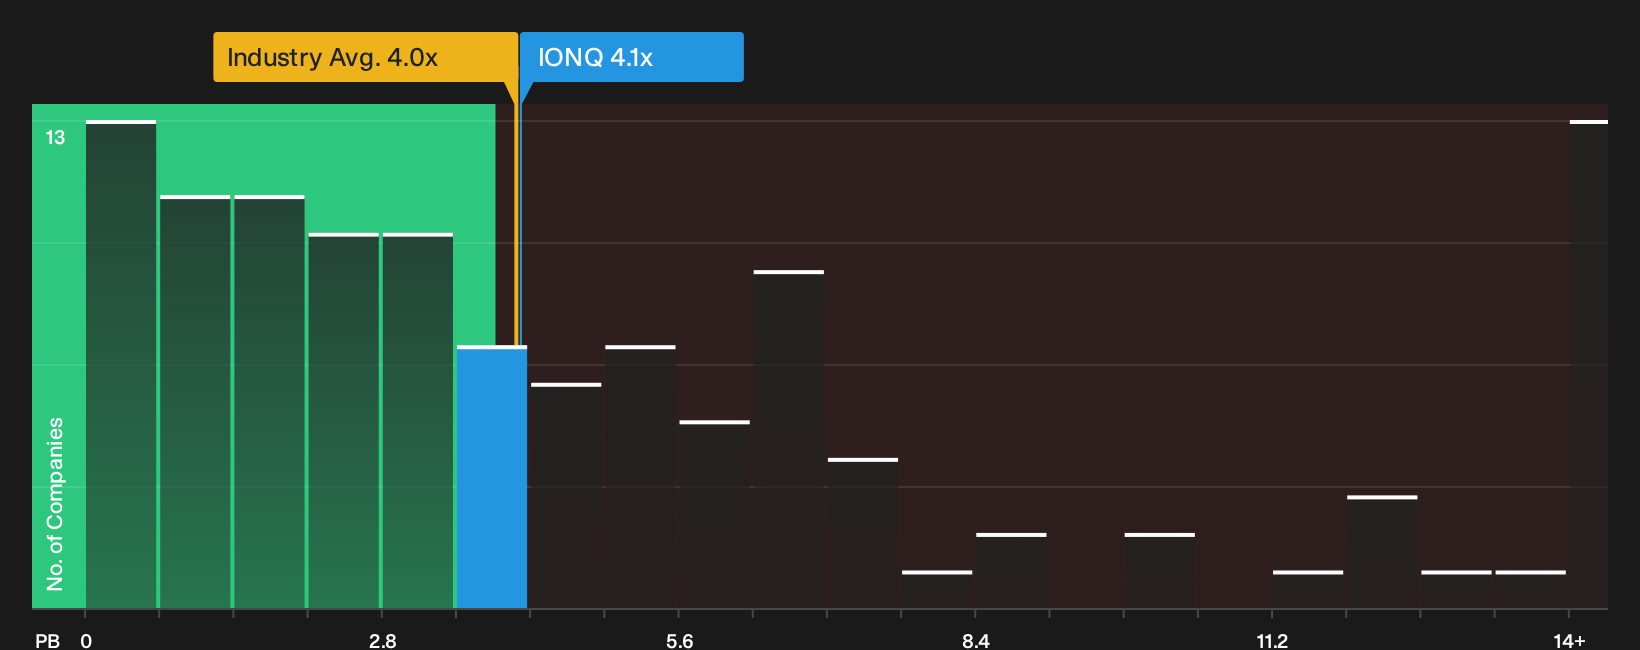
P/B suits IonQ because investors are still leaning more on its balance sheet and assets than on current earnings. On this lens, the stock trades on a P/B of about 4.1x compared with a semiconductor industry average near 4.0x. That is a very small premium and points to a market that is pricing IonQ roughly in line with the sector on a simple equity value basis.
Because the recent US$7.5 million Air Force Research Laboratory award gives IonQ more non dilutive funding for its quantum networking work, the modest P/B gap suggests investors are not paying a large extra mark up for that contract pipeline. For you as a shareholder, the key question is whether the assets already on the balance sheet and the quantum hardware and software platform they support justify paying around the sector norm on this metric. Explore the numbers behind IonQ's P/B valuation.
The IonQ Narrative: What Would Justify Today's Price?
Narratives sit between IonQ's book value puzzle and the live share price by spelling out which paths for growth, margins and future earnings would need to play out for the stock to be worth materially more or less than it trades for today on Simply Wall St's Community page. Instead of giving a single output like one ratio or model result, they map the future that figure relies on so you can later check whether IonQ's real progress lines up with those assumptions.
IonQ draws sharply different reactions, with community views splitting between a high conviction compounder and a story that the share price has already run too far.
Bull case: 63% undervalued
"IonQ has systematically de-risked its thesis, and is now fully funded to execute a "winner-take-all" land grab, positioning it as the potential "Nvidia of Quantum"…"
Discover why this Narrative puts IonQ at 63% undervalued.
Bear case: 527% overvalued
"At current prices, IonQ trades at well over 100 times revenue, a level rarely sustained even among the fastest growing technology companies…"
Explore why this Narrative puts IonQ at 527% overvalued.
IonQ’s price is only one piece of the decision
Book value and community narratives frame where IonQ is today, but analyst projections a few years out offer a different lens on what the business might become compared with today’s share price. Explore where analysts expect IonQ to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com