


EN
Will Strict Notice Deadlines Change QBE's (ASX:QBE) Narrative
- QBE Insurance Group recently won a Court of Appeal case in which a severely injured claimant was denied recovery because the policyholder breached the policy’s notification timeframes, confirming that such contractual deadlines can be enforced even without proof of harm to the insurer.
- This legal outcome underlines how routine wording around claim notifications can materially influence QBE Insurance Group’s ultimate claims exposure and the reliability of its underwriting assumptions on long tail liability business.
- The key question now is how this court decision around notification clauses might influence QBE Insurance Group’s broader investment narrative.
Scan how QBE Insurance Group’s court win on strict policy wording compares with other insurers that score highly on underwriting discipline within our curated 6 resilient stocks with low risk scores.
QBE Insurance Group Investment Narrative Recap
To own QBE Insurance Group today, you need to believe management can keep underwriting discipline tight, keep catastrophe losses within allowances and gradually pull expenses down with technology and portfolio reshaping. The recent court win on notification clauses supports that thesis by reinforcing contract certainty, but it does not change the near term earnings drivers on its own.
The more pressing swing factors remain claims inflation versus pricing, catastrophe activity in Australia Pacific and how quickly the expense ratio benefits from AI and automation show through. The biggest risk is that premium rate momentum softens while large losses or inflation stay sticky, which would put pressure on the combined ratio and returns.
There have been no fresh company announcements around this specific case, so the most relevant context is still QBE Insurance Group’s broader program of AI, automation and underwriting tools such as its Aurora engine and QCyber Rapid Pay offering. Those projects are aimed at faster claims handling, sharper risk selection and lower operating costs over time.
Set against that, management has acknowledged that expense ratio improvement has slowed because investment in modernization continues. That leaves execution risk if the savings arrive more slowly than hoped. For catalysts, the focus stays on evidence that these technology programs are improving cycle times and helping keep catastrophe and large loss experience within internal allowances.
QBE Insurance Group's current narrative assumes revenue growth of 4.2% per year, with the top line reaching $22.0b and earnings $2.2b by 2029, which implies flat consensus earnings relative to the $2.2b level today.
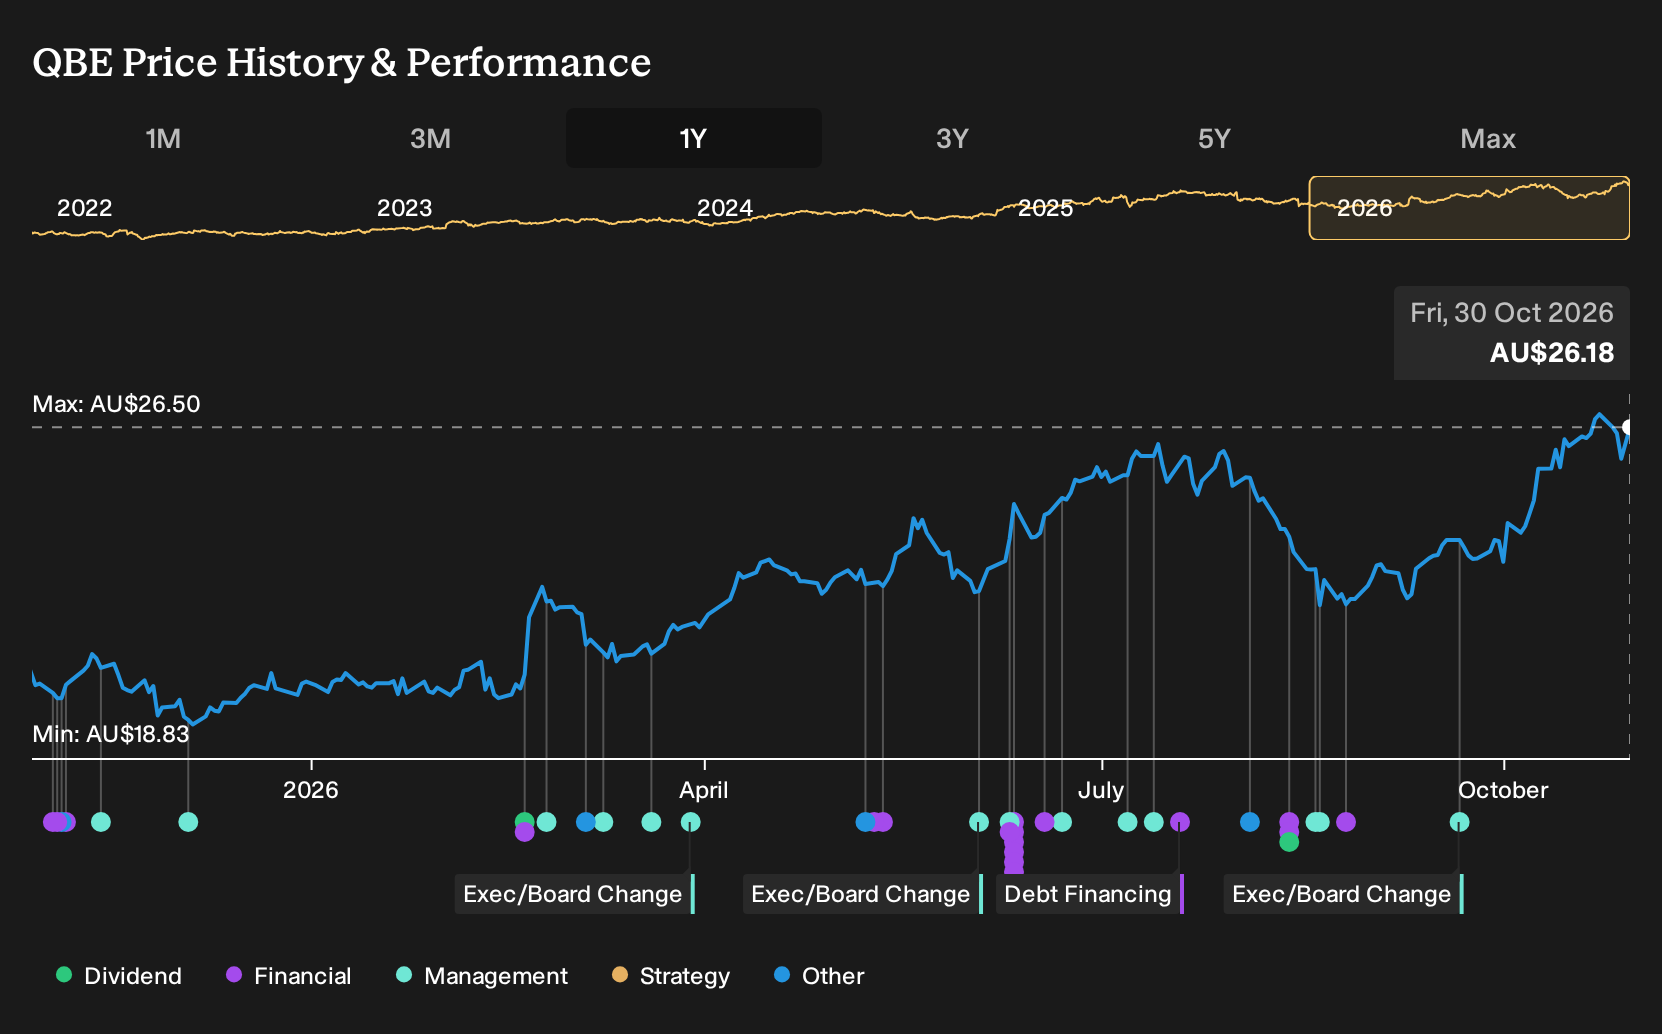
Uncover why QBE Insurance Group's fair value indicates a 5% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Some of the lowest ranked analysts see QBE Insurance Group’s court win through a different lens. You might focus on contract certainty, while they worry that heavier catastrophe exposure could matter more. Their pre news models sat at revenue of about $21.3b and earnings near $1.6b by 2029, so this ruling could prompt revised views.
Explore 5 other QBE Insurance Group fair value estimates, including one that suggests as much as 29% downside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your QBE Insurance Group research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for QBE Insurance Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate QBE Insurance Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond QBE Insurance Group?
If QBE Insurance Group has you thinking about underwriting quality, balance sheet strength and income resilience, it can help to line it up against a broader watchlist built using the Simply Wall St Screener.
- If you want a shortlist of companies where valuation looks more conservative, scan our curated set of 1 high quality undervalued stocks that combine quality fundamentals with pricing that may leave more upside than downside.
- For investors who care most about getting paid to wait, focus on income resilience by reviewing a hand picked group of 4 dividend fortresses that aim to pair higher yields with sturdier payout profiles.
- When capital protection is the priority, concentrate on resilience first and growth second by filtering for 6 resilient stocks with low risk scores that score well on financial strength and risk metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com